
Copper Stocks In Focus As New Recovery Tech Meets A 25% Supply Gap
Copper sits at the centre of a quiet tug of war between rising demand and a projected 25% supply shortfall by 2040, and now a biotech wildcard, Giraffe Bio, claims it can boost metal recovery from existing mines by up to 5%. That blend of scarcity risk and new processing tech could reshape which copper mining and processing stocks win. This article examines three companies exposed to that story.
The three copper mining and processing stocks below are only a starter pack, and the full Simply Wall St screen surfaced 65 more listed miners and processors with equally compelling narratives that are not covered here. To identify and analyze potential high‑conviction copper ideas directly, head straight into the Copper Mining and Processing Stocks screener.
Trekor Metals (TSX:TKO)
Trekor Metals is one of the clearest copper pure plays in this screen, with producing assets and projects tied directly to copper volumes. Its CA$4.6b market cap puts it firmly in the mid tier of global miners exposed to any step change in recovery tech.
"Although Florence Copper has reached its first full production quarter and is adding EBITDA for Trekor Metals, the reduction in 2026 guidance to 25 to 28 million pounds of copper from an earlier 30 to 35 million pounds target suggests ramp up risks that could leave future revenue and earnings below what higher volume assumptions would have implied."
What happens to Trekor Metals’ earnings power now largely hinges on how a single cost and productivity pressure at its copper assets resolves.
That single pressure point could either cap Trekor Metals’ potential or set up a sharp earnings reset, and the full narrative for Trekor Metals lays out how that risk could turn into upside.

Hindustan Copper (BSE:513599)
Hindustan Copper is a pure-play copper miner and processor in India, running exploration, mining, smelting and refining operations that fit squarely inside the Copper Mining and Processing Stocks theme. It generated about ₹34,981 million from manufacturing and selling copper products and carries a market value near ₹453.0 billion.
Hindustan Copper provides direct exposure to copper ore and metal processing, with earnings and margins tied closely to how much copper it can mine, refine and sell into a market that is currently concerned about long-term supply. This raises a key question: what happens when a business with that focus seeks to support a premium valuation that depends heavily on its production levels and realized pricing.
That premium story hinges on execution, so go straight to the 2 key rewards and 1 important warning sign and see how production ambition and pricing risk really line up

Atlas Consolidated Mining and Development (PSE:AT)
Atlas Consolidated Mining and Development is a long-running Philippines copper producer through its Toledo copper mine, giving direct exposure to the Copper Mining and Processing Stocks theme. It generated about ₱21.9b from the Philippines and carries a roughly ₱65.5b market value.
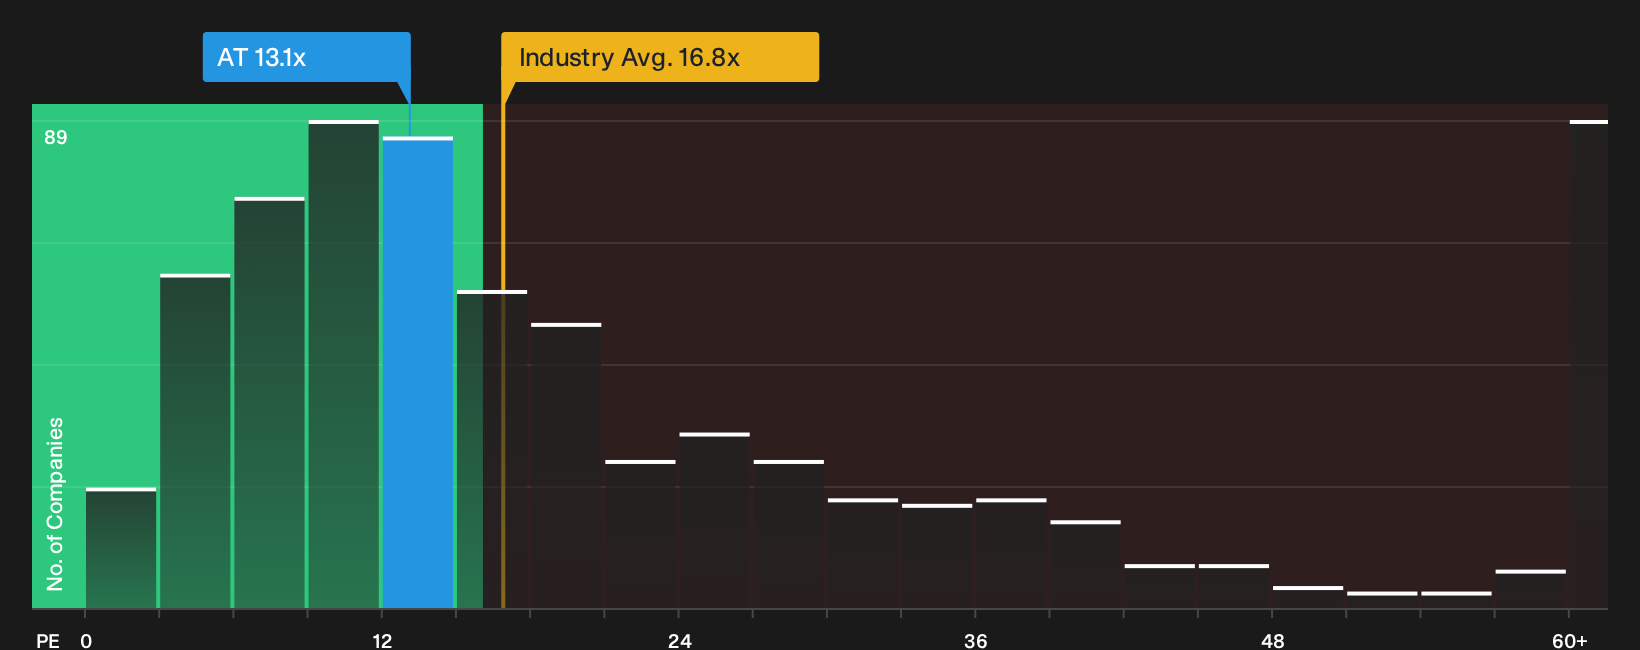
Atlas Consolidated Mining and Development offers pure copper leverage through its Toledo operation in Cebu, with all reported ₱21.9b of sales tied to the Philippines. Profitability has turned positive and the P/E sits below sector averages, so outcomes now depend on what happens if copper recovery margins shift even slightly.
If those margins really start to move, the analyst forecasts for Atlas Consolidated Mining and Development shows how expectations are lining up before the next big shift in Atlas Consolidated Mining and Development’s story
Seeking Fresh Alternatives Beyond Copper?
New themes are breaking out while attention lingers on yesterday’s winners. Momentum shifts fast and under the radar for now. Do your homework before the crowd and consider acting before sentiment changes.
- Target steady income streams by scanning 2 dividend fortresses built to spotlight businesses where cash payouts and balance sheet strength share top billing.
- Hunt for potential future leaders inside 10 high quality undiscovered gems featuring under-followed companies with solid numbers that have not yet been fully caught by broader market attention.
- Track the real picks and shovels of AI using 92 AI infrastructure stocks focusing on firms supplying the hardware, data centers, and backbone that support the sector.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com