
These Canadian Defensive Stocks Are Top Of The Class For October 2026
IMF warnings about large budget deficits and rising government borrowing costs have pushed many investors back toward sturdier Canadian stocks with strong finances. When debt markets look fragile, businesses with solid balance sheets and lower risk profiles can feel like the safer corner of the market. This article highlights three low risk Canadian leaders from our screener that could help form the dependable core of a long term portfolio.
The three stocks below are just a starting sample, and the full Low Risk Leaders screen on Simply Wall St surfaces five more companies with equally compelling stories that are not covered here.
Identify your own foundation holdings by heading straight into the Low Risk Leaders screener to filter, analyze, and focus on the lowest risk ideas for your watchlist.
China Gold International Resources (TSX:CGG)
China Gold International Resources is a Vancouver headquartered miner whose low risk profile in this screener is anchored by its majority owned Chang Shan Hao gold mine in Inner Mongolia, supported by the Jiama copper gold operation. The group generated about $399 million from produced gold and $1.24b from copper concentrate, and carries a market value near $15.82b.
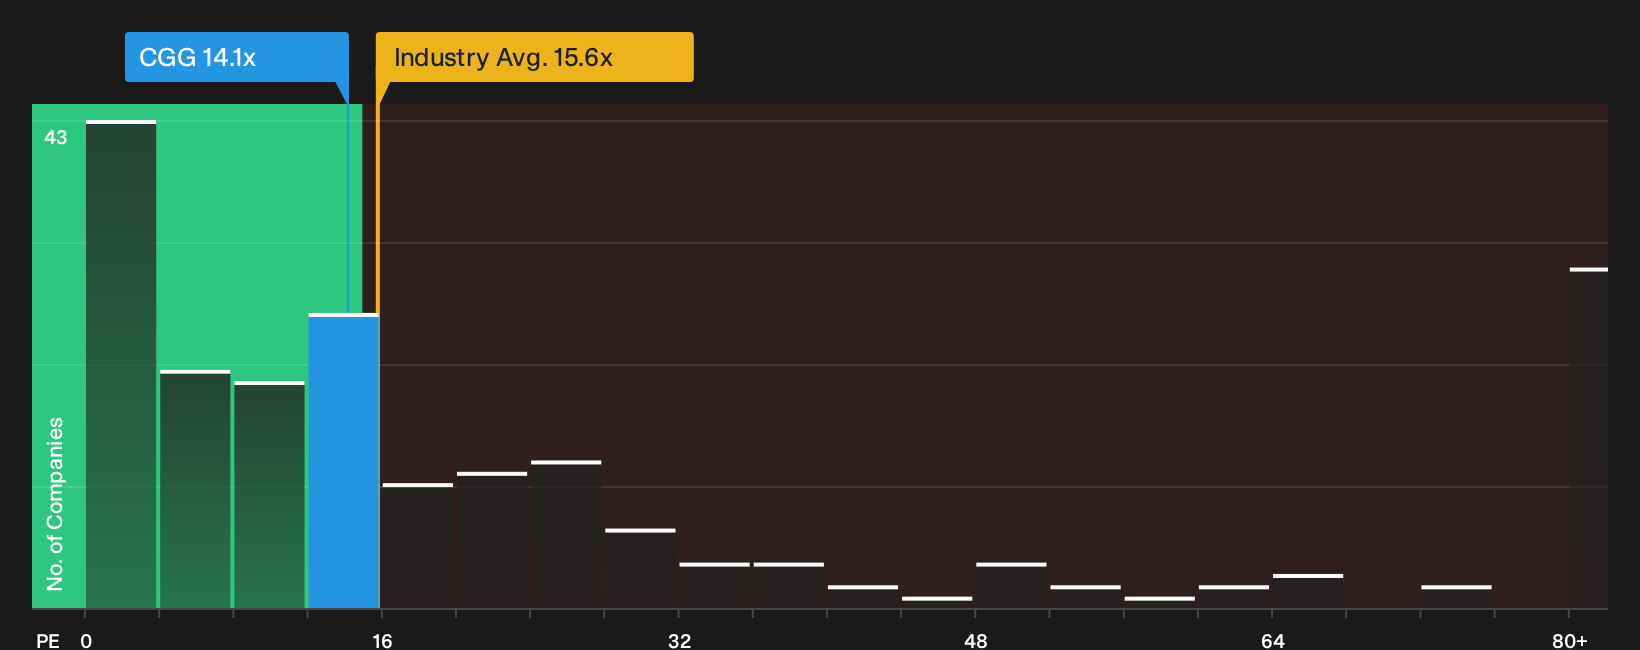
For a foundation focused investor, China Gold International Resources offers sizeable producing assets, a P/E of 14.1x that sits below peers, and net margins around 47.1% that help underpin the Low Risk Leaders theme. One factor that could affect how secure that picture feels is how a single funding dependence develops over time.
That funding reliance deserves a closer look through the 4 key rewards and 1 important warning sign to see what might be quietly influencing China Gold International Resources next chapter.
Sprott (TSX:SII)
Sprott is a Toronto based asset manager focused on precious metals and credit oriented products for risk conscious investors, with about $224 million of revenue from exchange listed products and $95 million from managed equities, supported by $80 million from private strategies, and a market value near $4.27b.
For the Low Risk Leaders theme, Sprott offers something different. The focus is not on a rock bottom valuation but on a mix of capital preservation focused bullion trusts, net margins at 26.4%, and a 25.6% ROE that indicate efficient use of capital for foundation style holdings, depending on how one unseen pressure around future fee revenue unfolds.
That unseen pressure on future fees is exactly what the analysis report for Sprott unpacks for Sprott, so you can see where earnings strength might be masking new fault lines.

Fortuna Mining (TSX:FVI)
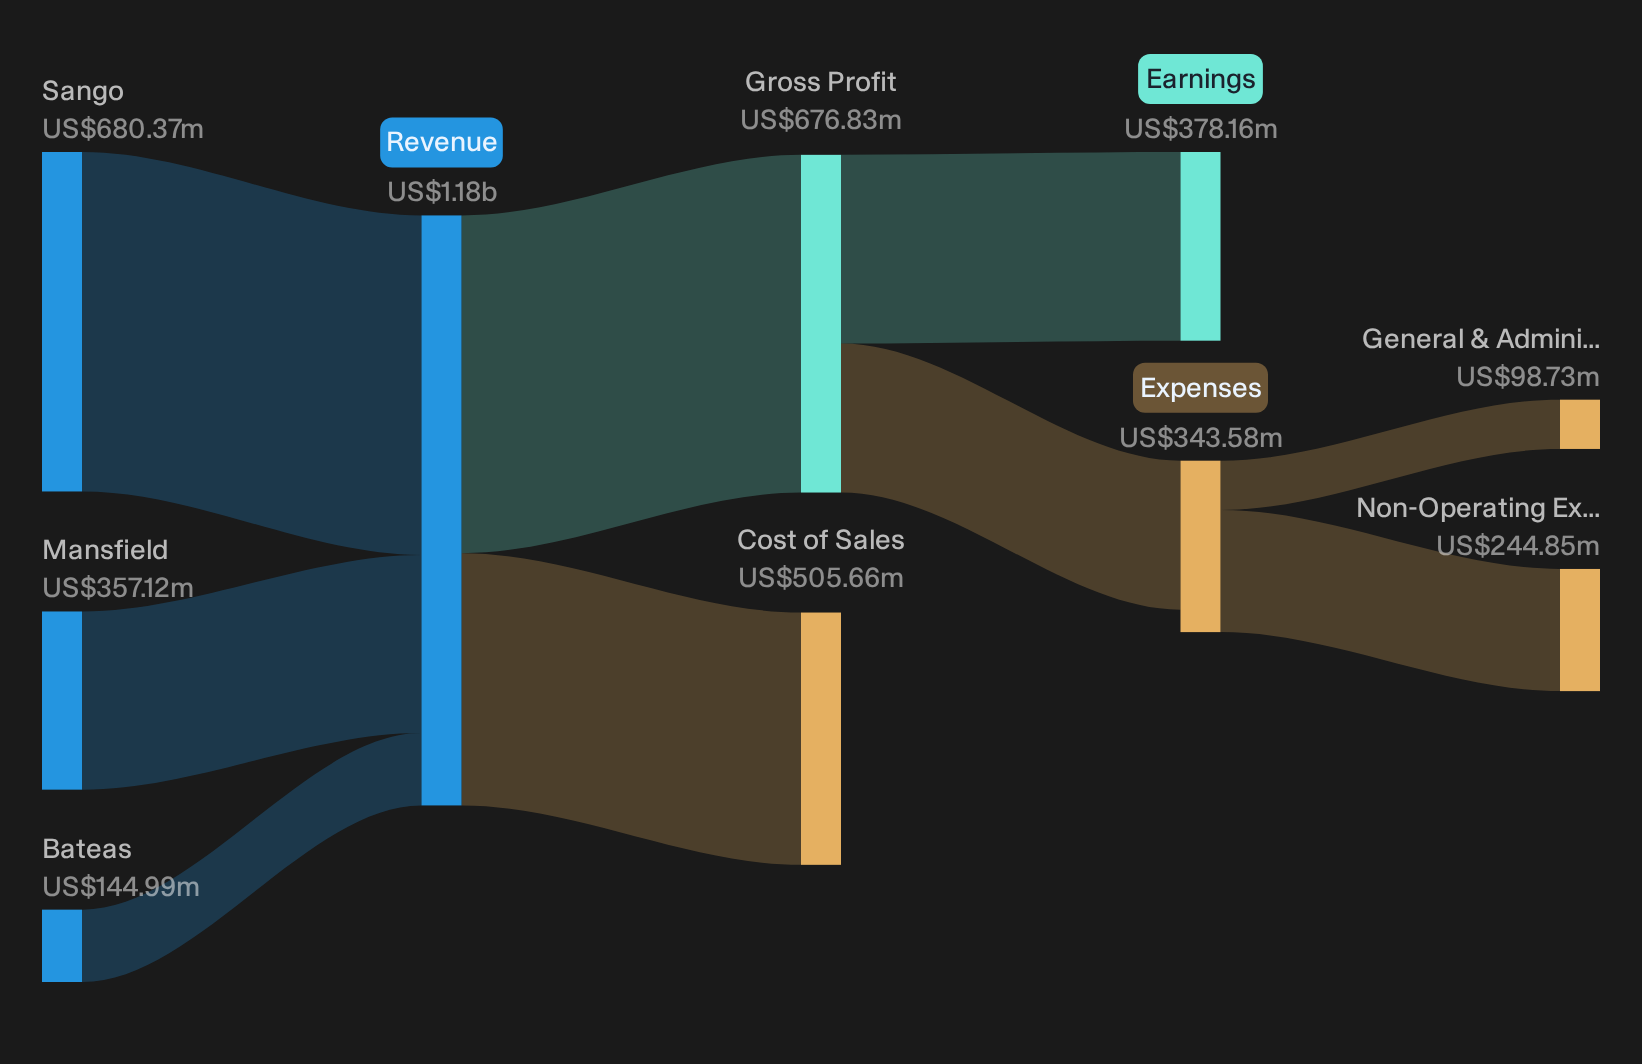
Fortuna Mining ties into the Low Risk Leaders theme through its Lindero and Séguéla producing gold mines, which underpin bullion and concentrate sales. The business also draws material income from the Sango segment at about $680 million, Mansfield at $357 million, and Bateas at $145 million, with a market value near CA$4.6b.
For investors building a sturdier base around precious metals, Fortuna Mining offers producing gold assets backed by an experienced management team and a growing West Africa footprint that is increasingly important to the Low Risk Leaders story.
"Expansion at Seguela and the development of Diamba Sud position Fortuna to restore and surpass its previous production levels, with higher-margin and longer-life ounces, aligning with anticipated increases in global demand for gold and other strategic metals, which is expected to support future revenue and cash flow growth."
What really matters now is how one cost pressure shifts over the next few years, because that could reshape the margin picture.
That margin swing is exactly what the full narrative for Fortuna Mining unpacks in detail, revealing how Fortuna Mining’s growth projects and cost profile could be quietly reshaping the risk reward balance.
Seeking Fresh Alternatives Before They Fly
Fresh ideas tend to move first. Breakout trends can gain momentum long before headlines catch up, and you may not want to be caught chasing. Consider scanning for new leaders that are still under the radar and deciding how they fit your own process.
- Look for early movers in smaller companies with stronger balance sheets and focused execution by running the 18 elite penny stocks with strong financials before momentum traders push valuations to different levels.
- Explore rising demand for secure digital finance by checking the curated 19 cryptocurrency and blockchain stocks that highlight businesses building real revenue behind the headlines.
- Focus on durable income streams by filtering for the 2 dividend fortresses that aim to combine higher yields with sturdier financial footing, so your watchlist is more targeted.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com