
Does AI Compliance Launch Change The Bull Case For Paychex Stock (PAYX)?
- Paychex, through its SixFifty platform, has released what it calls the HCM industry's first agentic HR compliance specialist, using AI to answer employment law questions across US jurisdictions and execute multi step compliance tasks such as drafting handbooks, distributing labor law posters, and tracking employee acknowledgments.
- The tool is offered both as a standalone SixFifty product and integrated into Paychex Flex and Paycor via the WISE AI engine. This points to a broader push to shift compliance work from manual processes to automated, workflow driven execution across the combined client base.
- We will look at how Paychex's investment narrative around AI scale and higher value services is affected by SixFifty's agentic compliance launch.
Paychex Investment Narrative Recap
To own Paychex, you need to believe its steady HCM model, recurring fees and expansion into higher value HR services can keep compounding earnings even as headline growth expectations stay moderate. The SixFifty agentic HR compliance launch fits that thesis by pushing more work into software and potentially reinforcing client stickiness rather than altering the near term story.
The key near term swing factor still sits with execution on Paycor integration, margin progress and how well Management Solutions, PEO and Insurance balance each other if growth in one line slows. The biggest operational risk remains integration missteps and softer client fund interest income, not this specific product launch, which looks incrementally helpful but not transformational.
In that context, the most relevant prior development is management’s expectation for fiscal 2027 revenue growth of 5% to 6% and adjusted EPS growth of 7% to 9%. That outlook leans heavily on pricing discipline, operating efficiency and deeper product penetration across both legacy and Paycor clients rather than on any single AI feature.
The SixFifty agentic HR specialist fits into that plan as another workload automation tool alongside the broader WISE AI engine, which already supports over 2,000 agents and features. For you as an investor, the operational question is whether Paychex can turn these tools into sustained cost savings and cross sell momentum fast enough to offset integration risk, higher debt and any drag from Management Solutions or lower interest on client funds.
Paychex's current analyst storyline points to revenues of US$7.7b and earnings of US$2.4b by 2029, based on 5.2% yearly revenue growth and an earnings increase of about US$600m from the US$1.8b reported today.
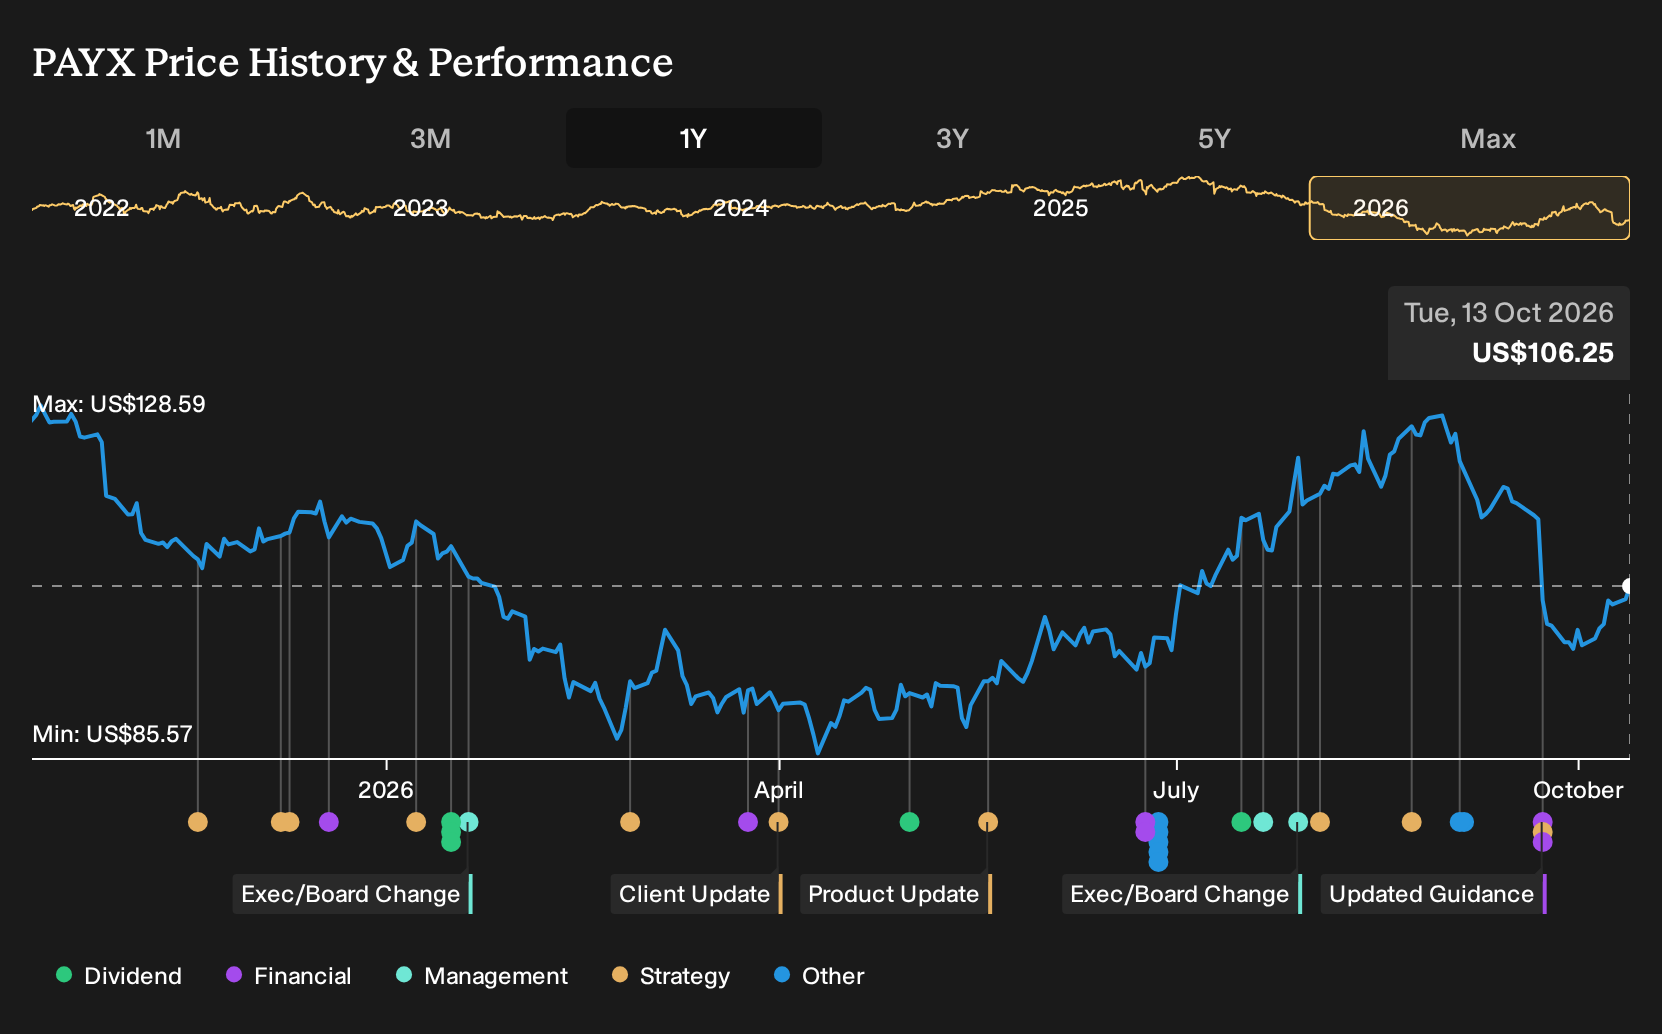
Uncover why Paychex's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Paychex focuses on a slower payoff from AI. The most bearish analysts saw earnings at about US$2.3b on US$7.6b of revenue by 2029, with a lower 17.3x P/E, before this SixFifty launch. That is a much more cautious story. Opinions clearly differ, so explore both narratives and decide which feels more realistic to you.
Explore 3 other Paychex fair value estimates, including one that suggests it could be worth just $113.93.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Paychex research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Paychex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paychex's overall financial health at a glance.
Looking For More Investment Ideas Beyond Paychex?
Once you have formed a view on Paychex, it helps to compare it with other opportunities that match your style, risk tolerance and income needs. The Simply Wall St screener can surface a range of different profiles so you are not relying on a single story or sector.
- If you care most about strong balance sheets and durable fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching its finances.
- If you are hunting for value, scan for companies on our 32 high quality undervalued stocks that pair quality metrics with a price that still looks reasonable.
- If reliable income is a priority, focus on potential 8 dividend fortresses that aim to combine higher yields with more resilient business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com