
Third Quarter Results Could Be A Key Test For Betsson Stock (OM:BETS B)
- Betsson entered its silent period ahead of third quarter results expected on 22 October 2026, while licensed betting operators in Brazil, including peers in online gaming, saw their local sites go offline after a new online betting ban and pending Supreme Court review.
- The combination of Brazil's regulatory halt and the upcoming earnings report focuses attention on how reliant Betsson's future operating mix may be on higher tax, tightly regulated jurisdictions versus emerging markets that carry greater legal and licensing uncertainty.
- This article now explores how Betsson's investment narrative is shaped by Brazil's online betting ban during the quiet period before third quarter earnings.
Scan how other regulated gambling players are positioned against the same pressures by reviewing our hand picked 225 resilient stocks with low risk scores, which keep balance sheets and licensing risk under tighter control.
Betsson Investment Narrative Recap
To own Betsson, you need to be comfortable with a betting group that leans into regulated markets, accepts higher gaming taxes and still aims to grow through product and geographic expansion. The short term focus sits on the 22 October 2026 third quarter report, where investors will look for how the mix between mature regions and newer territories is evolving.
Brazil's online betting ban creates a live test of Betsson's exposure to regulatory shocks in emerging markets. The sector wide issue may not change the core thesis around technology, brand reach and M&A, but it sharpens the biggest risk right now, which is margin pressure from taxes, regulation and rising operating costs.
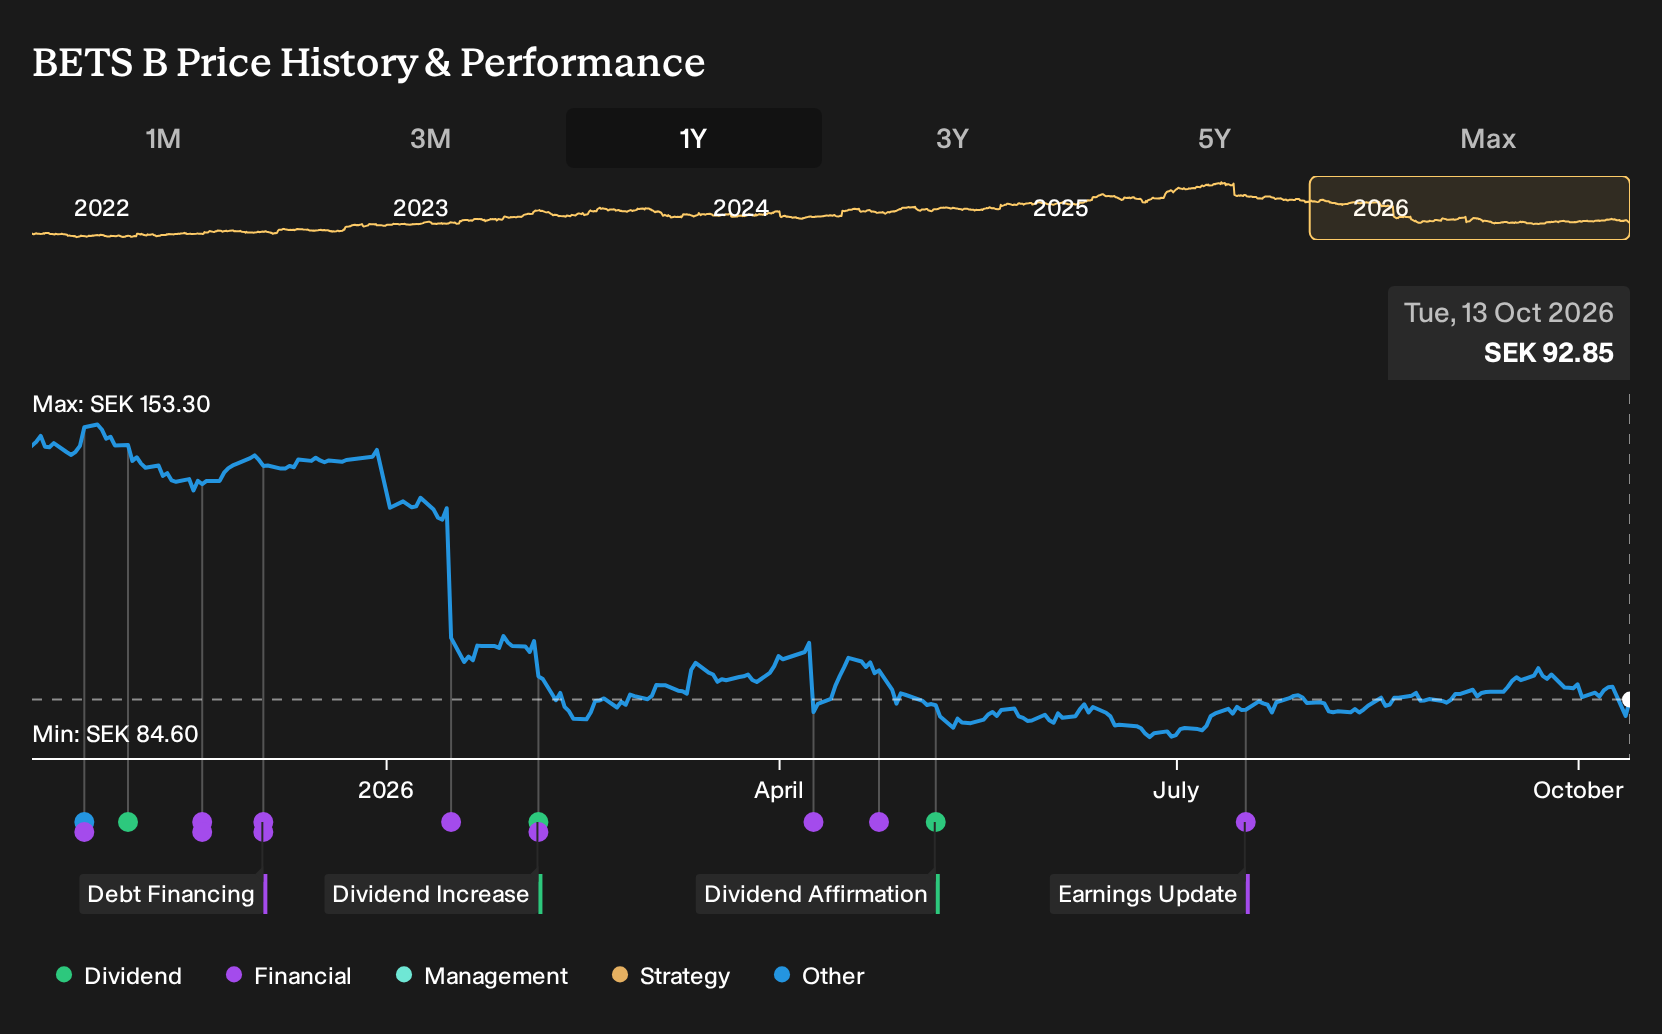
With Betsson in its silent period, the most relevant milestone is that upcoming third quarter earnings release. It arrives with the share price up 2.41% over the week of 5 to 9 October 2026, during a mixed stretch for European gambling peers, and after a weaker 1 year share return versus both the Swedish market and local hospitality sector.
That update will sit against a backdrop of 5.5% forecast annual revenue growth, an 11.2% net margin that is below last year, and earnings expected to grow 6.6% a year. For you, the question is whether the combination of regulated market exposure, current P/E of 8.4x and regulatory headlines such as Brazil still fits your tolerance for earnings volatility.
What The Current Betsson Forecasts Assume
Betsson's current analyst playbook leans on measured growth rather than a big upswing story, and it is worth spelling out what that actually means in numbers. Forecasts point to revenue rising by 3.8% a year, while consensus expects earnings to move from €153.8 million today to €141.6 million by 2029, which is a drop of about €12.2 million. Those same estimates point to revenues of €1.3 billion and earnings of €141.6 million by 2029. The profile here is modest top line growth combined with lower profit margins rather than a compound earnings build.
Betsson's narrative projects €1.3 billion revenue and €141.6 million earnings by 2029. This rests on 3.8% yearly revenue growth and an earnings decrease of about €12.2 million from €153.8 million today.
Uncover why Betsson's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate view focuses squarely on regulatory strain. The most cautious Betsson analysts were already pencilling in revenue of about €1.4b and earnings of roughly €141.1 million by 2029 before the Brazil ban hit headlines. That group is effectively warning you that fresh legal shocks could push earnings below their already muted path.
Explore 7 other Betsson fair value estimates, including one that suggests it could be worth just SEK90.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Betsson research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Betsson. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Betsson's overall financial health at a glance.
Looking for more Betsson-sized investment ideas?
If Brazil's regulatory shock and Betsson's forecast path have sharpened your thinking, it can help to line this story up against other opportunities that better fit your own risk, income and balance sheet preferences. The Simply Wall St Screener gives you a way to filter for that fit directly, rather than relying on headlines.
- If you want potential mispricing with quality behind it, start by scanning 185 high quality undervalued stocks that combine resilient finances with more conservative valuations.
- If capital protection matters most, focus on companies with stronger cushions by filtering for our list of solid balance sheet and fundamentals (204 results), where financial resilience is front and centre.
- If you prefer ideas that the market has not fully crowded into, widen your search through a curated 621 high quality undiscovered gems backed by solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com