
Finnair Shares In Focus After 2026 Revenue Guidance Lift
- Finnair Oyj has raised its full year 2026 revenue guidance to a range of €3.5b to €3.6b, up from the earlier estimate of €3.4b to €3.5b, signalling a more confident outlook shared on 13 October 2026.
- The higher revenue range hints that Finnair sees stronger demand or better capacity use than it previously built into its full year plan, which directly links to how effectively the airline can manage costs, routes and ancillary income streams.
- This development invites a closer look at how Finnair's upgraded 2026 revenue guidance could reshape the existing investment narrative around capacity, costs and demand.
See how Finnair Oyj's upgraded guidance compares with other carriers by reviewing our hand picked list of list of solid balance sheet and fundamentals (204 results)
Finnair Oyj Investment Narrative Recap
To be comfortable owning Finnair Oyj, you need to believe the airline can keep filling a growing seat base, hold onto ancillary income and keep unit costs under control despite fuel, fees and regulation. The raised 2026 revenue guidance points to a firmer top line. However, the main near term swing factor remains how efficiently that extra capacity is flown.
The biggest operational risk still sits in costs and labor. Rising environmental and sustainable aviation fuel expenses, higher traffic and landing charges, plus unresolved industrial disputes can quickly eat into already modest net margins. The new guidance does not remove that execution risk. It instead suggests management currently sees demand support for the plan.
Among recent information, capacity plans look most relevant to the upgraded revenue band. Finnair Oyj aims to increase Available Seat Kilometers by about 10% in 2025, which is a clear operational lever behind higher sales guidance into 2026. If those extra seats are matched with stable pricing and solid ancillary sales, the guidance range looks operationally consistent.
The same expansion plan also sharpens the risk profile. More flying hours mean higher exposure to fuel prices, maintenance costs and potential industrial action, which has already carried a cost in prior disputes. For an investor focused on catalysts, the key checks are progress on fleet renewal, any movement on Russian overflights that could improve route efficiency, and signs that labor relations are stabilising as capacity scales.
What The Finnair Oyj Forecasts Assume
Finnair Oyj's upgraded revenue guidance for 2026 sits alongside a longer term analyst story that extends out to 2029. Rather than just focusing on one year, the current forecasts sketch out how consistently the airline might grow its top line and widen margins over several years, if capacity, pricing and costs line up as planned.
Analysts are building their models on the idea that Finnair Oyj can grow revenue by 4.2% a year over roughly the next three years. On top of that, they assume profit margins move from 1.9% today to 2.7% by around 2029. This implies the business would keep more of every euro of sales as profit if those assumptions play out.
Earnings today are pegged at €60.0 million, with consensus forecasts pointing to €97.5 million by 2029. That implies an earnings increase of about €37.5 million from current levels, a step up that relies on both revenue expansion and better profitability rather than volume alone.
Forecasts also rest on a steady share count over the next few years, so all of the earnings growth in the analyst models flows through to earnings per share rather than being diluted. That matters for anyone tracking metrics like P/E, because it means the projected €0.48 in earnings per share by 2029 is driven by operational improvements, not financial engineering.
On valuation, the analyst framework assumes that by 2029 Finnair Oyj could be generating around €3.6b of revenue and €97.5 million of earnings. Those numbers are paired with a 9.9x P/E multiple in the models, which is lower than both the current 17.3x on the stock and the cited 17.3x industry level for GB airlines.
The analyst price targets cluster around €3.43, with the most optimistic at €3.8 and the most cautious at €2.9. With the shares trading at €5.06 when the report was compiled, that target range sits below the market price. The implied view is that expectations in the current quote look richer than the earnings and margin profile embedded in the consensus forecasts.
Finnair Oyj's narrative projects €3.6b revenue and €97.5 million earnings by 2029. This requires 4.2% yearly revenue growth and an earnings increase of about €37.5 million from €60.0 million today.
Uncover why Finnair Oyj's fair value indicates a 22% potential downside to its current price, which leaves little room for error.
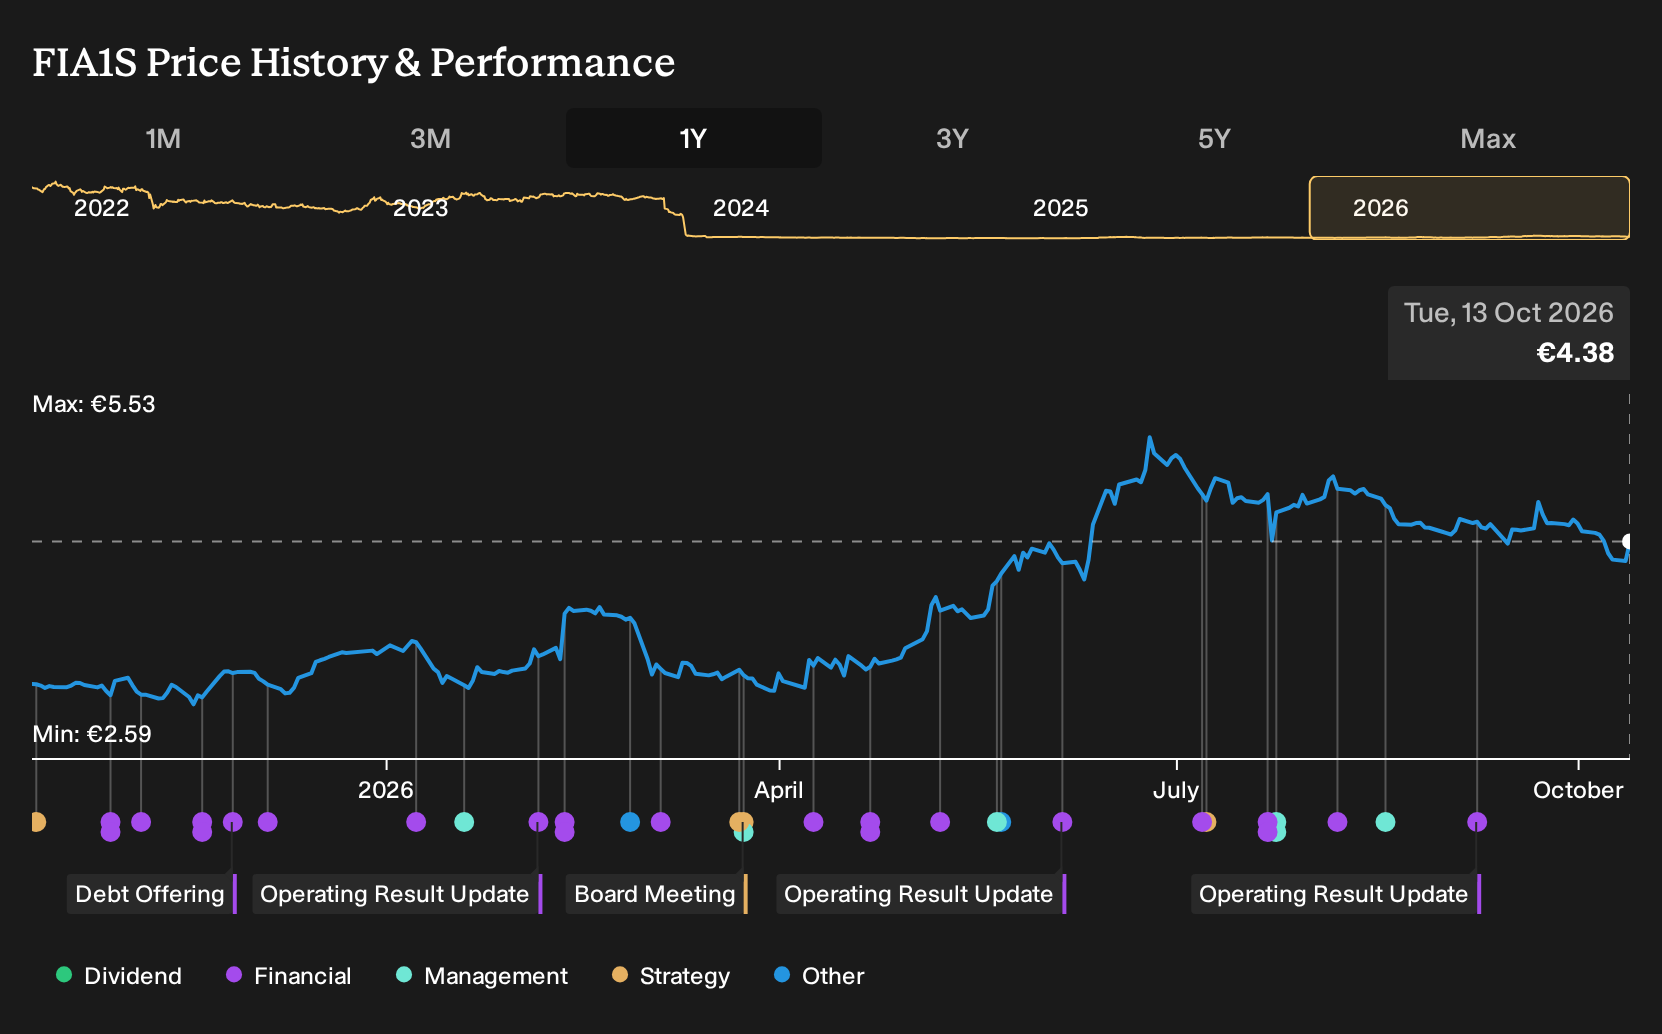
Exploring Other Perspectives
For a different lens on Finnair Oyj, focus on the bullish view that hinges on loyalty and ancillary income rather than just capacity and costs. Before this guidance upgrade, the most optimistic analysts were already pencilling in about €3.6b of revenue and €95.9 million of earnings for 2029. Those projections came with a €4.0 price target that assumed strong contribution from the Finnair Plus program and higher spend per passenger. The new 2026 revenue band could nudge that story in either direction, so it makes sense for you to compare these higher expectations with the more cautious forecasts and decide which version of the future feels more realistic.
Explore 2 other Finnair Oyj fair value estimates, including one that suggests as much as 80% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Finnair Oyj research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Finnair Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Finnair Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Finnair Oyj?
Once you have a view on Finnair Oyj, it can help to compare that thesis with opportunities in other sectors and capital structures so your portfolio is not anchored to a single story.
- If you want potential value combined with resilience, start your search with a 185 high quality undervalued stocks that already pair quality fundamentals with prices that look reasonable on key ratios.
- For investors who care most about durability and financial strength, focus on companies with robust balance sheets by scanning our curated list of solid balance sheet and fundamentals (204 results) that can help you sleep better through market swings.
- Those hunting for less volatile candidates can filter for businesses with steadier risk profiles by reviewing a focused 225 resilient stocks with low risk scores that may complement higher risk positions like airlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com