
Mixed Earnings Could Be A Key Test For Atrium Ljungberg Stock
- Atrium Ljungberg reported third quarter 2026 sales of SEK 761 million and revenue of SEK 915 million, with net income of SEK 353 million and basic earnings per share from continuing operations of SEK 0.56.
- The nine month figures show higher sales and revenue than a year earlier, while net income and basic earnings per share from continuing operations are lower, which points to pressure on profitability even as Atrium Ljungberg continues to grow its top line.
- The next step is to assess how Atrium Ljungberg's investment narrative compares with these mixed nine month profitability results.
Scan how Atrium Ljungberg's mixed earnings trend compares with peers by reviewing our curated set of 186 high quality undervalued stocks that combine balance sheet strength with resilient cash generation.
Atrium Ljungberg Investment Narrative Recap
To own Atrium Ljungberg, you need to believe its metro linked, mixed use districts can keep attracting tenants even as financing costs bite and some office demand softens. The latest quarter shows higher sales, revenue and quarterly earnings per share, so the core property platform still produces income despite pressure on margins over nine months.
The key near term swing factor is how quickly recently completed and ongoing projects fill with paying tenants, which speaks directly to cash generation and interest coverage. The biggest operational risk remains that higher vacancies and rising interest expense outpace rental gains. On the latest figures, that risk has not materially changed.
The most relevant fresh information is the nine month update to 30 September 2026. Sales reached SEK 2,290 million and revenue SEK 2,720 million, both above the prior year, while net income of SEK 617 million and basic EPS of SEK 0.98 were lower. That mix reinforces that top line activity and underlying profitability are pulling in different directions.
For you as a shareholder, that matters because major development projects in Sickla and other hubs only create value if future rent covers both construction spending and higher interest costs. With profit from property management previously under pressure from property sales and financing expense, this earnings report keeps the focus firmly on execution, leasing progress and balance sheet discipline rather than altering the core catalysts.
Atrium Ljungberg's narrative projects SEK 3.1 billion revenue and SEK 1.5 billion earnings by 2029. This assumes revenue decreases by 5.9% per year and requires an earnings increase of about SEK 928 million from SEK 572 million today.
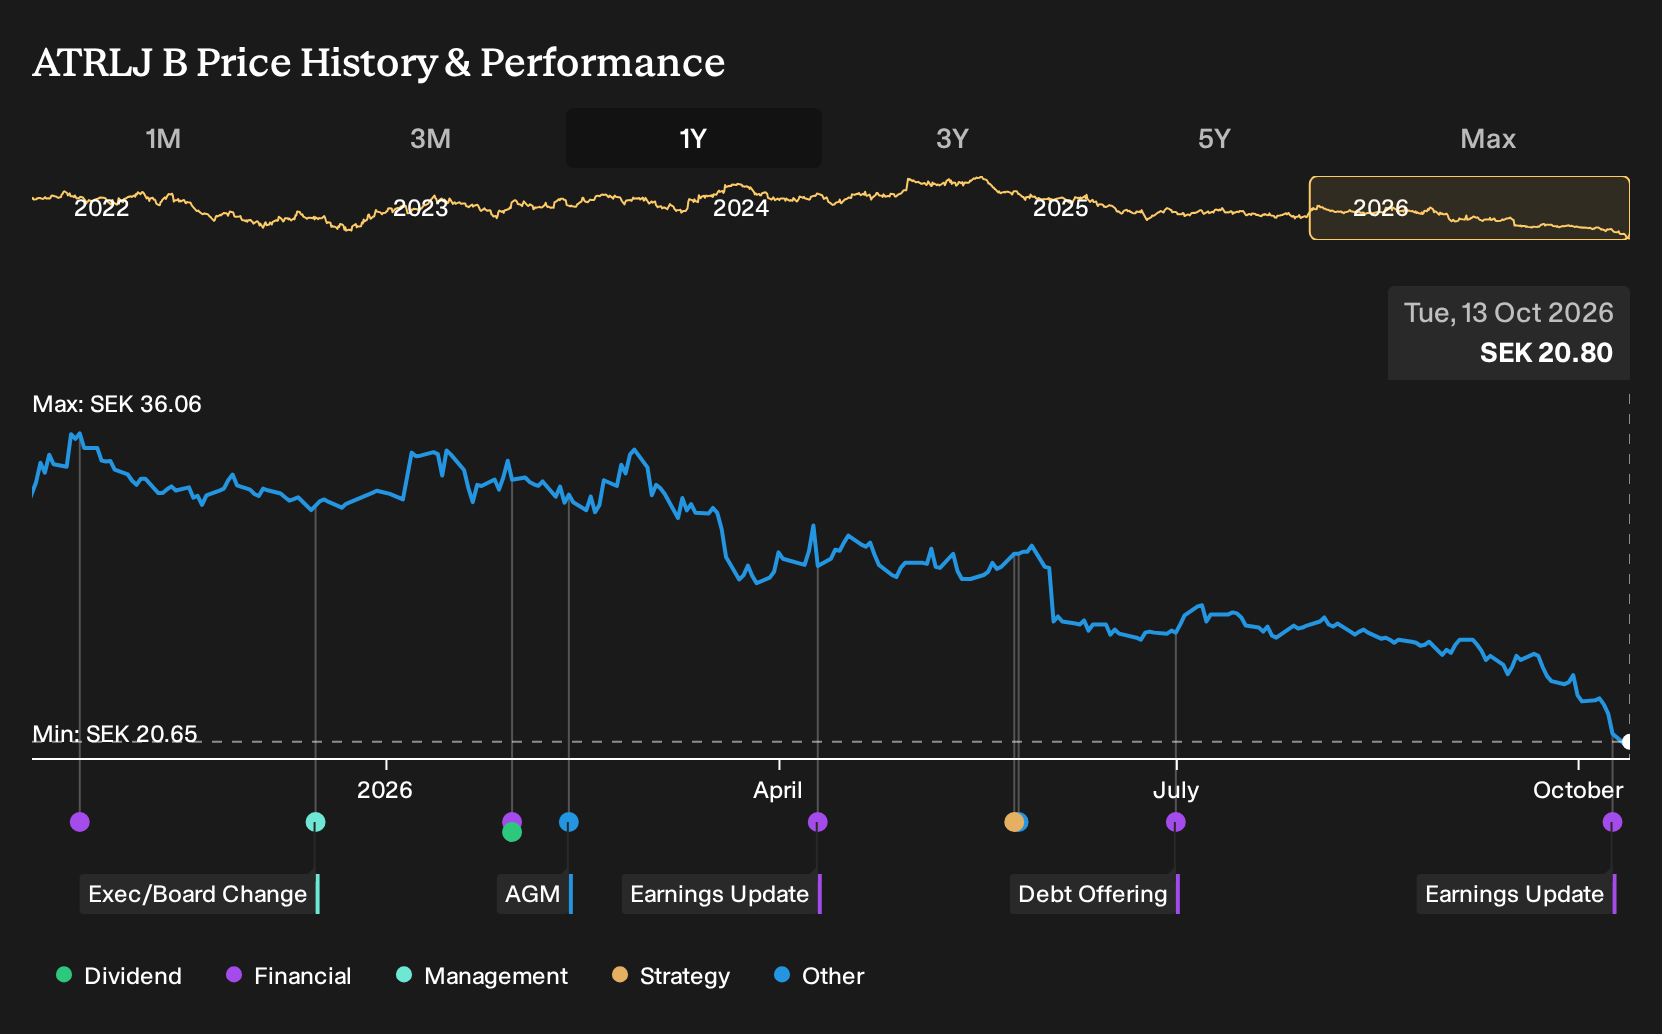
Uncover why Atrium Ljungberg's fair value indicates a 41% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard on the Ericsson contract and wider Stockholm pipeline, arguing Atrium Ljungberg could reach around SEK 3.3 billion of revenue and SEK 2.2 billion of earnings by 2029. You now have fresh earnings that those forecasts do not yet reflect, so views may shift as you compare both sets of numbers.
Explore another Atrium Ljungberg fair value estimate, including one that suggests potential upside of as much as 41% from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Atrium Ljungberg research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Atrium Ljungberg. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atrium Ljungberg's overall financial health at a glance.
Looking for more investment ideas beyond Atrium Ljungberg?
Once you have a handle on Atrium Ljungberg, it can help to set it in context by scanning other businesses with different risk and income profiles using the Simply Wall St Screener.
- If you want income to play a bigger role in your portfolio, you can start with a curated group of 223 dividend fortresses that focus on robust cash payouts.
- If capital preservation matters most to you, you can compare Atrium Ljungberg with a 224 resilient stocks with low risk scores that aims for resilient returns with fewer shocks.
- If you prefer to back financially sound operators, you can broaden your watchlist with a list of solid balance sheet and fundamentals (202 results) that can help you filter for sturdier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com