
Asian Undervalued Small Caps With Insider Action To Watch In October 2026
As Asian markets navigate a complex landscape marked by geopolitical tensions and fluctuating energy prices, small-cap stocks have garnered attention for their potential to offer unique opportunities amid broader market volatility. In this environment, identifying companies with strong insider action can provide valuable insights into potential undervaluation, making them noteworthy for investors seeking growth in the dynamic Asian market.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 3.9x | 0.8x | 23.03% | ★★★★★★ |
| Q Technology (Group) | 3.4x | 0.2x | 45.47% | ★★★★★☆ |
| Charter Hall Long WALE REIT | 8.6x | 12.1x | 39.65% | ★★★★★☆ |
| Australian Finance Group | 7.0x | 0.2x | 29.56% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.9x | 0.9x | 39.49% | ★★★★★☆ |
| Clover | 16.2x | 1.7x | 47.18% | ★★★☆☆☆ |
| Centurion | 16.6x | 3.2x | 18.22% | ★★★☆☆☆ |
| Citicore Energy REIT | 13.2x | 10.0x | 27.12% | ★★★☆☆☆ |
| FINEOS Corporation Holdings | 98.2x | 2.8x | 48.64% | ★★★☆☆☆ |
| Cettire | NA | 0.2x | 3.33% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Lifestyle Communities (ASX:LIC)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Lifestyle Communities focuses on the development and management of residential communities tailored for homeowners over 50, with a market capitalization of A$1.22 billion.
Operations: The company generates revenue primarily from property development and management, with a recent recorded revenue of A$204.82 million. Over time, it has experienced fluctuations in net income margin, reaching -1.47% in late 2025 before recovering to 22.91% by mid-2026. The gross profit margin showed a similar trend, dropping to -33.36% at the end of 2025 and later improving to 14.87%. Operating expenses have steadily increased over the years, impacting overall profitability trends significantly during certain periods.
PE: 10.0x
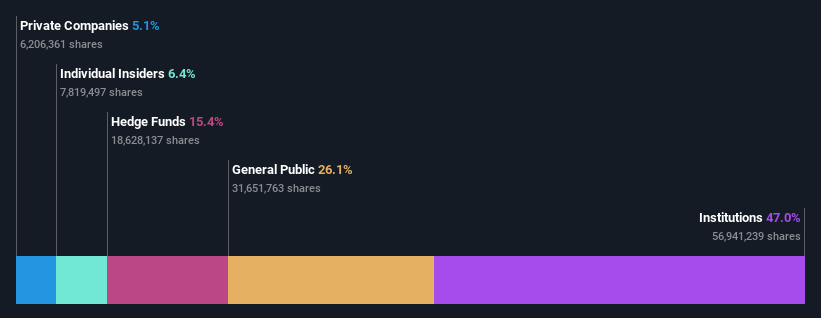
Lifestyle Communities, a small player in the Asian market, has shown significant insider confidence with Kevin Tucker acquiring 4.2 million shares valued at A$20.41 million over the past year. This reflects a 35% increase in their holdings. The company reported sales of A$52.36 million for the year ending June 2026, turning around from a net loss to an income of A$46.92 million, indicating potential growth despite funding risks from external borrowing sources only and interest payments not being well-covered by earnings yet earnings are forecasted to grow by nearly 16% annually offering prospects for future improvement in financial health and shareholder value.
- Click to explore a detailed breakdown of our findings in Lifestyle Communities' valuation report.
Gain insights into Lifestyle Communities' past trends and performance with our Past report.
Universal Robina (PSE:URC)
Simply Wall St Value Rating: ★★★★☆☆
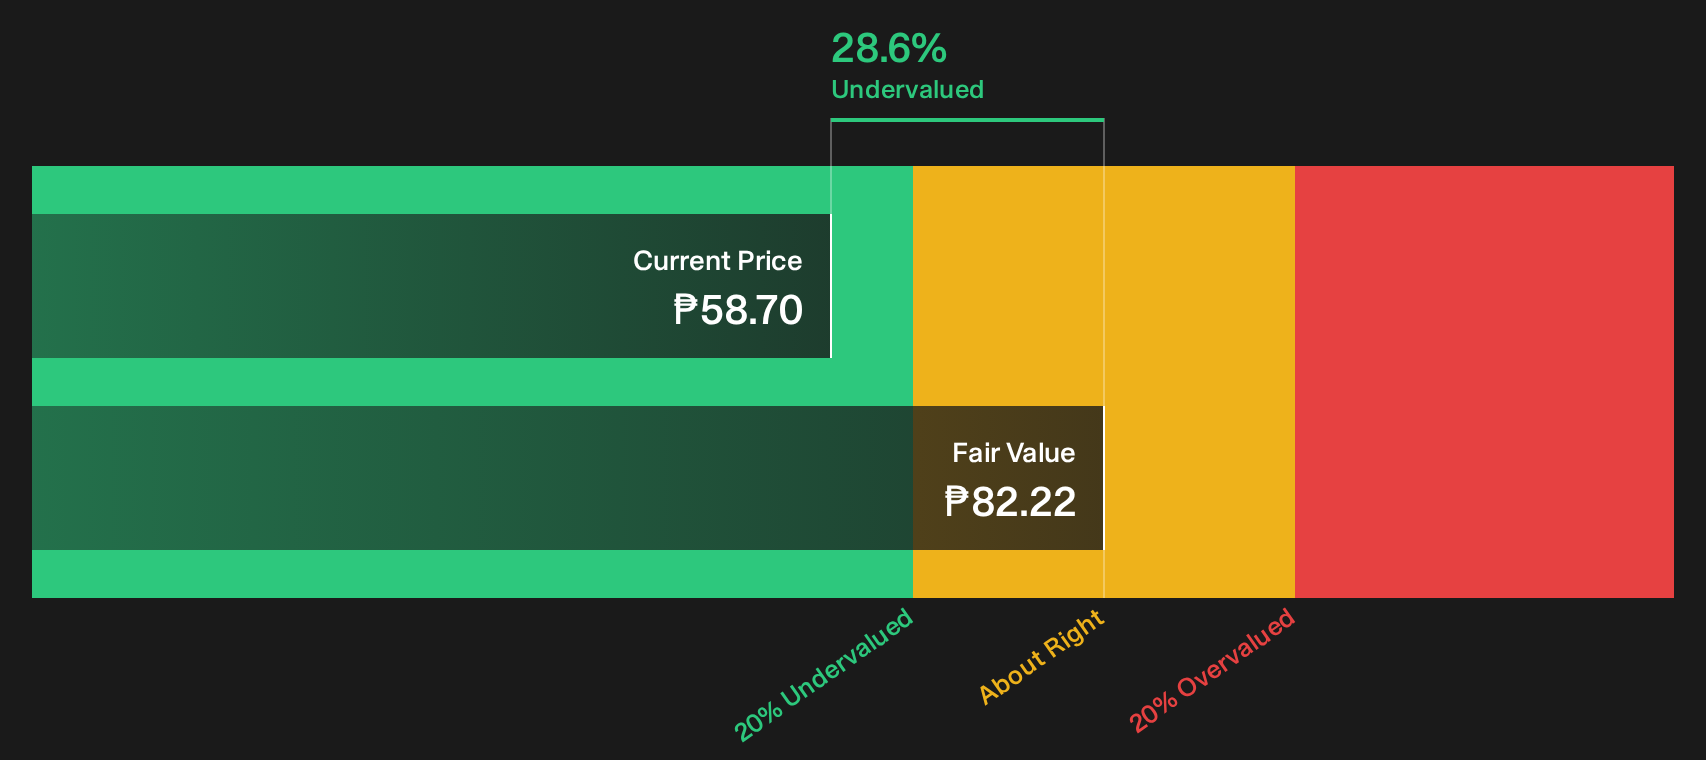
Overview: Universal Robina operates as a diversified food and beverage company, focusing on branded consumer foods, commodities, and animal nutrition and health products with a market capitalization of ₱286.23 billion.
Operations: Branded Consumer Foods is the largest revenue segment, contributing significantly to total revenue. The company has experienced fluctuations in its gross profit margin, with recent figures around 26.74%. Operating expenses are primarily driven by sales and marketing costs.
PE: 11.6x
Universal Robina, a notable player in Asia's small-cap landscape, recently showcased insider confidence when James Gokongwei purchased 1.6 million shares valued at PHP 100.10 million between July and August 2026. This move suggests potential optimism about the company's future prospects. Despite relying solely on external borrowing for funding, URC reported strong earnings growth with net income rising to PHP 2,939 million in Q2 2026 from PHP 2,216 million a year earlier. Additionally, they declared a special cash dividend of PHP 2.30 per share payable by September end, further indicating financial health and shareholder value focus amidst forecasted annual earnings growth of over nine percent.
- Click here to discover the nuances of Universal Robina with our detailed analytical valuation report.
Evaluate Universal Robina's historical performance by accessing our past performance report.
UltraGreen.ai (SGX:ULG)
Simply Wall St Value Rating: ★★★★☆☆
Overview: UltraGreen.ai focuses on developing and providing artificial intelligence solutions for sustainable energy management, with a market cap of $1.75 billion.
Operations: UltraGreen.ai generates revenue primarily from its DxG segments in the Americas and the Rest of World, with gross profit margins showing an upward trend, reaching 85.88% by mid-2026. The company's cost structure includes COGS and significant operating expenses, with general and administrative costs being a notable component.
PE: 8.4x
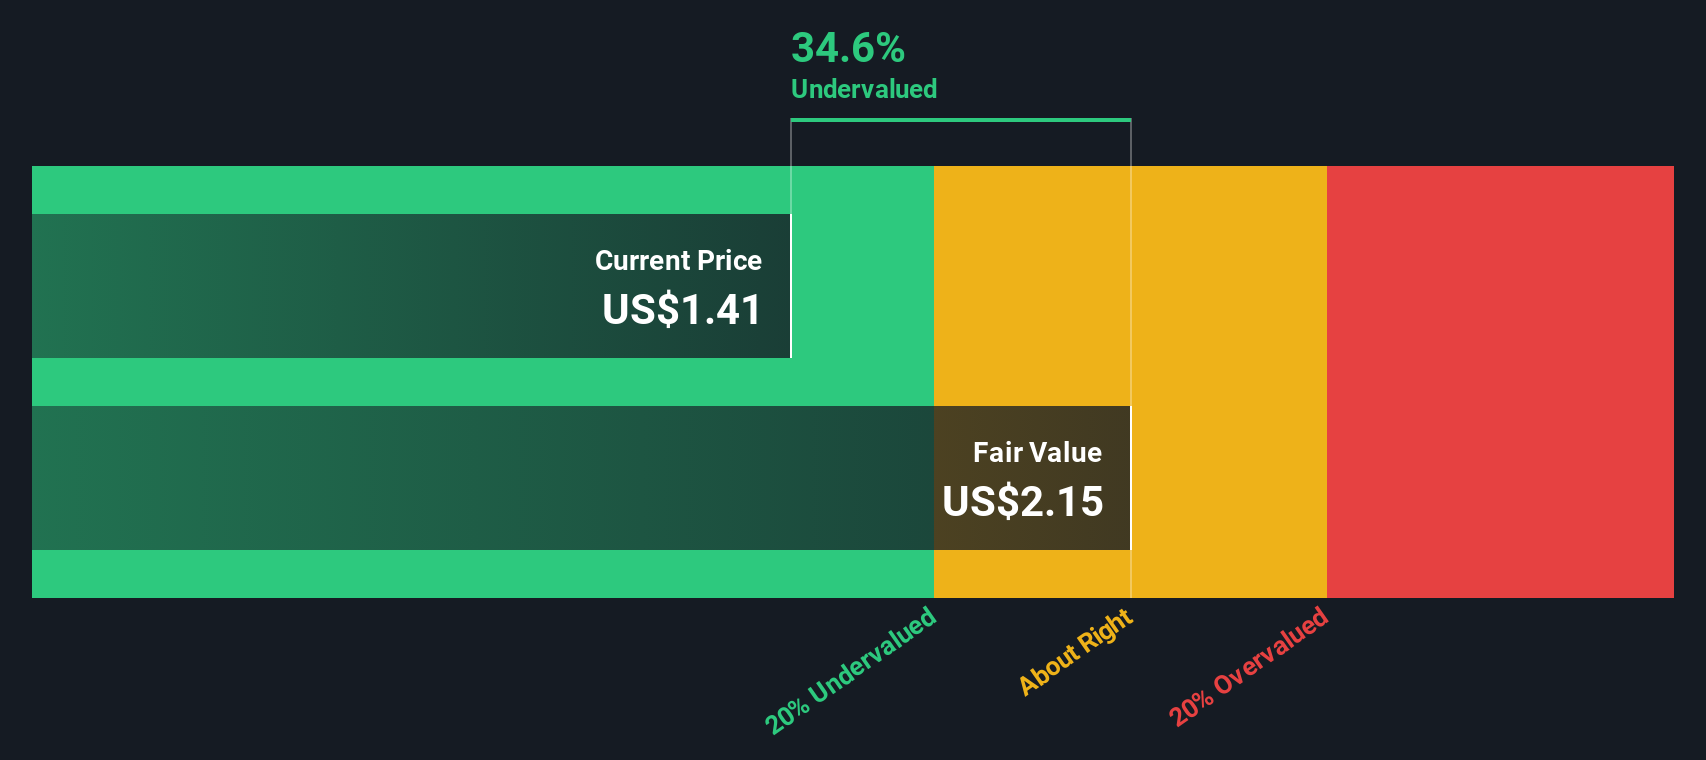
UltraGreen.ai, a tech-focused company in Asia, has seen recent insider confidence with share purchases over the past quarter. Despite a volatile share price in recent months, the company's financials show promise; sales for the first half of 2026 reached US$87.16 million, up from US$66.65 million last year, and net income increased to US$39.25 million from US$25.67 million. With projected annual revenue between US$175-185 million and earnings growth forecasted at 11.96% annually, UltraGreen.ai offers potential for investors seeking opportunities in smaller companies within Asia's dynamic market landscape.
- Get an in-depth perspective on UltraGreen.ai's performance by reading our valuation report here.
Assess UltraGreen.ai's past performance with our detailed historical performance reports.
Key Takeaways
- Click this link to deep-dive into the 58 companies within our Undervalued Asian Small Caps With Insider Buying screener.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com