
SAN-ALTD (TSE:2659) Could Be 72% Below Fair Value On Half Year Earnings
SAN-ALTD (TSE:2659) moved into focus after SAN-A CO., LTD. released half year earnings on October 6, 2026, reporting higher sales, net income, and basic earnings per share compared with the previous period.
The latest half year figures land as SAN-ALTD’s share price has eased in the short term, with a 30-day share price return down 7.35% and a 90-day share price return down 3.74%. This comes even though the year-to-date share price return is up 5.42% and the 1-year total shareholder return is 19.30%, hinting that recent weakness comes against a stronger multi-year backdrop that includes a 69.85% total shareholder return over five years.
Scan how SAN-ALTD’s latest earnings move compares with other Japan stocks by checking a curated list of 13 high quality undervalued stocks with resilient balance sheets and cash flows.
SAN-ALTD now trades below both analyst targets and an estimated intrinsic value, even after reporting stronger half year figures. Is that discount a safety margin, or a warning that the market’s caution is justified?
Price-to-Earnings of 16.4x: Is it justified?
SAN-ALTD screens as expensive on a P/E basis, with the stock at ¥3,090 and trading above several reference points that suggest a lower multiple.
The P/E ratio compares the current share price to earnings per share and is a common shorthand for how much investors are paying for current profits. For a supermarket operator such as SAN-ALTD, this gauge often reflects how investors view the durability of earnings in a steady but relatively mature retail market.
Here, the current P/E of 16.4x is higher than the estimated fair P/E of 13.2x. This indicates that investors are paying a richer price than the fair ratio implies the shares might warrant over time. The same 16.4x level is also above the peer average of 13.9x and the wider JP Consumer Retailing industry at 12.7x, which is a clear signal that SAN-ALTD trades at a premium to comparable businesses.
Explore the SWS fair ratio for SAN-ALTD.
Result: Price-to-Earnings of 16.4x (OVERVALUED)
Still, the SAN-ALTD story can change quickly if annual net income growth stays weak, or if Okinawa consumer spending softens and crimps supermarket traffic.
Find out about the key risks to this SAN-ALTD narrative.
Another View: SAN-ALTD Through A Cash Flow Lens
While the P/E ratio presents SAN-ALTD as expensive, the SWS DCF model presents a different picture. On that basis, the share price of ¥3,090 sits below an estimated future cash flow value of ¥10,846.95, which frames the stock as heavily undervalued. Which signal carries more weight for you?
Look into how the SWS DCF model arrives at its fair value.
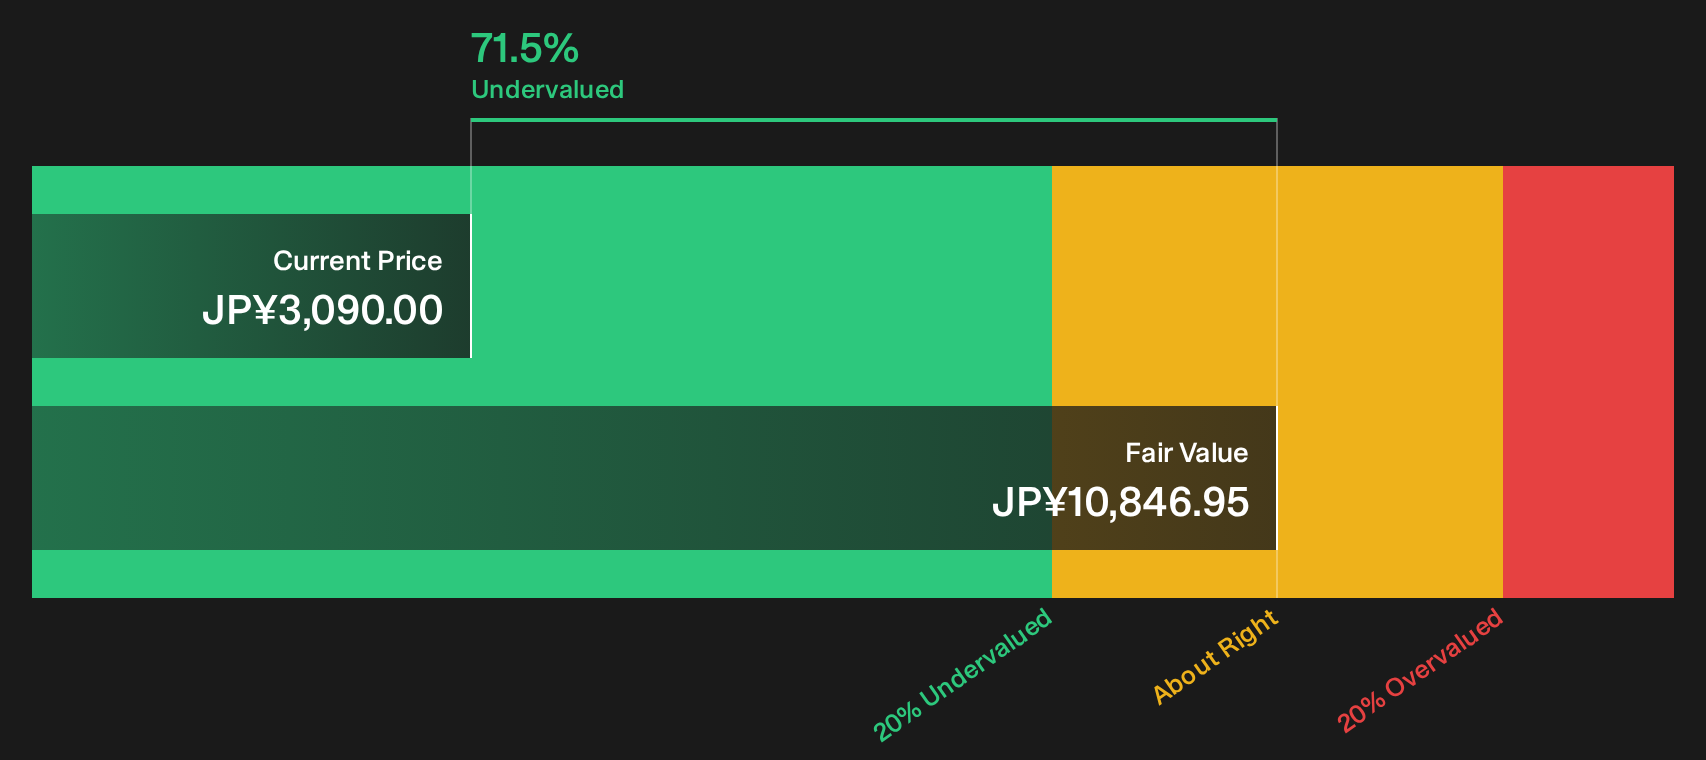
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SAN-ALTD for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on SAN-ALTD so far. If you want your own take, move quickly, stress test the numbers, and weigh both the 1 key reward and 3 important warning signs.
Looking for more ideas beyond SAN-ALTD?
If SAN-ALTD has sharpened your thinking, do not stop here. Fresh opportunities often sit just outside your current watchlist, and ignoring them can cost you options.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (21 results) that can handle tougher conditions.
- Hunt for quality at a discount by reviewing a 13 high quality undervalued stocks that combine cash generation with disciplined financial profiles.
- Prioritise durability and calmer portfolio swings by checking a 24 resilient stocks with low risk scores that scores well on financial strength and risk factors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com