
Global Payments (GPN) Could Be 22% Undervalued On Thailand Cross Border Payments Deal
Global Payments (GPN) is expanding its reach in Asian tourism by partnering with Centara Hotels & Resorts to power cross-border payment services across Centara’s Thailand properties, with transactions scheduled to start in the fourth quarter of 2026.
Against that backdrop, Global Payments’ recent news lands after a mixed price run, with the share price at US$81.88 and a 30 day share price return that fell 7.26%, while the 90 day share price return gained 4.68% and the 1 year total shareholder return declined 4.07%. This points to some short term momentum but a tougher multi year journey.
Scan how Global Payments compares to a hand picked group of payment and fintech peers by reviewing the 30 high quality undervalued stocks, which may be poised for a potential rerating.
Bulls point to Global Payments’ cross-border push and solid recent revenue and net income figures, while bears focus on the multi-year share price drag. Which side do the current valuation markers lean toward next?
Most Popular Narrative: 22% Undervalued
Global Payments is framed as undervalued in the most followed narrative, with a fair value of $105 compared to the recent $81.88 share price, putting analysts’ execution assumptions under the microscope.
The Worldpay acquisition and operational transformation program are being advanced through targeted cost and revenue synergies, with management reaffirming plans for $600 million of cost and $200 million of revenue synergies on a run rate basis by the end of 2028. This can provide a multi year tailwind to earnings growth and net margin improvement.
See why 43 investors see Global Payments as 22% undervalued.
Result: Fair Value of $105 (UNDERVALUED)
Still, the thesis can weaken if Worldpay integration stumbles or if prolonged travel weakness keeps Global Payments’ adjusted revenue and earnings below current expectations.
Find out about the key risks to this Global Payments narrative.
Another View: Global Payments On Earnings Multiples
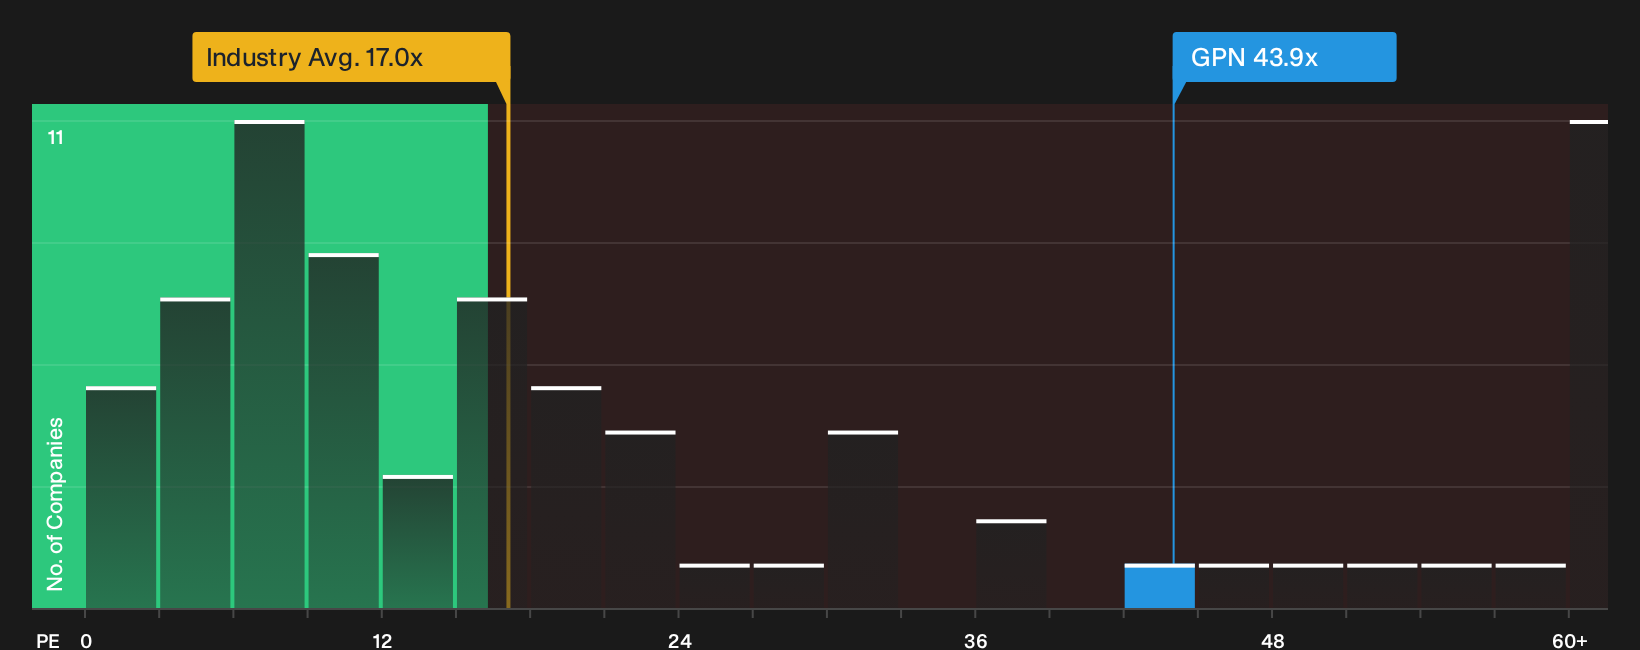
The first narrative frames Global Payments as undervalued on future cash generation and analyst fair value. A simple check on today’s P/E tells a different story. The shares trade on 43.9x earnings, versus 12.7x for peers and a 16.9x industry average, while the fair ratio sits at 30x.
That gap suggests the stock carries meaningful valuation risk if growth or margins fall short of expectations. It raises a practical question for investors: Is the stronger earnings outlook enough to justify such a rich multiple, or does the price still need to do some catching up to the fundamentals?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There have been mixed signals on Global Payments so far, and you may be feeling that tension. Use the data to pressure test your own thesis with our breakdown of 2 key rewards and 3 important warning signs.
Looking for more Global Payments investment ideas?
If Global Payments has sparked fresh questions about where to put capital to work next, do not stop here. Broaden your watchlist and give yourself more options.
- Target resilient performers by scanning a 31 resilient stocks with low risk scores that could help steady your portfolio when sentiment swings.
- Hunt for underfollowed opportunities by tapping into a 20 high quality undiscovered gems that screens for quality businesses flying under most radars.
- Strengthen your core holdings by reviewing a list of solid balance sheet and fundamentals (25 results) so you are not caught holding fragile finances when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com