
INTC Stock: What to Watch Before Earnings on October 22
Intel (INTC) heads into its Oct. 22 report on a strong run. It has beaten its own guidance for seven straight quarters. Last quarter, revenue rose 25% to $16.1 billion, its fastest growth in more than 15 years. Data center sales jumped 59%, and adjusted earnings of $0.42 per share came in at double what analysts expected. Given that track record, another beat is likely already expected. For the third quarter, Intel guided revenue of $15.8 billion to $16.8 billion, roughly flat with the second quarter. That’s unusual, since the third quarter has historically been stronger for Intel. CFO Dave Zinsner said Intel can’t make enough chips to meet demand.
The Fourth-Quarter Outlook Could Matter More
Zinsner said supply should start improving toward the end of the third quarter, with upside expected in the fourth. I believe that fourth-quarter guidance will decide how the stock reacts. A clear step up would show that supply is finally catching up with demand. A flat outlook would suggest the bottleneck is lasting longer than planned.
Foundry is the other thing to watch. Intel said its 14A process was on track to deliver a key design kit to customers in October. Any sign of a major outside customer for 14A would be meaningful. After Nvidia (NVDA) halted its trial of Intel’s 18A process, I argued that Intel’s recovery depended on winning large customers like that. The foundry business still lost about $2.1 billion last quarter, so a big customer would help show it can stand on its own.
About Intel Stock
Intel Corporation designs, manufactures, and sells computer chips and related technologies. Its products include processors and graphics chips for personal computers, servers, and data centers, as well as networking and edge-computing solutions. The company also provides semiconductor manufacturing services through its foundry business, producing chips for both Intel and external customers. Founded in 1968, the company is headquartered in Santa Clara, California.
Over the last 12 months, INTC stock has surged sharply by 169%, far outperforming the S&P 500’s ($SPX) 17% gain during the same period. The rally was driven by a 10% stake from the U.S. government and a $5 billion Nvidia (NVDA) investment. But since hitting a high of over $142 in late June, the stock has fallen to about $100 as of this writing. The dip came mainly due to dilution from a roughly $23 billion equity raise and ongoing foundry losses.
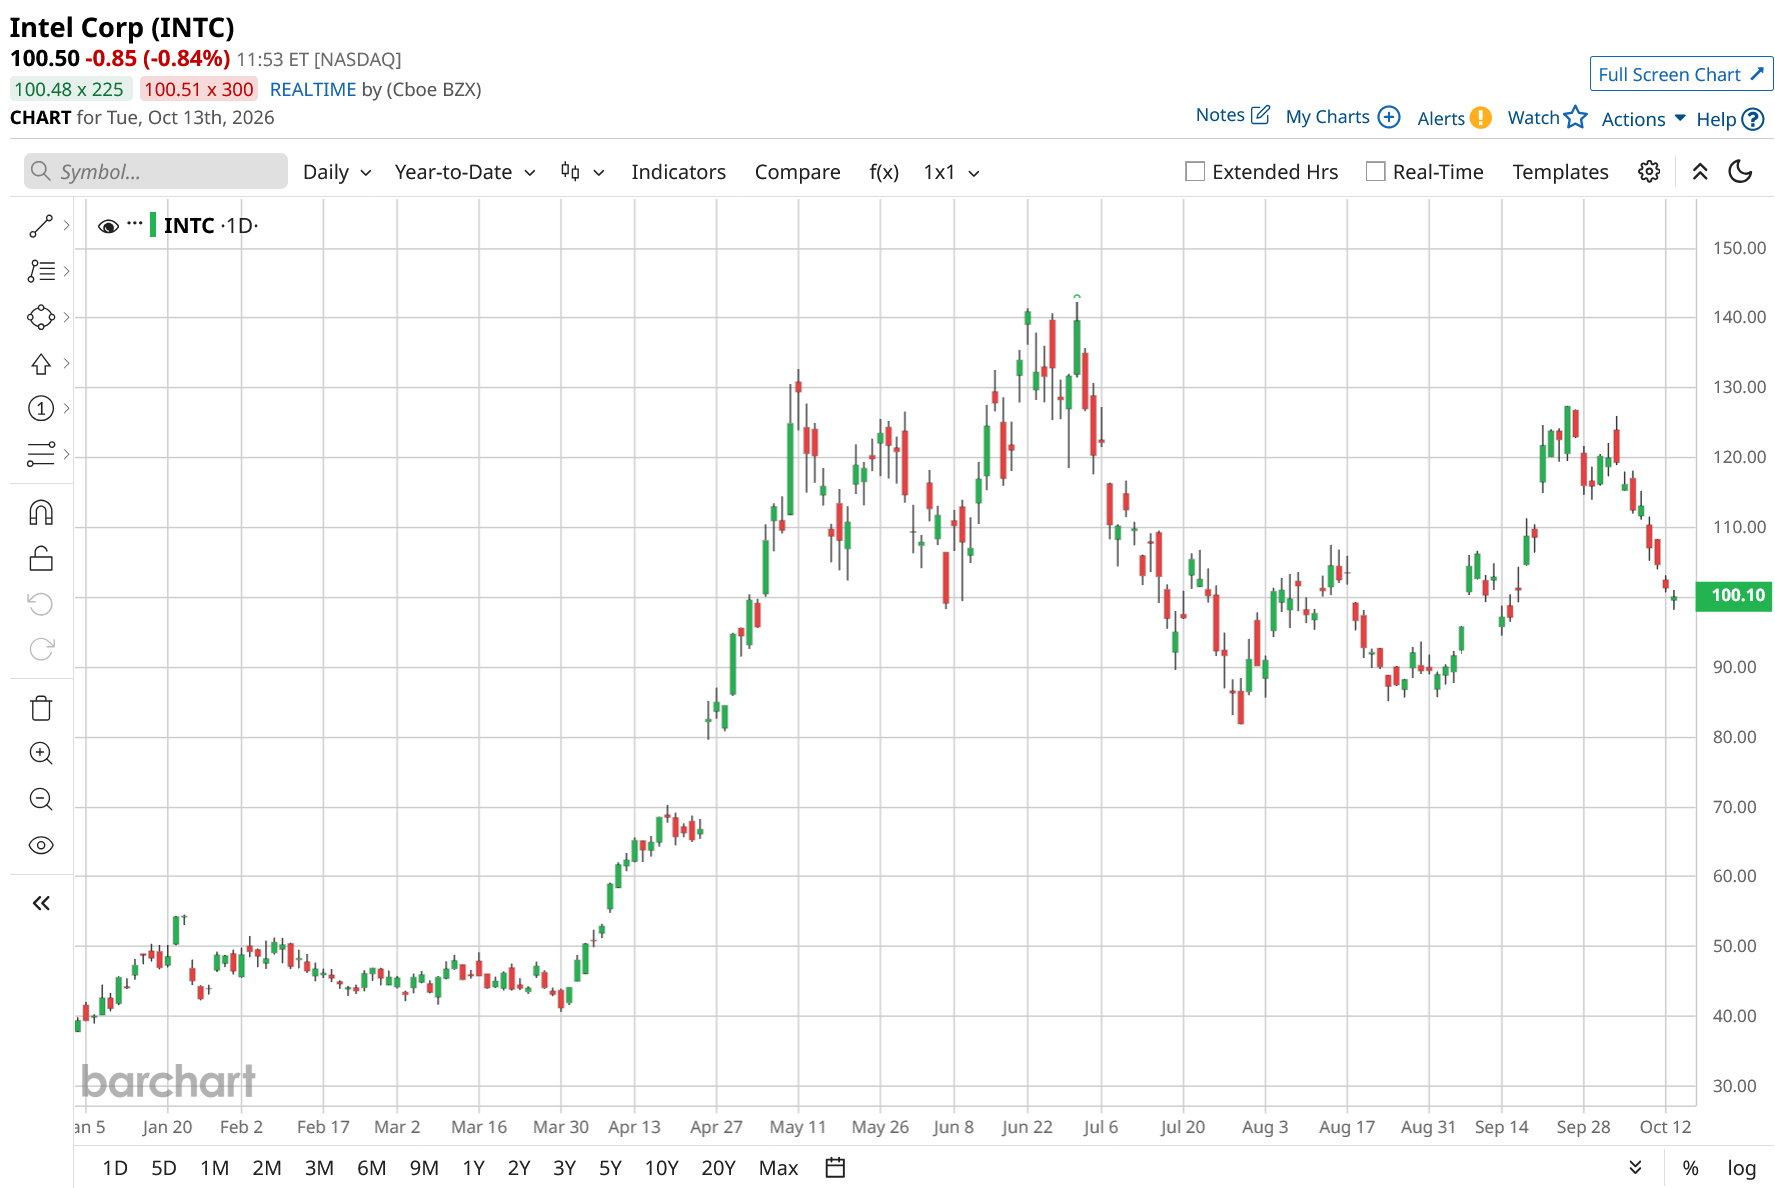
Intel’s forward GAAP price-to-earnings (P/E) isn’t meaningful, since it is still posting losses on a reported basis. So the forward price-to-sales (P/S) ratio gives a better idea of how much the market’s view of the company has shifted. At 10x, it sits more than three times its 5-year average of 3.14x. The EPS outlook explains the premium. Analysts expect earnings to surge 262% this year, 36% in 2027, 44% in 2028, and then 60% in 2029. That later jump likely depends on the foundry business starting to pay off. Looking at the balance sheet, Intel holds net debt of $21 billion. This isn’t necessarily a problem right now, but the company also intends to spend more on factories next year. Overall, I think the stock already prices in a successful turnaround. This is what makes winning a big foundry customer even more important.
What Do Analysts Think of INTC Stock?
TD Cowen analyst Joshua Buchalter reiterated a “Hold” rating and set a price target of $115 on INTC stock. The analyst rates Intel as “Hold” because he believes much of the company’s recent progress is already reflected in the stock price. While Intel is improving its business and benefiting from optimism around AI and its foundry plans, the analyst wants to see stronger proof that the company can significantly grow revenue before becoming more positive on the stock. In contrast to TD Cowen, Bank of America Securities analyst Vivek Arya maintained a “Buy” rating on INTC with a price target of $145.
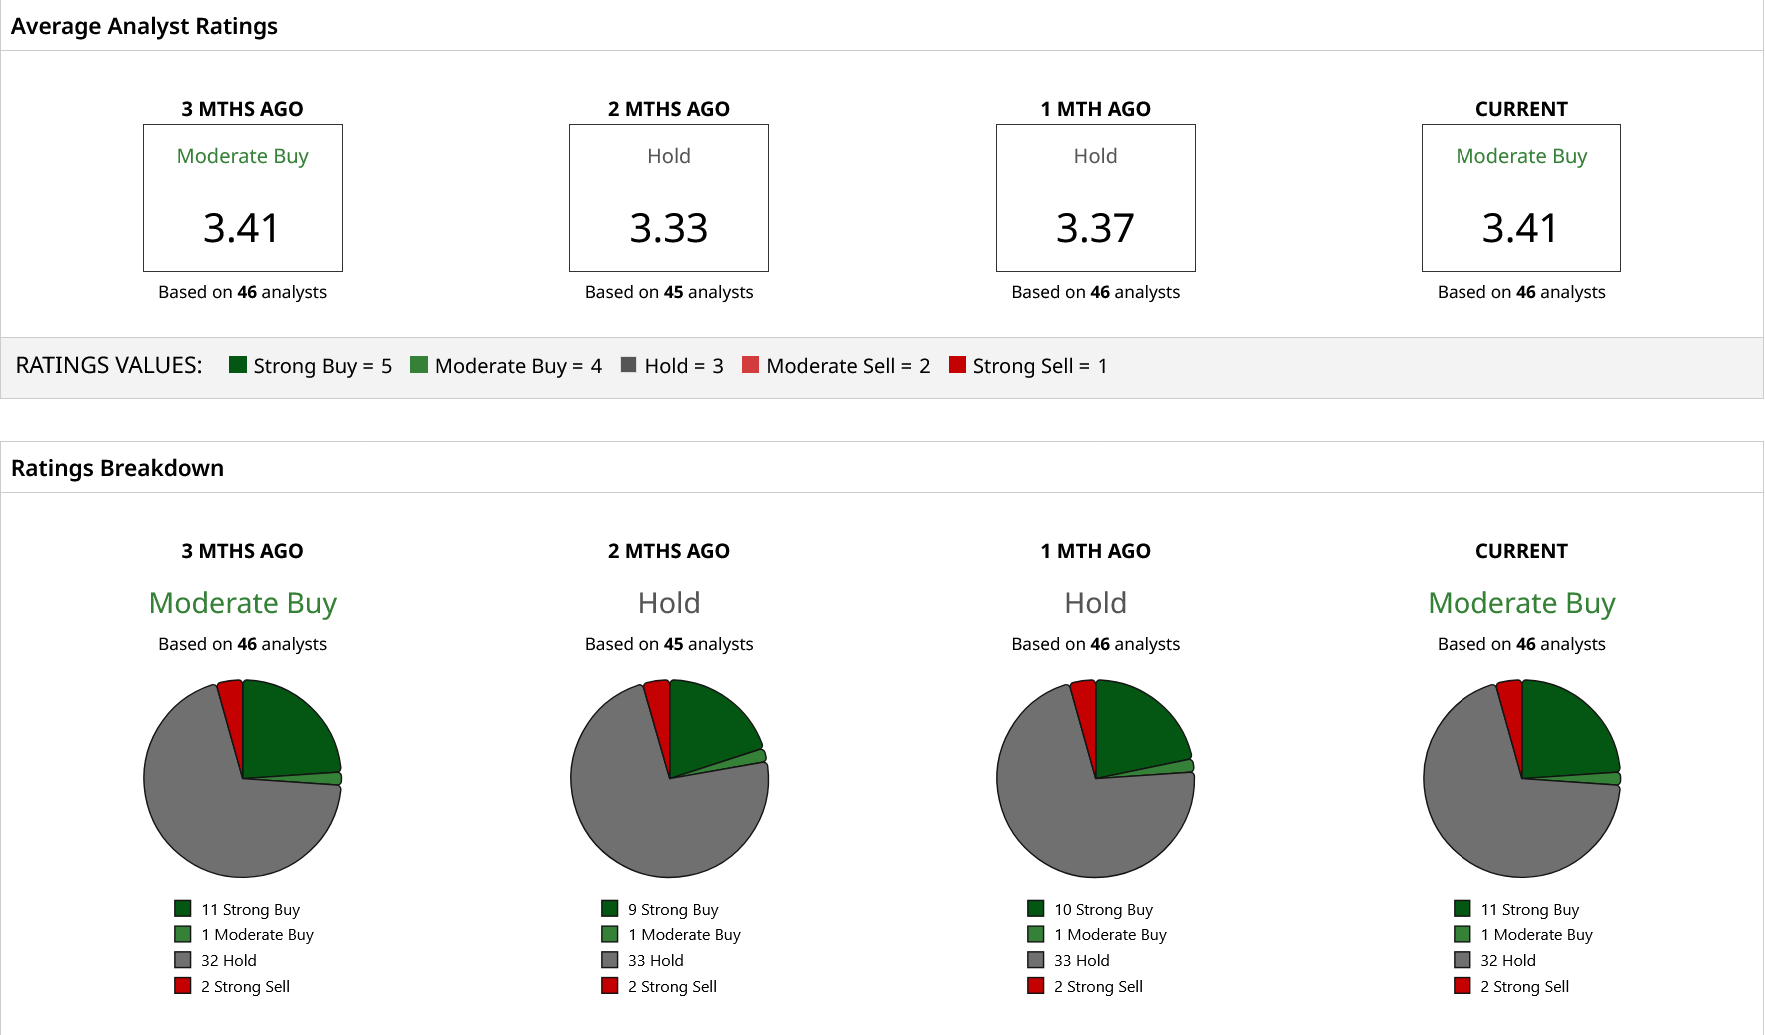
Based on 46 Wall Street analysts covering the stock, INTC holds a consensus “Moderate Buy” rating. Out of those, 12 have a “Strong Buy” rating, one has a “Moderate Buy” rating, 31 have a “Hold” rating, and two have a “Strong Sell” rating. The stock’s mean price target of $115 sits below its current share price. However, the high price target of $200 reflects 67% upside from the current levels. This suggests that analyst sentiment is mixed, with most staying cautious, while the $200 high target reflects significant upside if Intel delivers on its AI and foundry plans.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.