
Round One (TSE:4680) Posted Fresh Sales Figures, Is The Stock Still Undervalued?
Sales update triggers closer look at Round One
Round One (TSE:4680) just released unaudited sales figures through September 2026, reporting JPY 11,628 million for the month and JPY 66,074 million year to date. This gives investors fresh data on current trading.
The latest sales update lands as Round One’s share price trades at ¥1,322, with a 30‑day share price return of 12.65% and a year to date gain of 16.84%. The 5 year total shareholder return of 209.28% points to long running positive momentum that recent monthly gains appear to be extending.
Scan how Round One compares with other consumer-focused operators showing fresh trading momentum by reviewing our curated list of 74 high quality undiscovered gems in similar segments.
Short term traders may see Round One’s recent 30 day jump as a reason to pause, while longer term holders might be weighing up buying in before any pullback. So what does the current valuation actually suggest?
Price-to-earnings of 21x for Round One: Is it justified?
Round One trades on a P/E of 21x, which sits below several benchmarks and provides a reference point against the current ¥1,322 share price.
The P/E ratio compares what investors pay today with the company’s earnings per share. For a leisure operator like Round One, this yardstick links directly to how the business converts customer visits into profits, rather than being distorted by asset values or one-off gains.
On this measure, the stock is described as good value versus both the JP Hospitality sector average of 22x and a peer group average of 23.2x. It is also assessed as inexpensive relative to an estimated fair P/E of 27.5x, which indicates that the current multiple sits well below a level the market could plausibly move toward if sentiment or results remain supportive.
The discount across all three reference points is clear. Round One is framed as good value compared to peers, the broader industry, and the estimated fair P/E, which together present a consistent picture of a market that is pricing its earnings more cautiously than those benchmarks.
Explore the SWS fair ratio for Round One.
Result: Price-to-earnings of 21x (UNDERVALUED)
Still, Round One depends on discretionary leisure spending. Any squeeze on household budgets or shifts in entertainment habits could quickly challenge the current earnings-based story.
Find out about the key risks to this Round One narrative.
Another view on Round One’s value
The P/E points to Round One looking inexpensive, yet our DCF model also suggests the shares trade below an estimate of future cash flow value at ¥1,569.43 versus the current ¥1,322 price. Two methods both hint at a gap. The real question is what eventually closes it.
Look into how the SWS DCF model arrives at its fair value.
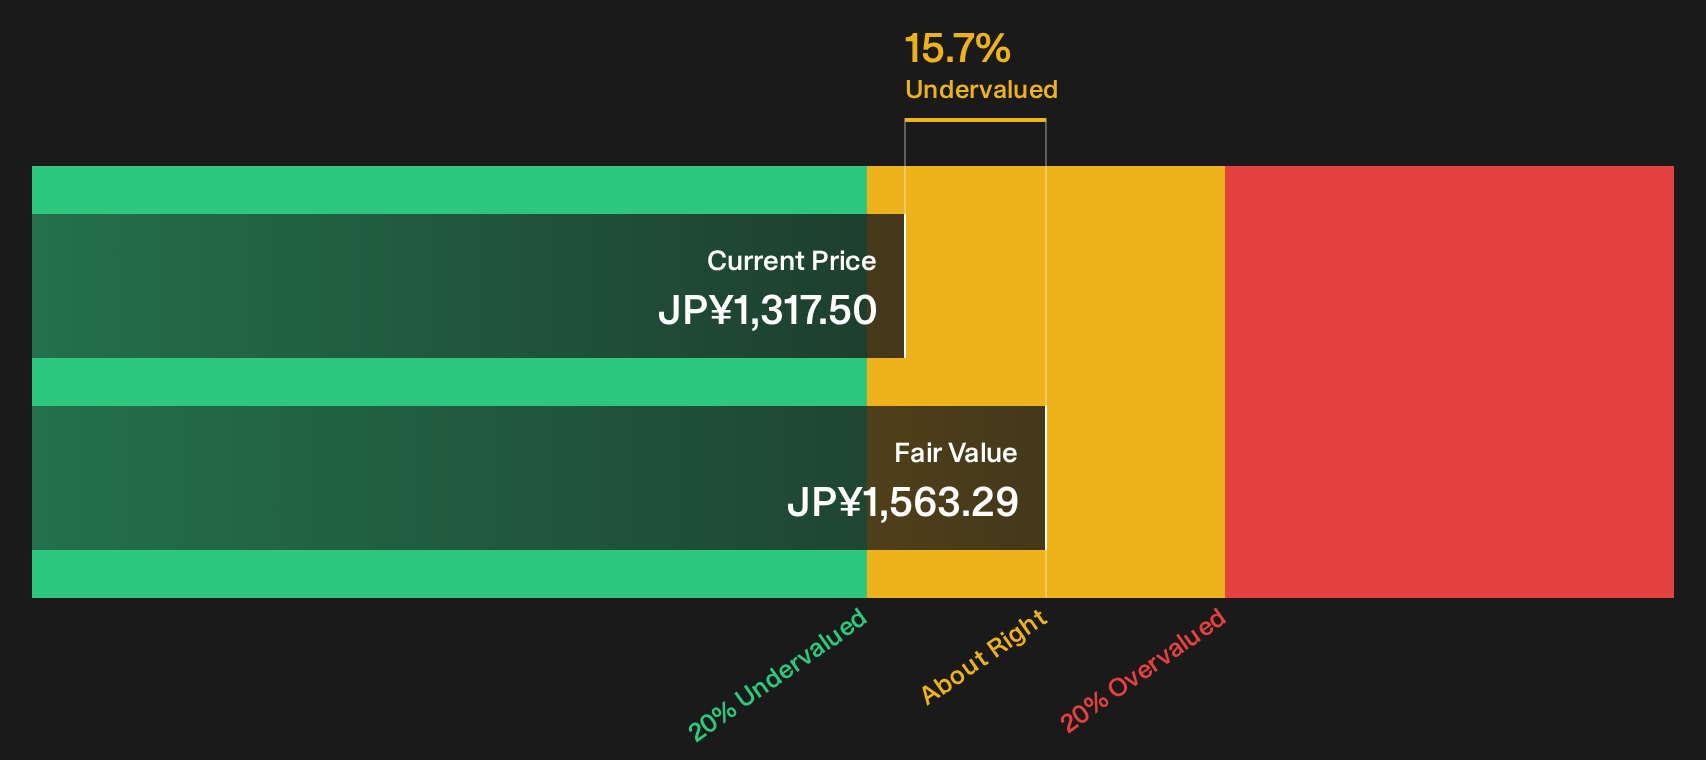
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Round One for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The Round One story appears interesting but incomplete if you look only at the headline valuation. Consider both the potential risks and opportunities while the details are fresh by reviewing the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Round One?
If Round One has your attention, broaden your watchlist with a few focused stock ideas that match different approaches to risk, value, and income.
- Target potential value opportunities by reviewing the 13 high quality undervalued stocks that match strong fundamentals with attractive pricing.
- Prioritise resilience first and filter for 24 resilient stocks with low risk scores that may offer a smoother ride when markets turn choppy.
- Build a cash flow focused watchlist with 27 dividend fortresses that aim to combine meaningful yield with underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com