
JD.com (JD) Stock Looks Below Fair Value After Deal Talk
JD.com has seen its share price fall a long way over the past few years, which puts a spotlight on whether the current US$26.72 level lines up with the earnings the business is producing today. With fresh headlines around a possible Ceconomy acquisition in Europe, the question for you is how much of JD.com's profit power is already baked into the stock.
- The share price is down 63.1% over 5 years, which puts long term performance under pressure and makes the earnings tag on today's valuation more important than usual.
- The reported plan to acquire Ceconomy for about US$2.5b can reshape JD.com's growth mix and may influence future earnings quality, capital intensity and how quickly profits convert into cash.
- Your read on JD.com is one view; the desks covering it have another. See what analysts think JD.com's shares could be worth.
The issue now is whether JD.com's current share price is adequately explained by the earnings the business generates and what those profits may look like in the years ahead.
To put JD.com's earnings driven story in context, it can help to compare it with other businesses by scanning 29 high quality undervalued stocks
Does JD.com Look Undervalued on Earnings?
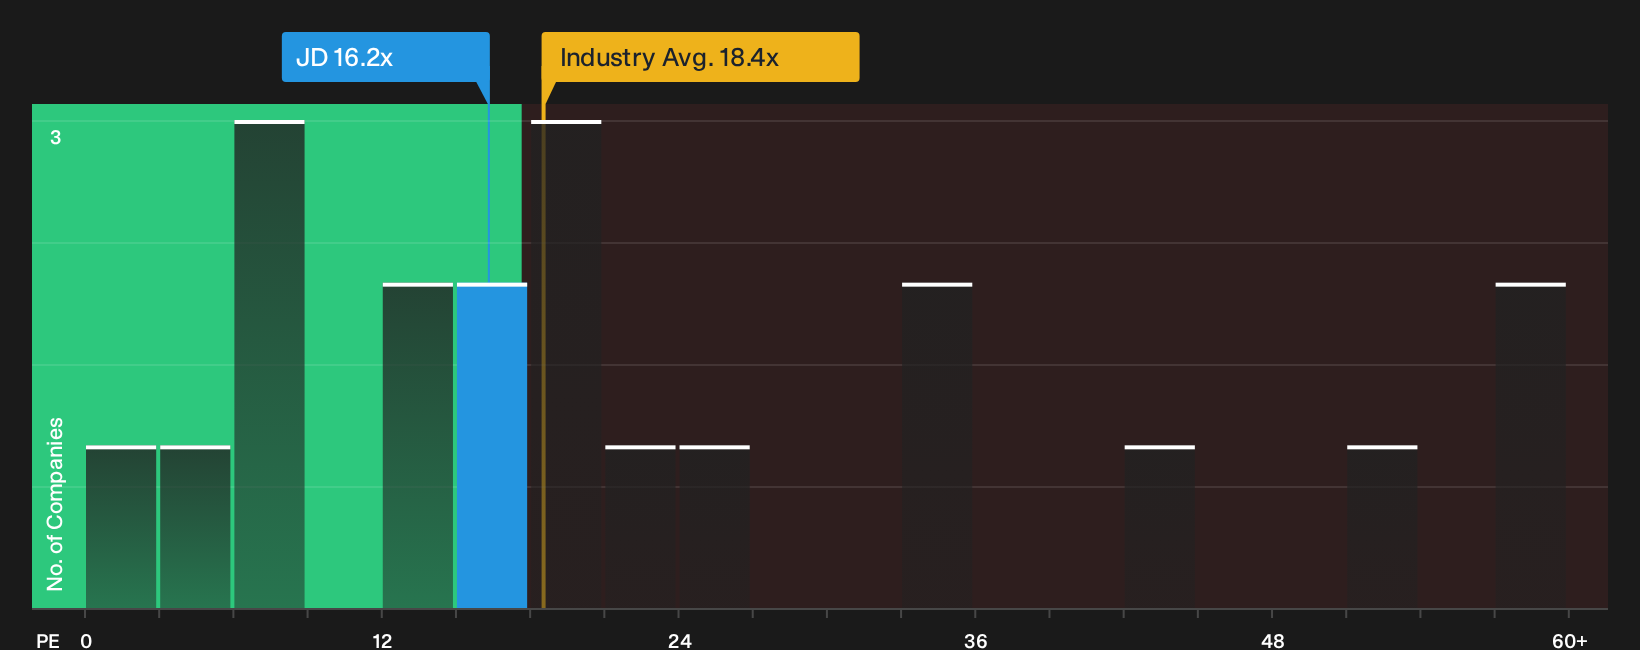
The P/E ratio fits JD.com well because earnings are the key thing investors are watching as the business adjusts its retail mix and evaluates deals like Ceconomy. At roughly 16.2x earnings, JD.com trades below the Multiline Retail industry average of about 18.4x and sits at a steeper gap to the broader peer group on roughly 31.4x. The stock also changes hands at a discount to the tailored fair multiple that factors in JD.com's profitability profile, growth assumptions, size and risk. This points to the shares being undervalued on this yardstick.
Because the Ceconomy deal has pushed JD.com into the headlines again, it matters that even after that news the market is still pricing the stock below both sector and peer P/E levels. For you as a shareholder or potential buyer, the question is whether current earnings quality and any impact from a Ceconomy acquisition justify the market keeping JD.com's P/E multiple below that fair benchmark, or whether the gap eventually closes. Explore the numbers behind JD.com's P/E valuation.
The JD.com Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St's Community page pick up where the JD.com valuation puzzle leaves off, by spelling out which growth, margin and earnings paths would need to play out for the current price to look either too low or too high. Each one ties its number to a specific view on how JD.com's growth profile, profitability and risk mix might evolve, giving you a clear reference point you can revisit as fresh information arrives.
One of the top community narratives on JD.com: 32% undervalued
"Logistics innovation, supply chain investment, and diversification into new businesses and markets drive margin expansion, operating efficiency, and sustained long-term growth..."
Discover why this Narrative puts JD.com at 32% undervalued.
One more JD.com check that belongs beside the share price
Price tags and earnings multiples only tell part of the story. The people setting JD.com's priorities and the way they are rewarded can tilt long term outcomes in very different directions. See who runs JD.com and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com