
Is DaisekiLtd (TSE:9793) Undervalued As Earnings Guidance And Dividend Rise?
DaisekiLtd (TSE:9793) is back in focus after half year earnings to August 31, 2026 showed higher sales and net income, along with fresh full year guidance and a higher second quarter dividend.
That earnings release landed after a softer few months for the share price, with DaisekiLtd posting a 30 day share price return of down 2.87% and a 90 day move of down 7.91%. Even though the year to date share price return is up 5.81% and the 1 year total shareholder return is 14.81%, the 3 and 5 year total shareholder returns remain in decline. This points to short term momentum improving from a weaker longer term track record as investors reassess both growth potential and risk after the higher guidance and dividend.
See how DaisekiLtd compares with other waste management and recycling plays by reviewing our hand picked list of solid balance sheet and fundamentals (21 results) that have weathered recent market swings with relatively resilient fundamentals.
DaisekiLtd has bounced on fresh guidance and a richer dividend, yet the longer term chart still shows scars. Is most of the easy recovery already priced in, or does valuation still hint at more headroom?
Preferred P/E of 16.4x: Is it justified?
DaisekiLtd closed at ¥3,550, and on the latest numbers the shares trade on a P/E of 16.4x, which screens as expensive relative to both peers and its own estimated fair P/E.
The P/E multiple compares the current share price to earnings per share, so it reflects how much investors are paying for each unit of profit. For a waste treatment and recycling business like DaisekiLtd, that ratio often acts as a shorthand for how much confidence the market has in the durability of cash flows and future profit growth.
Here, the 16.4x P/E sits above the estimated fair P/E of 16.3x and above the JP Commercial Services industry average of 13.4x, as well as the 10.8x peer average. That combination points to investors already paying a richer price than both sector benchmarks and the level the market could move towards if sentiment cools.
Explore the SWS fair ratio for DaisekiLtd.
Result: Price-to-earnings of 16.4x (OVERVALUED)
Still, DaisekiLtd carries clear risks if industrial waste volumes soften or regulators tighten rules in ways that raise treatment costs and squeeze profitability.
Find out about the key risks to this DaisekiLtd narrative.
Another view on DaisekiLtd’s value
The P/E screen says DaisekiLtd looks expensive, yet the SWS DCF model points the other way. On that cash flow view, the shares at ¥3,550 sit about 42% below an estimated fair value of ¥6,139.21. Which lens deserves more weight when the signals clash?
Look into how the SWS DCF model arrives at its fair value.
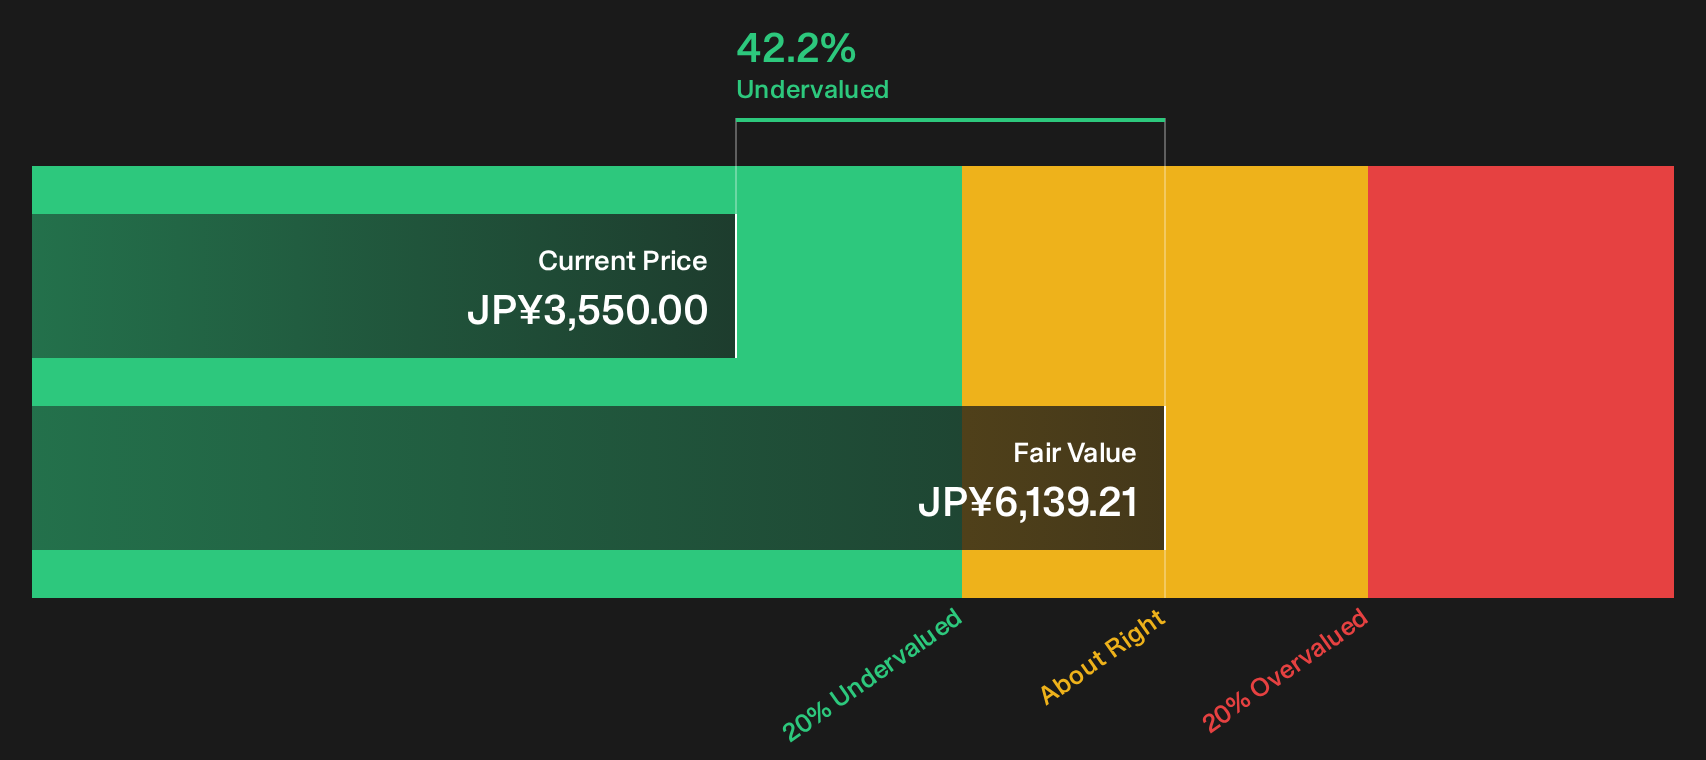
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DaisekiLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on DaisekiLtd’s valuation and risk profile make this a stock you need to inspect yourself, not just read about. Move quickly, review the underlying data, and weigh both the potential upside and the concerns highlighted in the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DaisekiLtd?
Do not stop your research with DaisekiLtd. Use the Simply Wall Street Screener to surface fresh opportunities that match the kind of portfolio you want to build.
- Target potential bargains before the crowd by scanning our hand picked 13 high quality undervalued stocks that line up strong fundamentals with modest market expectations.
- Strengthen your income stream by focusing on companies in the 27 dividend fortresses that pair higher yields with robust underlying financials.
- Protect your downside by reviewing the 24 resilient stocks with low risk scores that combine resilient balance sheets with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com