
Round One And 2 Other Japanese Insider Backed Growth Stocks
The IMF flags two big forces right now. AI investment is helping keep the world economy running hotter than expected, while high public debt and tighter money create more pressure on weaker businesses. That mix puts fast growing Japanese companies with management heavily invested in their own shares in a sweet spot. This article highlights three such stocks, explaining why insiders’ conviction could matter for your portfolio.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where leadership and analysts are aligned on an optimistic outlook. However, if you want the absolute best, these 28 high growth high conviction stocks are the cream of the crop.
Round One (TSE:4680)
Round One runs indoor leisure complexes across Japan, combining bowling, arcade games, karaoke, billiards and Spo Cha multi sport arenas into a repeatable format well suited to rapid roll outs. The group is valued by the market at about ¥347.5b.
Round One aligns closely with the screener theme because its indoor leisure chain is built for store expansion. Analysts expect earnings to grow 15.07% a year with revenue forecast to rise 8.8% a year. That kind of growth profile only holds if one unseen pressure on profitability moves in its favour.
If that margin squeeze is what worries you, start with the DCF valuation analysis for Round One to see whether the current share price already reflects thinner profitability.
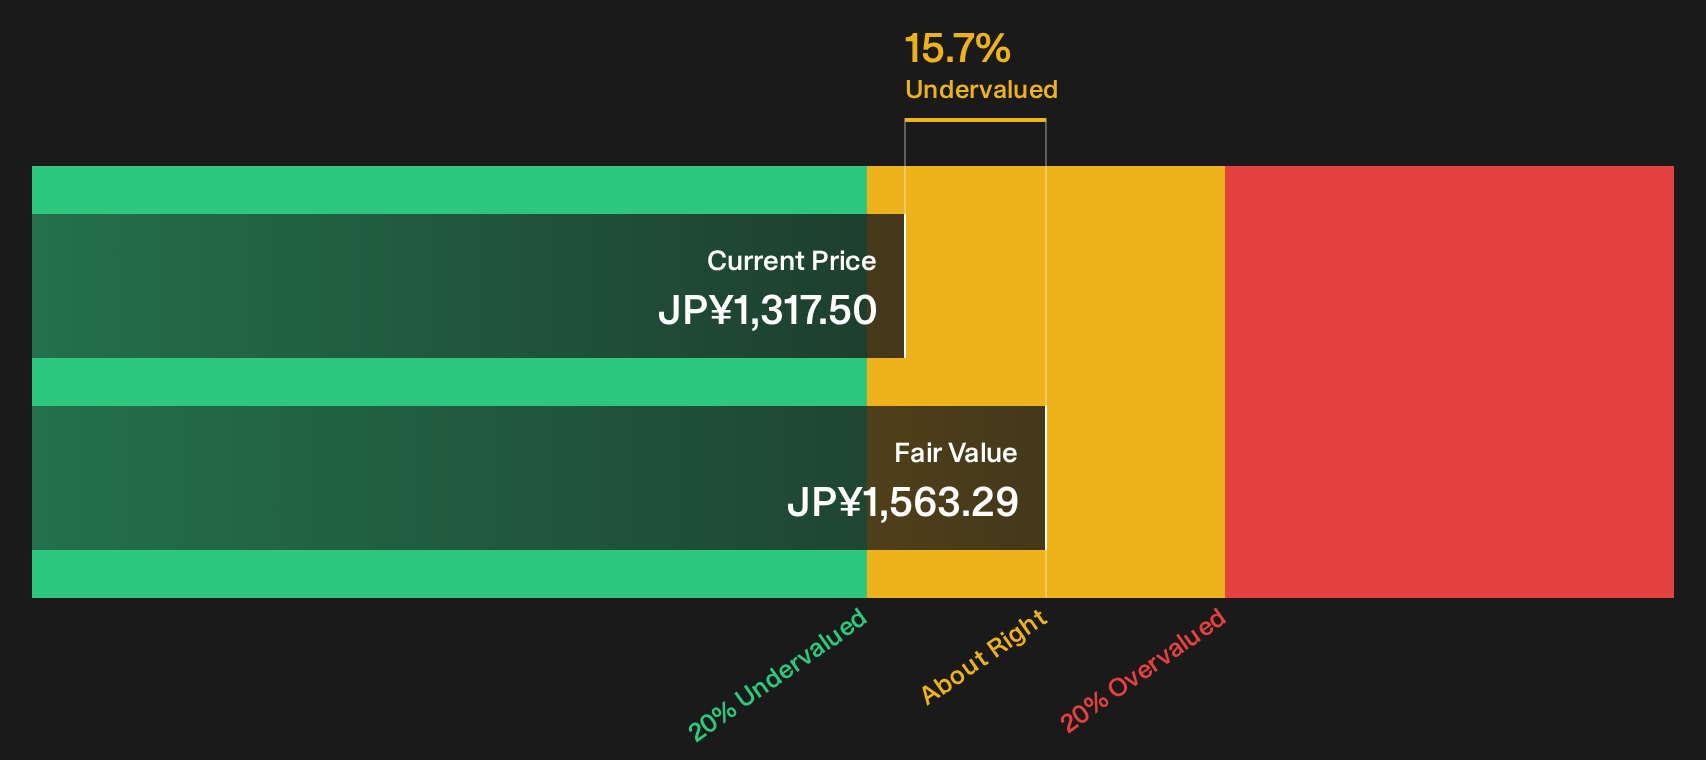
Sansan (TSE:4443)
Sansan runs cloud tools that turn business card and meeting data into searchable, companywide contact intelligence. This is a clear fit for a fast growing SaaS theme. The group is headquartered in Tokyo and has a market value of about ¥254b.
Sansan lines up neatly with the screener theme because earnings are forecast to rise 23.02% a year, while net sales guidance for FY2027 points to continued expansion on a much stronger profit base than a year ago. The mix of fast growing subscription income and rising margins looks powerful, depending on how pressure on that profitability story plays out.
That profitability swing is exactly what the analysis report for Sansan unpacks, allowing you to see whether Sansan’s growth engine is quietly stretching its limits or just getting started.

Micronics Japan (TSE:6871)
Micronics Japan focuses on semiconductor test equipment, with the probe card division generating about ¥84.9b of its roughly ¥85.3b in segment revenue and a smaller ¥1.4b contribution from TE equipment. The business, valued at about ¥598b, is tightly linked to chip manufacturing growth.
Micronics Japan is closely aligned with the fast growing, insider-backed theme through its probe cards and test gear, with earnings forecast to rise about 24.9% a year after roughly 89.4% profit growth in the latest period. That momentum depends heavily on what happens to one crucial swing factor in chip demand and pricing.
That single swing factor is exactly what the 2 key rewards and 1 important major warning sign reveals, showing where Micronics Japan’s upside and pressure points could be accelerating next.

Seeking Fresh Alternatives Beyond These Three
Fresh breakouts, momentum building, and under the radar for now. The best entries rarely stay mispriced for long, so scan new ideas before the crowd and act now.
- Hunt for consistent cash generators and stress test your dividend income using the curated 27 dividend fortresses before yields get compressed by investors chasing the same payouts.
- Ride the next wave of automation by zeroing in on 91 robotics and automation stocks that are positioned to benefit if robotics adoption keeps climbing and valuations still look reasonable.
- Target the plumbing behind the AI surge and track infrastructure players through 92 AI infrastructure stocks before demand stories become fully reflected in their share prices.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com