
Is Mitsui (TSE:8031) Undervalued Following Its Completed Share Buyback?
Mitsui (TSE:8031) has completed its previously announced share repurchase, buying 8,285,900 shares between August and September for ¥42,114.32 million. This amount is equal to 0.29% of outstanding equity.
The completed buyback lands at a time when Mitsui’s 1 year total shareholder return of 36.56% and 3 year total shareholder return of 94.97% contrast with a more muted 3.30% year to date share price return and a recent 2.96% 1 month share price decline. This suggests strong longer term compounding, while shorter term momentum has started to cool.
See how Mitsui compares with other capital-efficient businesses using our curated list of 13 high quality undervalued stocks.
Recent price softness after a completed buyback can either flag investors cooling on Mitsui or simply lag how the underlying operations are tracking. To judge which story fits, the next step is to test the valuation.
Most Popular Narrative: 21% Undervalued
Mitsui last closed at ¥4,910 against a narrative fair value of ¥6,209. This frames the recent buyback as part of a bigger cash flow story rather than a one off signal.
The main factor that has to go right is that Mitsui continues to execute disciplined capital allocation, including maintaining COCF around the targeted JPY 1.2 trillion level while recycling assets and returning over 50% of COCF to shareholders under MTMP2029.
See why 21 investors see Mitsui as 21% undervalued.
Result: Fair Value of ¥6,209 (UNDERVALUED)
Still, the narrative around Mitsui hinges on commodity exposed cash flows and energy segment volatility, where softer iron ore, coal and LNG conditions have already weighed on recent profit and core cash generation.
Find out about the key risks to this Mitsui narrative.
Another View: Mitsui Through The Cash Flow Lens
While the analyst narrative points to a fair value of ¥6,209 for Mitsui, the Simply Wall St DCF model paints a more cautious picture. On that measure, the shares at ¥4,910 sit above an estimated future cash flow value of ¥4,043, which leans toward an overvaluation signal.
This gap between a richer earnings-based fair value and a lower DCF output leaves investors with a clear question: Which story do you trust more, the cash the business is expected to throw off or the multiple the market might one day pay for those earnings?
Look into how the SWS DCF model arrives at its fair value.
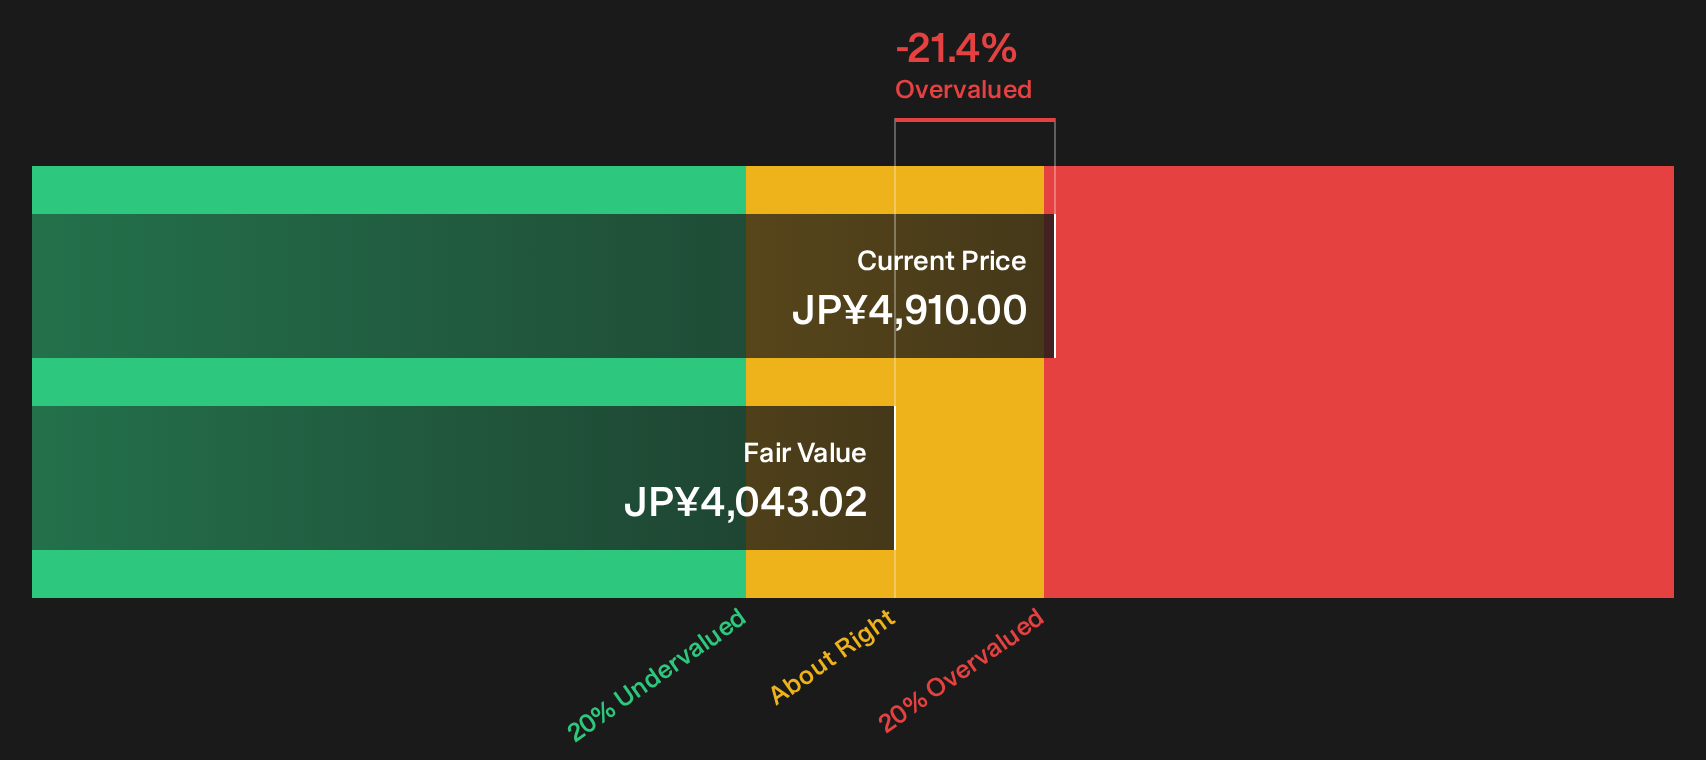
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsui for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or early opportunity? If you want to move quickly and build your own conviction, weigh both sides by reviewing the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Mitsui?
Once you have a view on Mitsui, the real edge comes from lining it up against other opportunities that could shift your portfolio’s risk and reward profile.
- Target income resilience by scanning companies that aim to pair sizable yields with staying power using our 27 dividend fortresses.
- Pressure test your bargain-hunting instincts by comparing Mitsui against a 13 high quality undervalued stocks built around quality and pricing discipline.
- Tilt toward capital preservation by focusing on a 24 resilient stocks with low risk scores that emphasizes balance sheet strength and a steadier return profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com