
Duke Energy (DUK) Nears Storm Restoration, Is The 14% Undervaluation Case Convincing?
Duke Energy dividend news and grid investment backdrop
Duke Energy (DUK) is back in focus after reporting near completion of power restoration in North Florida following Hurricane Isaias, alongside a long term grid investment plan that includes fresh common and preferred dividend declarations.
Duke Energy shares trade at US$117.69, with the 7 day share price return of 3.38% partly offset by a 90 day share price decline of 6.87%, while the 3 year total shareholder return of 47.28% reflects a very different longer term experience.
The recent uptick in the share price sits alongside a one year total shareholder return that is down 3.39%, suggesting the latest grid investment plan, hurricane restoration update and fresh dividend declarations are being weighed against earlier concerns and shifting views on risk and income stability.
Scan a curated group of regulated utilities showing similar grid upgrade and income stories to Duke Energy through the 43 power grid technology and infrastructure stocks.Bulls point to Duke Energy’s regulated grid buildout and steady dividends, while bears see storm risk and recent share price weakness. Which case does the current valuation lean toward next?
Most Popular Narrative: 14% Undervalued
Duke Energy’s most followed narrative pegs fair value at about $136.94, above the recent $117.69 close, which puts the latest dividend and grid headlines against a valuation gap that some investors see as meaningful.
Major economic development wins in Duke Energy territories, including large data center projects, are now supported by about 7.6–7.8 GW of executed electric service agreements and a 15.4 GW late stage pipeline that is expected to be fully contracted by the first half of 2027, which could translate into multi year load growth and higher regulated revenue as this contracted demand is served.
See why 87 investors see Duke Energy as 14% undervalued.
Result: Fair Value of $136.94 (UNDERVALUED)
Still, the narrative around Duke Energy can shift quickly if the planned US$10b equity issuance pressures per-share metrics, or if higher financing costs squeeze returns on that record capital plan.
Find out about the key risks to this Duke Energy narrative.
Another View on Duke Energy’s Valuation
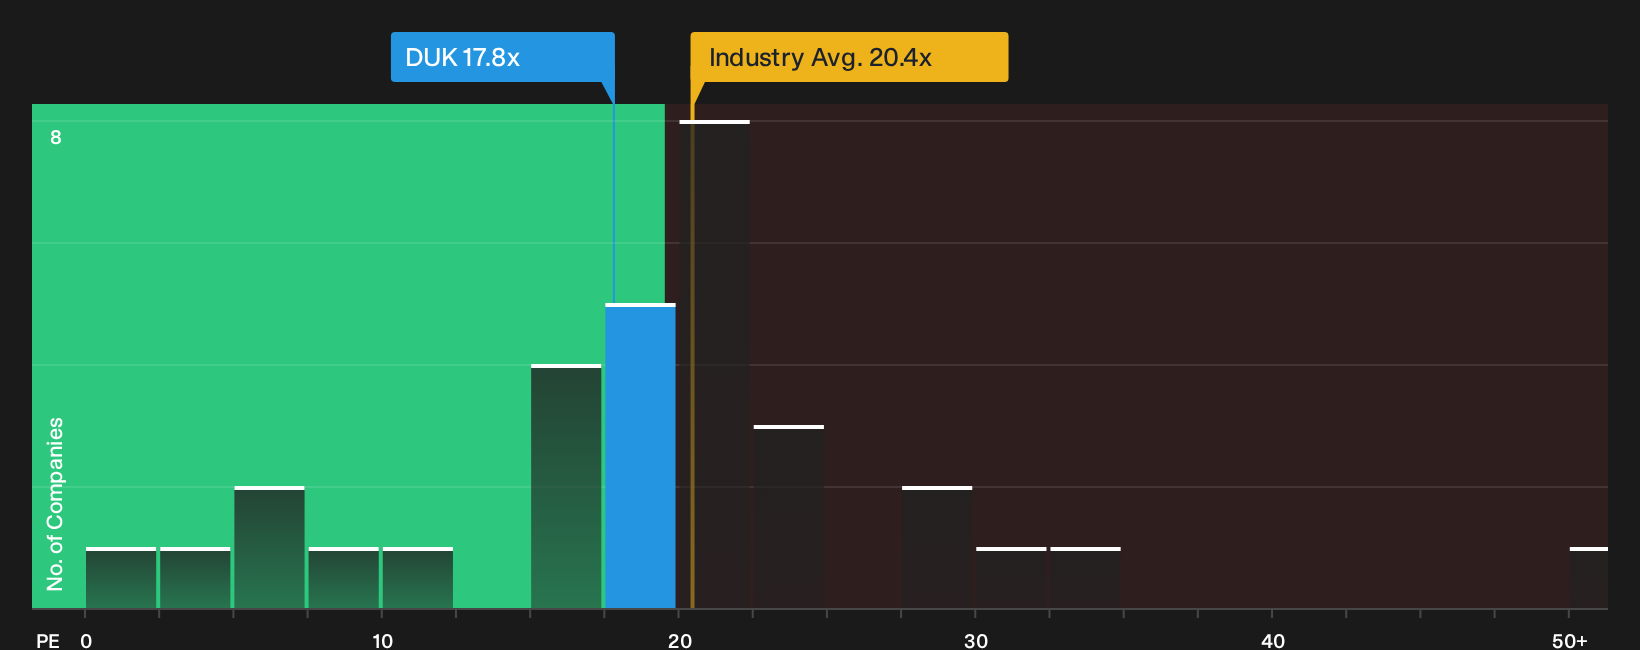
The earlier narrative leans on analyst targets that put Duke Energy at a fair value of $136.94, with the stock trading on a P/E of 17.8x compared with 22.7x for peers and 20.4x for the wider US Electric Utilities industry. That gap can look like a discount or a warning label, depending on how you see the risks around equity issuance, interest coverage and slower forecast growth than the broader US market.
Our fair ratio estimate of 21.1x sits closer to the peer and industry levels than to the current 17.8x. This suggests the market could shift toward that higher multiple if the grid buildout and contracted data center demand keep supporting earnings quality. If the share price instead stays pinned near today’s lower P/E, is that the market calmly pricing in those funding and rate pressures, or leaving room for potential upside if execution holds together?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Duke Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Duke Energy so far. If you want to move quickly and reach your own stance, weigh the 4 key rewards and 2 important warning signs.
Looking for more Duke Energy style investment ideas?
If you want more context around Duke Energy, compare it with peers through focused stock ideas so you are not reacting late to the next move.
- Target quality at a discount by checking companies that pass strict value and fundamentals filters through the 29 high quality undervalued stocks.
- Prioritise resilience by reviewing businesses with strong balance sheets and solid financial footing through the list of solid balance sheet and fundamentals (25 results).
- Spot early opportunities by scanning financially sound companies that are still under the radar using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com