
After a 60% Rally in Just 3 Months, Palantir Stock Can Still Soar Higher
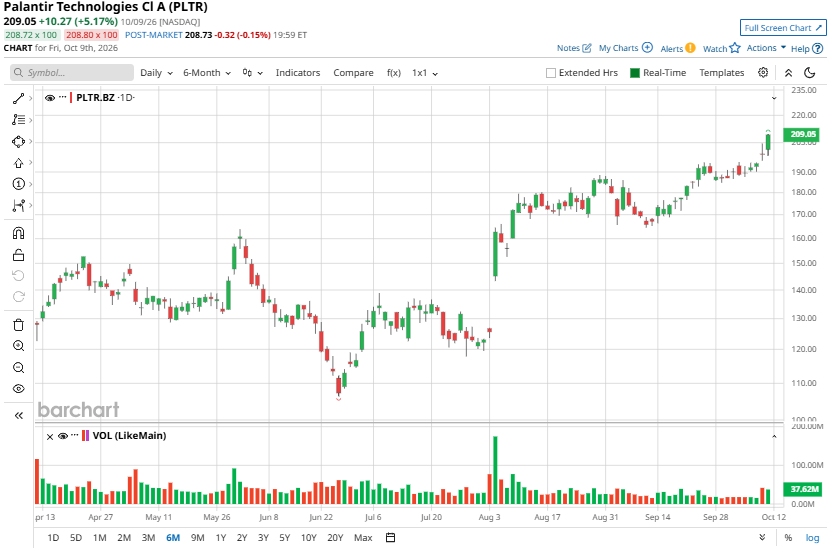
Palantir (PLTR) stock has made a solid recovery, climbing 60% over the past three months. The sharp rally has followed stronger-than-expected second-quarter results and an upward revision to the company’s financial outlook, strengthening investor confidence in its growth trajectory.
Palantir’s operating performance points to solid underlying business strength. Accelerating revenue growth signals increasing demand for its Artificial Intelligence Platform (AIP). At the same time, robust expansion in the U.S. commercial segment highlights the company’s growing ability to convert AI adoption into commercial opportunities.
While PLTR stock has rallied significantly, its business momentum isn’t likely to slow anytime soon, supporting the rally further. Let's take a closer look.
U.S. Business Strength to Power Palantir Stock Higher
Palantir appears well-positioned to sustain strong growth, led by accelerating demand across its U.S. business, particularly in commercial operations. The company reported revenue growth of 93% year-over-year (YOY) to $1.935 billion in Q2, driven by strong domestic momentum.
U.S. revenue more than doubled from the prior-year period, reaching $1.573 billion and contributing more than 81% of the company’s total revenue. U.S. commercial operations played a significant role in this performance, with revenue climbing 149% YOY and 28% sequentially to $764 million. The segment's sequential increase reflects the continued strength of customer demand.
Palantir’s contract wins also point to a favorable demand environment. During Q2, total commercial contract value (TCV) rose 118% YOY to $2.337 billion, reflecting growing interest in the company’s AI platform. U.S. commercial TCV surged 153% YOY to $2.132 billion. Meanwhile, trailing 12-month U.S. commercial TCV rose 117% to $5.964 billion. These gains suggest solid growth ahead.
Palantir is expanding its customer base while deepening relationships with existing accounts. The company reported 653 U.S. commercial customers at quarter-end, up 35% YOY and 6% from the previous quarter. This growth indicates that its commercial footprint is widening as more businesses adopt its platform.
Spending among major customers indicates increasing engagement as well. Revenue generated from Palantir’s 20 largest customers over the trailing 12 months rose 67% YOY, averaging at approximately $124 million per customer. This trend suggests that existing enterprise customers are increasingly driving the company’s overall growth.
Beyond commercial adoption, the government business continues to support Palantir’s expansion. U.S. government revenue increased 90% YOY and 18% sequentially to $809 million, highlighting the segment's strength alongside growing demand from commercial customers. Solid momentum across both businesses positions Palantir to deliver strong financials in the coming quarters.
Palantir’s forward-looking contract metrics indicate strong growth ahead. Total remaining deal value reached $13.1 billion at the end of Q2, up 83% YOY and 11% sequentially. Remaining performance obligations (RPO) also rose 103% YOY to $4.9 billion, up 10% from the prior quarter.
Management raised the company's guidance, further strengthening the investment case. Palantir now expects full-year U.S. commercial revenue to grow at least 134% YOY to $3.424 billion. The company also raised the midpoint of its fiscal 2026 revenue guidance to $8.154 billion, implying about 82% YOY growth. This compares with its previous revenue guidance range of $7.65 billion to $7.66 billion.
Overall, Palantir’s accelerating U.S. commercial revenue, expanding customer base, rising contract values, and improved guidance point to a strong underlying growth trajectory, which could power PLTR stock higher.
Palantir Stock Is Poised for Further Gains
Palantir’s upward momentum is supported by robust growth in its U.S. commercial business, increasing contract values, a growing customer base, and an improved full-year outlook. Revenue growth is likely to remain strong, while the expanding value of remaining contracts signals healthy future demand. Continued enterprise adoption of its AI platform and resilient government demand will drive further earnings growth, supporting additional upside in PLTR stock.
Despite these favorable growth prospects, Palantir’s premium valuation remains a key risk for investors. Nevertheless, a pullback could present an attractive entry point.
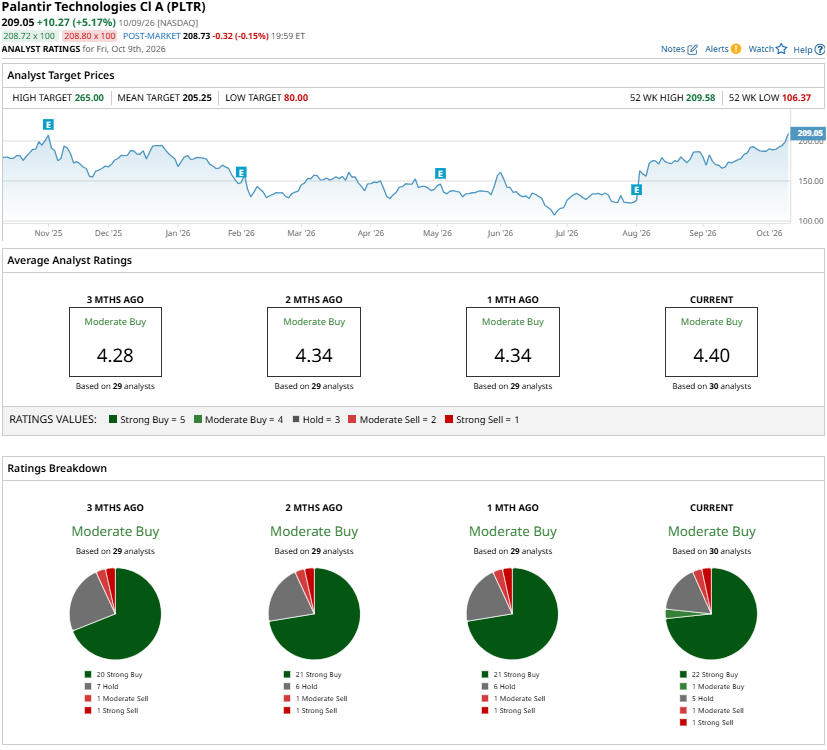
Wall Street analysts remain cautiously positive on Palantir stock with a consensus “Moderate Buy” rating. PLTR stock currently trades near its average price target, while the highest price target of $265 indicates potential upside of about 28% from current levels.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.