
What Ola Electric Mobility Holders Got Wrong Before The Slide
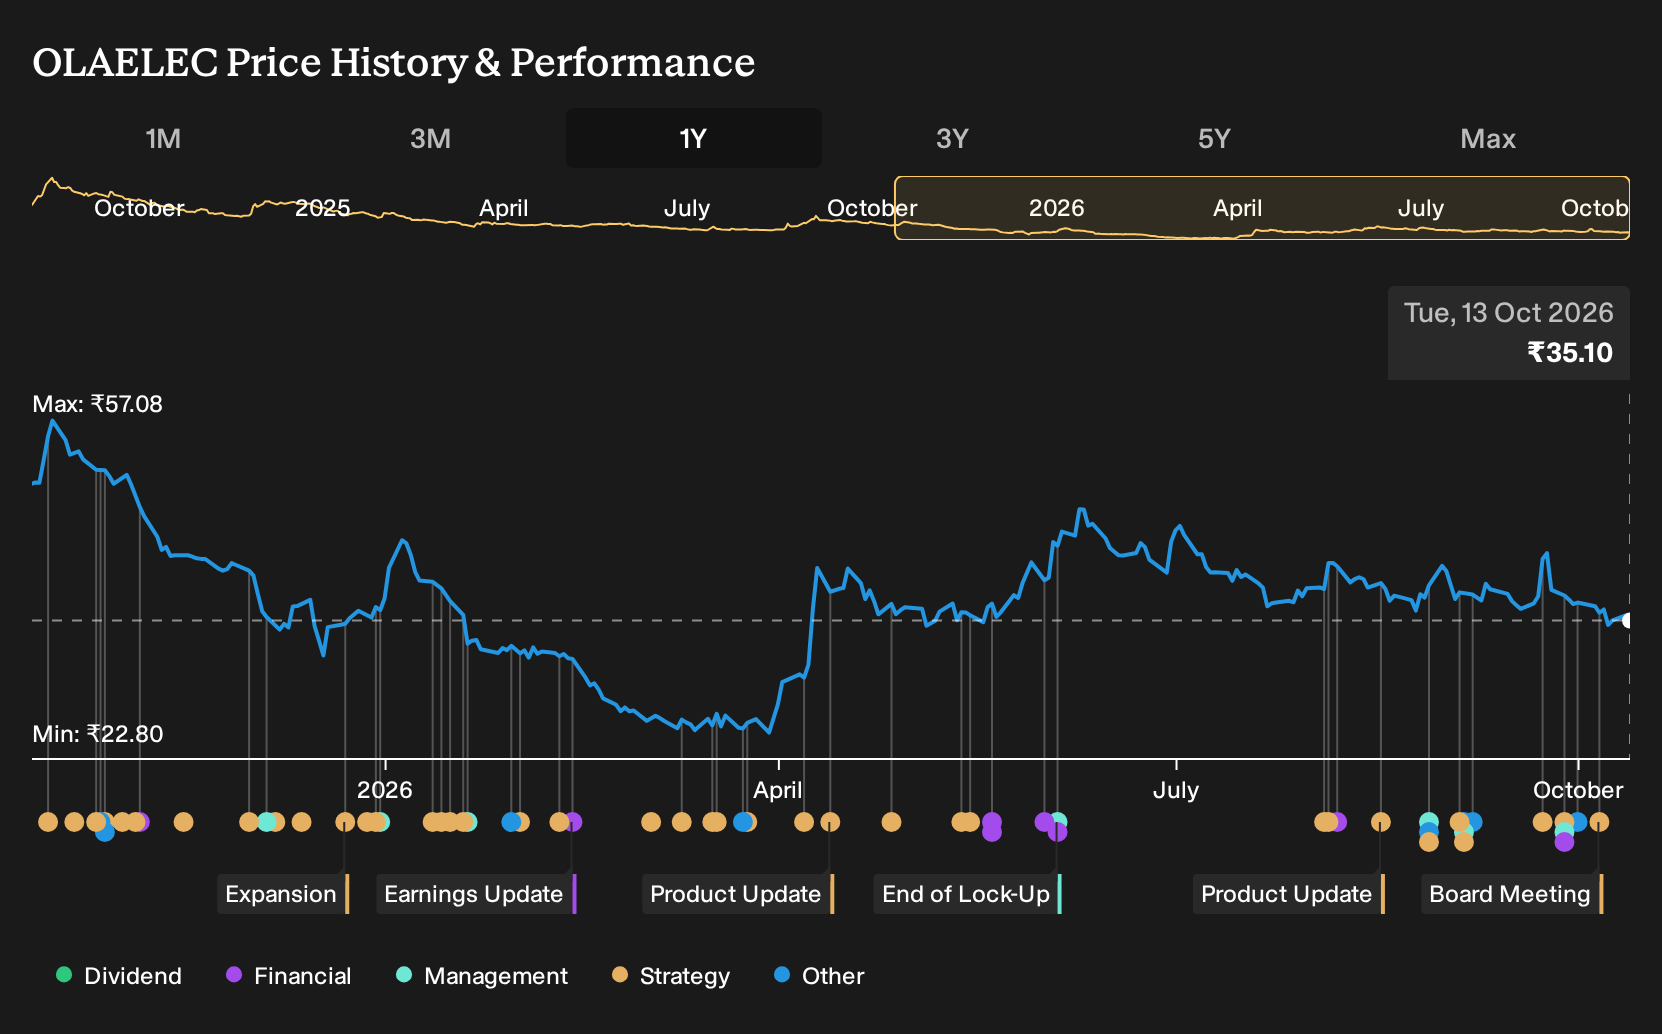
If you had decided to sidestep Ola Electric Mobility when bullish and bearish analyst targets were pulling in opposite directions, your account would look different today. Holding Ola Electric Mobility over the past year would have meant a 30.1% loss, including dividends. With Q1 2027 revenue of ₹4,550m and a deeper net margin loss than Q1 2026 now on record, which assumption from those 2025 forecasts most clearly signalled how fragile the thesis already was?
If the move has made Ola Electric Mobility harder to judge, start where the gap is still open and scan 181 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Ola Electric Mobility
The shares cost ₹50.27 at the start of the period, and Ola Electric Mobility sat between two sharply different stories that both looked plausible on August 2025 research.
The bullish narrative pointed to a Fair Value of ₹72, a price implied by optimistic assumptions that revenue could climb 45.3% a year and profit margin could move from a loss to 9.9% within a 3 year window.
The bearish case anchored to a Fair Value of ₹30, arguing that raw material volatility and gigafactory execution risk might hold revenue growth nearer 13.1% with the same 9.9% margin assumption and a 3 year timeframe.
What The Results Put To The Test For Ola Electric Mobility
The clearest datapoint was Ola Electric Mobility’s Q1 2027 numbers. Revenue fell to ₹4,550m from ₹8,280m in Q1 2026 while the reported loss narrowed from ₹4,280m to ₹3,360m and net margin slipped from a 51.7% loss to a 73.8% loss. That combination of lower sales and a deeper margin loss challenged the bullish profitability path and lent more weight to the cautious case.
The hinge assumption was rapid improvement in net margin. For any other electric vehicle stock, you would now track not just revenue trends but also the reported net margin line every quarter to see whether it is actually moving toward the level used in the original forecast.
What Today's Ola Electric Mobility Price Already Assumes
Ola Electric Mobility now trades at ₹35.1, and this Narrative’s Fair Value sits below that level based on its own framework rather than an objective line in the sand.
The argument focuses on whether execution, service quality and supply chain fixes can stick. A buyer today has to judge if lingering parts and service risks are already fully reflected in the lower price.
"The current valuation implies that Ola Electric Mobility will justify a higher share price than today by delivering on industry leading gross margins, scaling its 6 GWh Gigafactory and converting the installed base into sizeable service and energy storage cash flows."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 24% below our estimate - targets new boutiques and a fresh mobile app to deepen customer engagement.
- Company 2 - 35% below our estimate - grows fee income as asset owners outsource infrastructure capital and portfolio management.
- Company 3 - 44% below our estimate - adds flagship stores and digital channels converting urban traffic into design-led sales.
Those are three of them. See the full list of 203 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com