
3 Data Center Infrastructure Stocks Worth Watching As AI Capex Builds
AI chips grab the headlines, but the quieter backbone is the data center plumbing that keeps all that silicon powered, cooled and online. As Microsoft talks up its Maia 300 plans and big tech races to build custom AI hardware, real money still flows into the physical gear that makes those racks usable. This article walks through three stocks linked to that build out and explains how the latest AI capex signals could matter for your portfolio decisions.
The three stocks covered below are just a starting sample, and the full screen surfaced 25 more companies with equally compelling data center infrastructure stories that are not unpacked in this article.
If you want to identify and analyze the highest conviction beneficiaries of AI hyperscaler capex, go straight to the Global Data Center Infrastructure Beneficiaries of AI Hyperscaler Capex screener.
Shenzhen KSTAR Science and Technology (SZSE:002518)
Shenzhen KSTAR Science and Technology builds uninterruptible power supplies, data center cooling and modular facilities that plug directly into the data center infrastructure theme. The data center industry segment generates about CN¥3.4b in revenue, with the new energy unit adding roughly CN¥2.3b. The business has a market value of around CN¥18.3b.
Shenzhen KSTAR Science and Technology provides focused exposure to the hardware that keeps AI data centers running, from UPS systems to modular server rooms, at a time when hyperscalers are signaling ongoing AI-heavy capital expenditures. Interest in this stock centers on how one pressure within its funding structure may affect future flexibility on pricing and capacity.
That funding pressure is exactly why you might want the 5 key rewards and 1 important warning sign, before pricing power or capacity constraints start to bite.
Xi'an Sinofuse Electric (SZSE:301031)
Xi'an Sinofuse Electric supplies fuses and related protection gear used in data center power distribution, as well as in new energy vehicles, storage and renewable power systems. The business has a market value of about CN¥12.3b.
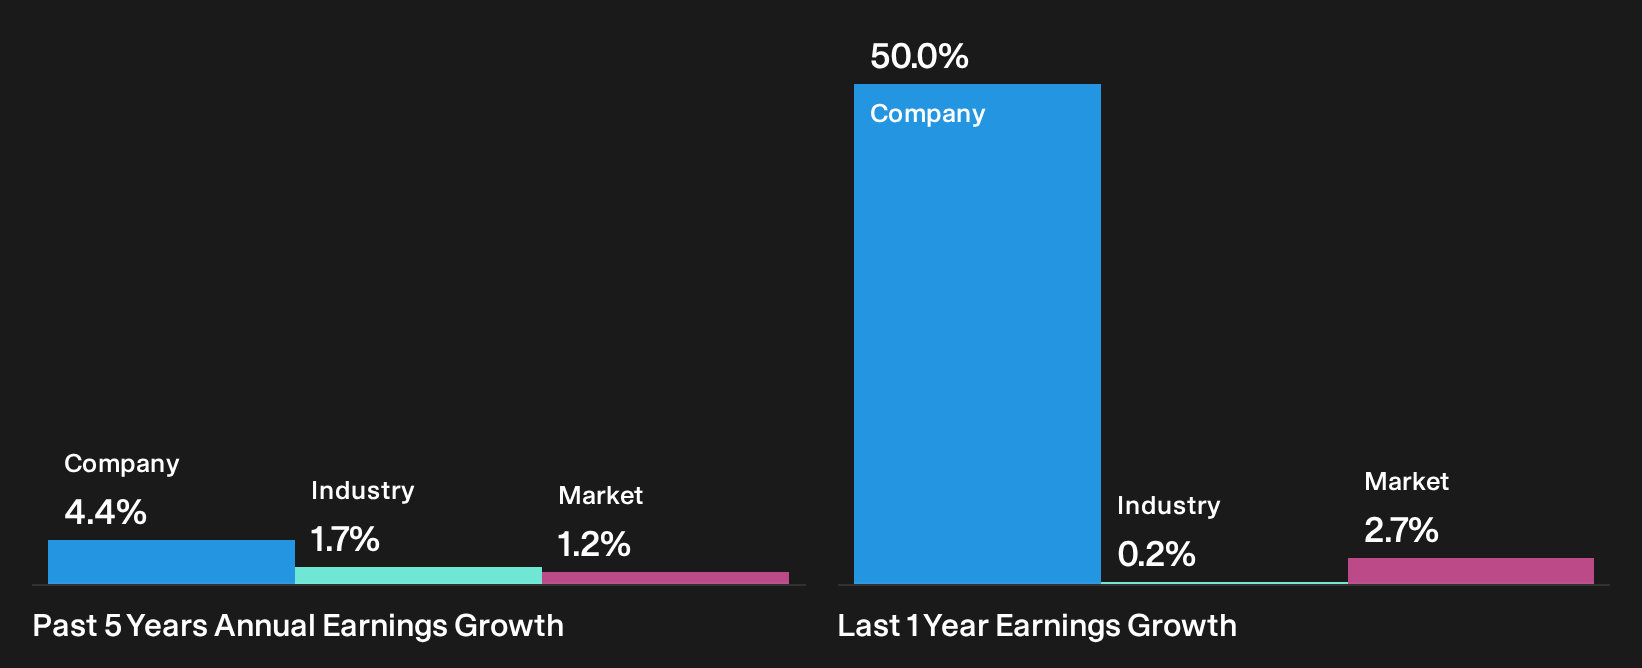
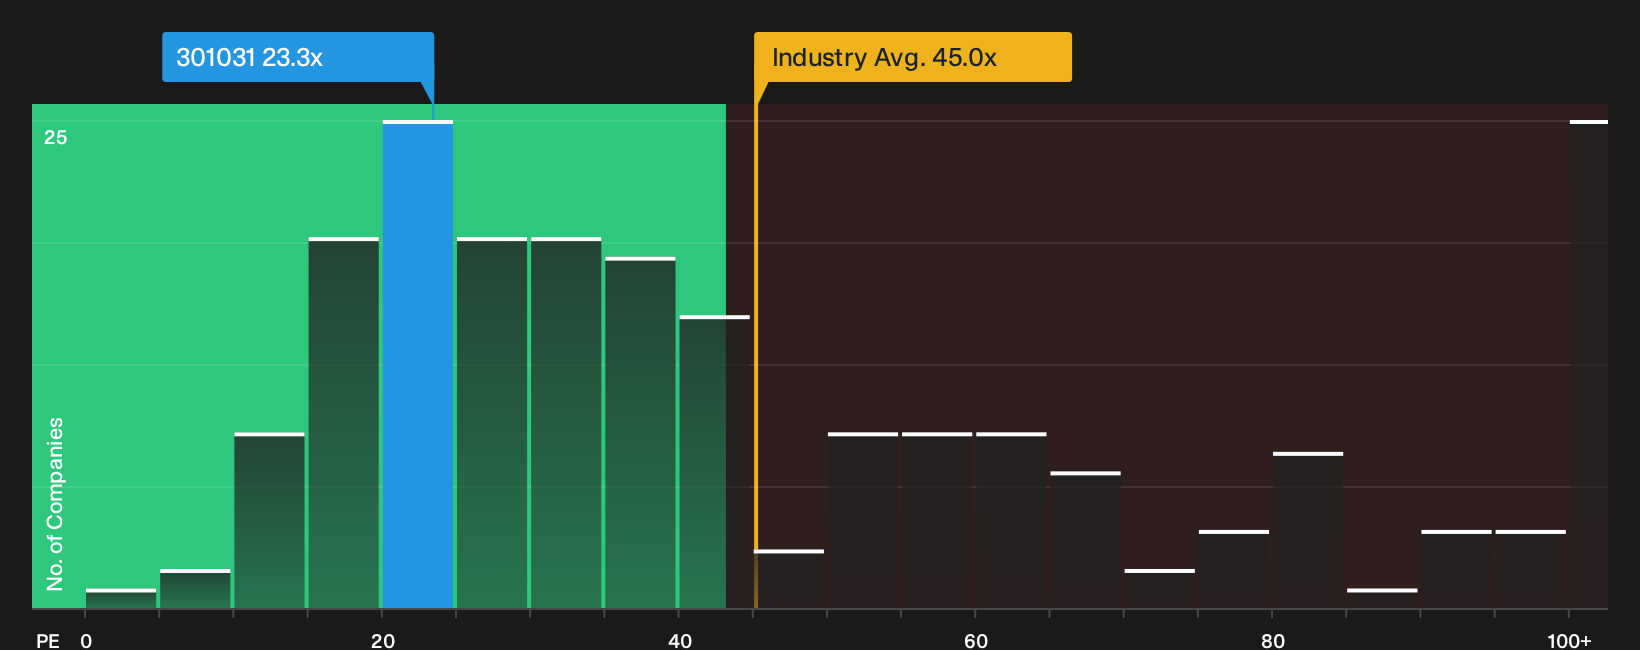
Xi'an Sinofuse Electric is directly involved in the AI data center build out because its fuses and sensors help protect the heavy power flows feeding racks of accelerators. Revenue and earnings are growing strongly, profitability is high, and valuation multiples sit below the broader China market, although the heavy reliance on external borrowing means a single shift in funding conditions could matter significantly for future returns.
That funding sensitivity is exactly why the 5 key rewards and 1 important major warning sign could be worth your time before sentiment decouples from the balance sheet story.
Wasion Holdings (SEHK:3393)
Wasion Holdings plugs into the AI data center theme through its energy metering and efficiency systems that help heavy power users keep electricity use under control. The business is big enough to matter for the screen and broad enough to give you multiple ways to think about that exposure.
Wasion Holdings runs three main businesses tied to energy infrastructure, with smart grid solutions generating about CN¥3.8b, digital energy services about CN¥4.7b and AI integrated efficiency offerings roughly CN¥2.7b, and the stock carries a market value around HK$13.6b.
"Ongoing modernization and digitalization of power grids worldwide, including AMI 2.0 replacement cycles in the US and Europe, and new policy mandates for decarbonization and grid transformation in China, put Wasion in a favorable position to capture long-term demand for advanced metering and grid-automation products, directly supporting revenue and earnings growth."
The real swing factor is how one pressure on future profitability plays out if AI driven power demand and competition do not move in lockstep.
If that profitability pressure matters to you, read the full narrative for Wasion Holdings to see how Wasion Holdings could still turn accelerating grid digitalization into outsized upside.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. The best breakouts often gain momentum before most investors notice, then the data goes stale fast. Scan these under the radar lists now and get in early.
- Hunt for potential breakout small caps where AI is more than a buzzword by scanning 149 AI small caps that already have real businesses behind the story.
- Target resilient income ideas by reviewing the 219 dividend fortresses that blend high yields with balance sheets aimed at keeping payouts from dropping when conditions tighten.
- Spot underfollowed operators before momentum catches them by checking the 620 high quality undiscovered gems that screen for quality fundamentals while attention is still limited.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com