
Earnings Preview: What To Expect From EMCOR Group’s Report
Headquartered in Norwalk, Connecticut, EMCOR Group, Inc. (EME) is a leading provider of electrical and mechanical construction, building services, and industrial infrastructure solutions. Incorporated in 1987, the Fortune 500 company helps businesses build, maintain, and upgrade critical infrastructure, from electrical power distribution and lighting systems to heating, ventilation, air conditioning (HVAC), plumbing, fire protection, and security systems. Its expertise also extends to low-voltage networks, voice and data communications, and industrial facilities.
As a member of the S&P 500, EMCOR operates at the intersection of construction, energy infrastructure, and facility management. Boasting a market capitalization of approximately $34.4 billion, the company is positioned to benefit from demand for complex infrastructure projects, including data centers and industrial facilities.
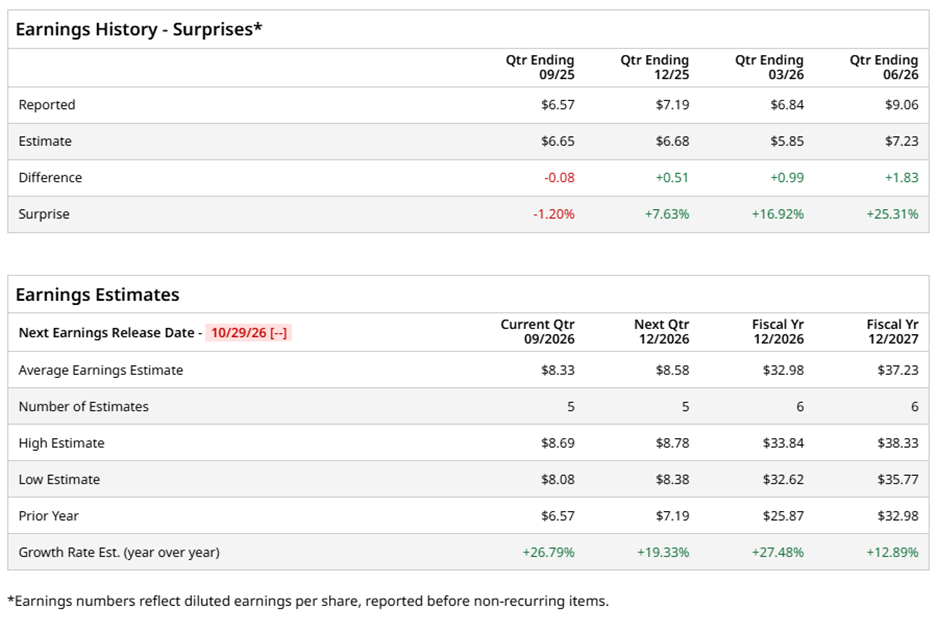
The leading provider of electrical and mechanical construction and facilities services is expected to announce its fiscal third-quarter earnings for 2026 soon. Ahead of the event, analysts expect EMCOR Group to report a profit of $8.33 per share on a diluted basis, up 26.8% from $6.57 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters, while missing the forecast on one other occasion.
For fiscal 2026, analysts expect EMCOR Group’s EPS to be $32.98, up 27.5% from $25.87 in fiscal 2025. Its EPS is expected to rise another 12.9% year over year (YOY) to $37.23 in fiscal 2027.
EME stock has surged 17.4% over the past 52 weeks, but underperformed the S&P 500 Index’s ($SPX) 19.2% gains during this period. On the contrary, it outperformed the State Street Industrial Select Sector SPDR ETF’s (XLI) 12.8% gains over the same time frame.
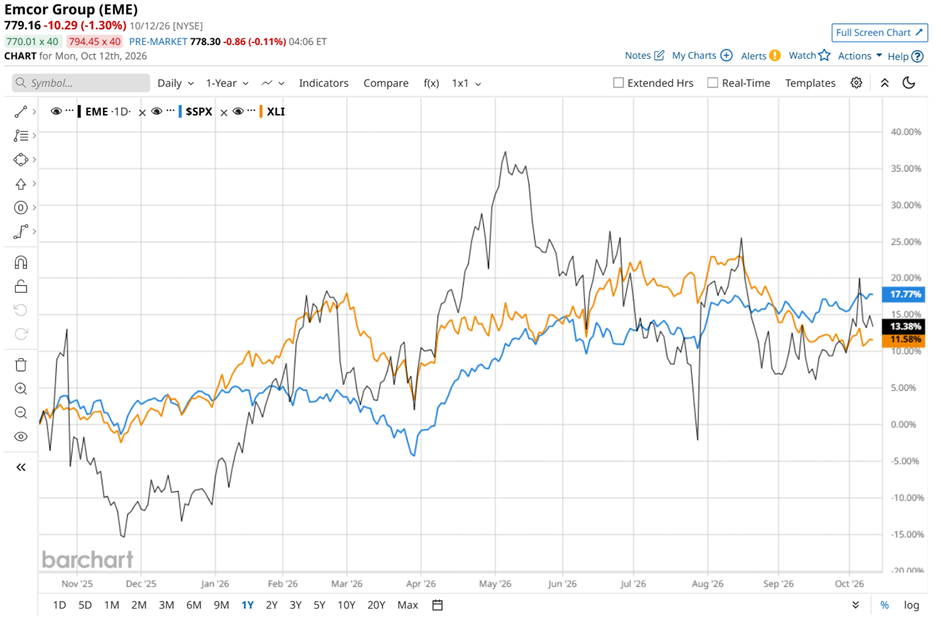
EME stock has been having quite a year, and if you have been watching the stock, you know this is not just another construction company story. Sure, it has underperformed the broader S&P 500 over the past year, but it has outpaced its sector peers. In 2026, the stock has gained 27.4% YTD, beating both the S&P 500 and the XLI. Not bad for a company that makes its money building the very infrastructure much of the AI boom depends on.
A big reason behind that run has been EMCOR’s ability to turn demand into actual dollars. Data centers, electrical infrastructure, institutional projects, and industrial facilities have all been keeping its crews busy. Its Electrical and Mechanical Construction businesses have benefited from rising network and communications activity, while Building Services has gained from HVAC retrofits and controls. Industrial Services has also found support from turnaround work and petrochemical activity.
Then came July 30, when EME stock surged 19.3% after the company delivered a blowout second-quarter report. Revenue jumped 19.8% YOY to $5.2 billion, while EPS climbed 34.8% annually to $9.06, beating Wall Street’s expectations. Operating income rose 31.8% to $547.3 million, and operating margin expanded to 10.6% from 9.6% a year earlier. Clearly, investors liked what they saw.
The order book made the story even more compelling. EMCOR’s remaining performance obligations (RPOs) hit a record $17.14 billion at the end of Q2, up 44% YOY and 10% sequentially. Better yet, 95% of that increase came organically, suggesting demand is doing plenty of the heavy lifting without relying entirely on acquisitions. Strong bookings across data centers, healthcare, water and wastewater, and institutional markets also give the company better visibility into future work.
Management is feeling confident, too, forecasting full-year 2026 EPS of $32 to $33.25 and revenue between $20 billion and $20.5 billion. Acquisitions are adding capabilities, while the company’s balance sheet gives it room to pursue opportunities.
More recently, EME climbed 5.8% on Oct. 6 as enthusiasm around AI infrastructure spending, power systems, and grid upgrades lifted related industrial stocks. With defense modernization adding another potential demand driver, EMCOR has plenty working in its favor.
Wall Street is still firmly in EMCOR’s corner, giving EME stock an overall “Strong Buy” rating. Of the 11 analysts covering the stock, eight recommend a “Strong Buy,” while the remaining three advise a “Hold.” EME’s average analyst price target is $1,012.62, indicating a potential upside of 30% from the current levels.
On the date of publication, Sristi Suman Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.