
Is MaxLinear (MXL) Fairly Valued Following Its Topaz And MaxAI 2.0 Showcase?
MaxLinear (MXL) has put its Topaz platform and MaxAI 2.0 front and center, using Network X 2026 to show how AI-ready broadband gateways could reshape edge computing and subscriber networks.
Recent pricing tells a mixed story for MaxLinear. The share price is US$88.99 after falling 7.46% over the past day and 15.64% over the last week, although the 30 day share price return of 19.34% and very large year to date gain of 380.77% signal powerful longer term momentum. Over a wider horizon, total shareholder return of 464.66% over one year and 316.23% over three years suggests the market has already reacted strongly to the broader AI and broadband narrative around launches such as Topaz and MaxAI 2.0, even as short term swings hint at changing views on execution risk and valuation.
Seize the momentum around MaxLinear's AI-ready gateways and compare it with other potential breakouts across 92 AI infrastructure stocks.After a near 5x one-year total return and with a share price slightly below analyst targets, MaxLinear now sits between a fair value discount narrative and a market that is already bracing for potential setbacks.
Most Popular Narrative: 6% Undervalued
Against a fair value estimate of $94.55, MaxLinear’s last close at $88.99 leaves a modest gap that recent AI optical enthusiasm is trying to fill.
Accelerating demand for high-speed data center optical interconnects and next-generation PAM4 DSP solutions (Keystone and Rushmore), supported by robust design win momentum with major module makers and hyperscale customers, positions MaxLinear to capture a significant share of growing global data/AI infrastructure spend, likely driving meaningful revenue growth from late 2025 through 2027.
See why 18 investors see MaxLinear as 6% undervalued.
Result: Fair Value of $94.55 (UNDERVALUED)
Still, concentration in maturing broadband markets and the risk that AI optical demand proves bumpier than expected could quickly challenge the MaxLinear repricing story.
Find out about the key risks to this MaxLinear narrative.
Another View: MaxLinear Through A Sales Multiple Lens
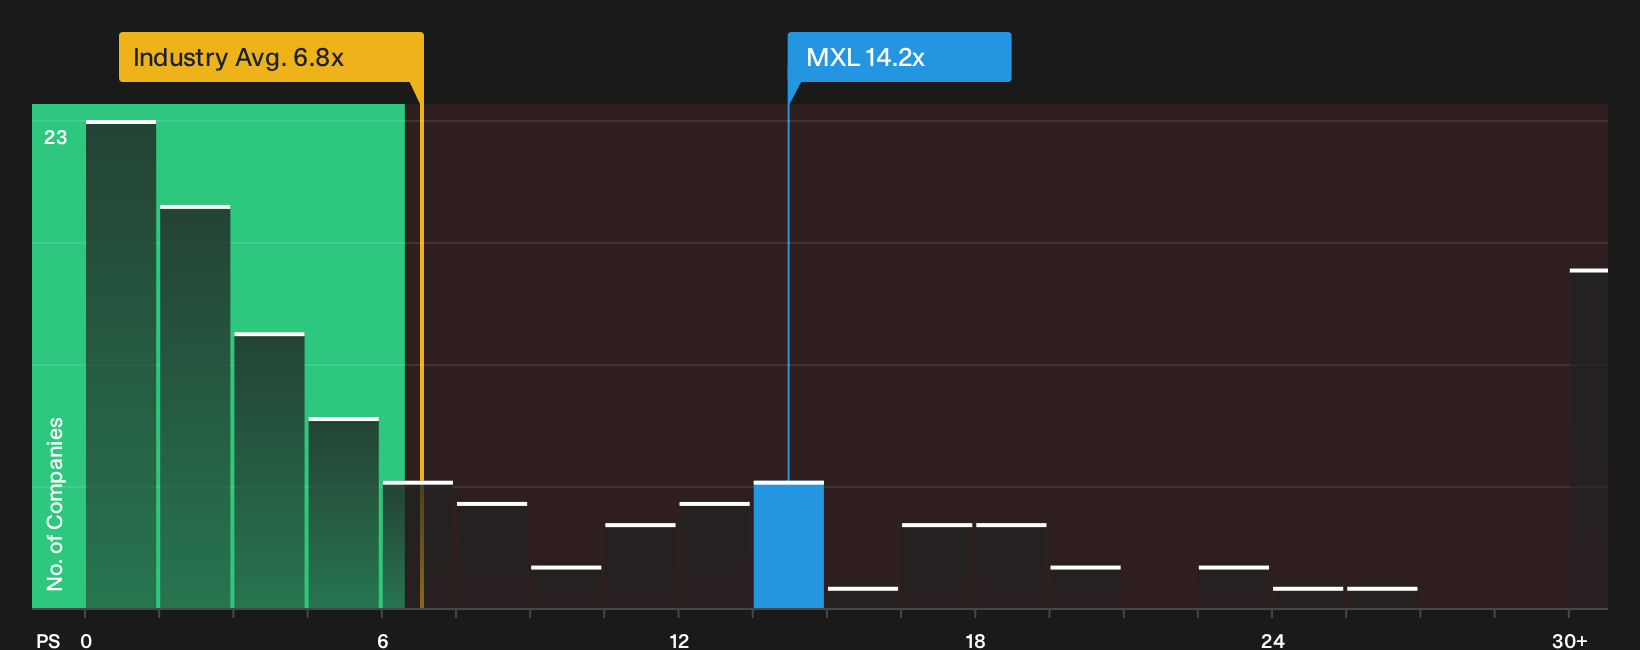
Fair value work built around future earnings paints MaxLinear as roughly 6% undervalued, yet the price tag on current sales tells a different story. At a P/S of 14.2x, the stock trades at more than double the US Semiconductor average of 6.8x and above the peer group at 11.2x, while the fair ratio sits lower again at 13.5x. That gap implies the market is already paying a premium for MaxLinear’s AI and optical story, so the real question is whether you see that premium as justified resilience or fragile optimism.
For a closer look at how this pricing premium stacks up against fundamentals, check the valuation breakdown through See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
The story around MaxLinear is split between opportunity and risk, and that is exactly why your own judgment matters most right now. Weigh the upside potential against the pressure points, then stress test your stance by walking through 1 key reward and 2 important warning signs.
Looking for more MaxLinear investment ideas?
Do not stop with MaxLinear alone. Use the Simply Wall Street Screener to spot other opportunities that sharpen your watchlist and challenge your assumptions before the next move.
- Target resilient balance sheets and steady fundamentals by checking the list of solid balance sheet and fundamentals (25 results) that filters for financially grounded businesses.
- Hunt for potential mispricing by scanning the 29 high quality undervalued stocks that highlights companies where quality and valuation sit out of sync.
- Pursue income-focused opportunities by reviewing the 8 dividend fortresses that zeroes in on yields starting at 5% with an emphasis on staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com