
US stock outlook | Futures of the three major stock indexes have mixed ups and downs, and the wave of chip stock sell-offs continues, bank earnings season begins
Pre-market market trends
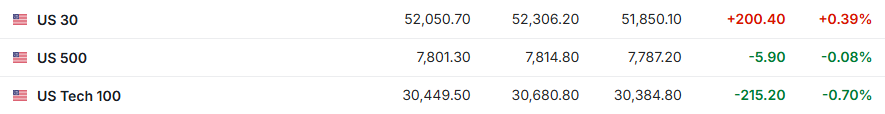
1. Before the US stock market on October 13 (Tuesday), futures for the three major US stock indexes had mixed ups and downs. As of press release, Dow futures were up 0.39%, S&P 500 futures were down 0.08%, and NASDAQ futures were down 0.70%.
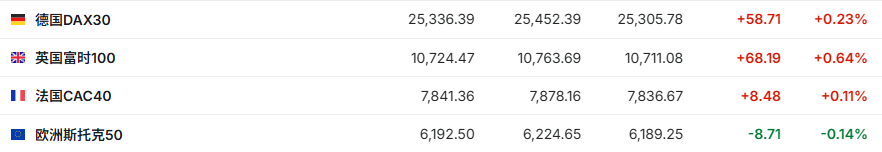
2. As of press release, the German DAX index rose 0.23%, the UK FTSE 100 index rose 0.64%, the French CAC40 index rose 0.11%, and the European Stoxx 50 index fell 0.14%.
3. As of press release, WTI crude oil fell 1.95% to $91.91 per barrel. Brent crude fell 1.74% to $104.79 per barrel.

Market news
The wave of chip stock sell-off continues, and the bank earnings season begins. The sharp decline in memory chip stocks brought the market's doubts about the sustainability of AI narratives to the front. From Seoul to Taipei to Philadelphia, the semiconductor sector is under collective pressure. The Kospi Index plummeted more than 5% on Tuesday, and the Philadelphia Semiconductor Index has fallen more than 7% from this month's high. The core of this round of sell-off is not on the demand side, but on the supply side, the competitive landscape has suddenly changed and the capital chain is tight. Meanwhile, with Wall Street's latest earnings reports being released one after another, major US bank stocks are entering a correction range. The KBW Bank Index has fallen about 12% from its August high, exceeding the 10% technical correction threshold.
Federal Reserve Waller: The sharp rise in US bond yields will help curb demand, and AI investment will drive inflation. Federal Reserve Governor Christopher Waller said that the sharp rise in long-term US Treasury yields is helping to curb demand in interest rate sensitive industries such as housing and automobiles, thus playing a role in tightening monetary policy to a certain extent. Waller said at the Economic Forum held in New Delhi on Tuesday: “Will rising yields have an impact on interest rate sensitive industries such as housing and automobiles? Of course it would.” He pointed out that although this was not the intention of the Federal Reserve, rising yields did “play a certain role.” Waller also said that AI is also driving up prices because the rapid construction of AI infrastructure stimulates demand. Waller is one of many US Federal Reserve officials hoping AI will eventually increase productivity. If AI can increase productivity, the economy is expected to grow stronger without causing excessive inflation. But he said that this return may take years to materialize, while AI-driven price pressure may continue for two to three years.
Is there an opportunity to bottom out after yields soar? Major Wall Street banks such as Goldman Sachs and Damo are optimistic about the prospects for a rebound in US debt. After weeks of sell-off driving US Treasury yields to multi-year highs, Wall Street strategists began to re-examine the investment value of US bonds. Institutions such as Goldman Sachs, Morgan Stanley, and Citi believe that with the sharp rise in US bond yields, the attractiveness of bond valuations is increasing. However, there are still clear differences among the major institutions regarding the future path of the Federal Reserve's interest rate and the timing of a rebound in US debt. Goldman Sachs believes that the credit market is beginning to show signs of pressure, as well as improvements in investors' position structures and market technical risks, may create conditions for a rebound in US Treasury bonds. Citi, on the other hand, favors short-term US bonds. The bank's strategist said that as inflation slows and wage growth weakens, it is unlikely that the Federal Reserve will raise interest rates to a high level in 2023. Morgan Stanley also believes that US bond yields are already attractive, but at the same time, investors are advised to wait for the Federal Reserve's interest rate meeting this month and the US midterm elections before considering entering the market.
Is the signal for the Fed's interest rate cut hidden in Walmart's stock price? This indicator once again sounded the alarm of a recession. According to an analysis by Jim Paulson, the former chief investment strategist at Leuthold Group, Walmart's stock price lagged behind from May to August 2026, but since August, Walmart's stock price has outperformed the S&P Global Luxury Stock Index by about 21%, and Walmart's stock price has also risen about 8% from its low in late August. Paulson believes that this change in relative performance indicates that consumers may be tightening their budgets again, which means that the US economy is losing momentum, and the future economy may weaken or force the Federal Reserve to switch back to easing policies. But if rising energy prices continue to drive up overall inflation, or if corporate investment and consumer demand remains strong, policymakers may continue to maintain an austerity stance. Furthermore, the historical performance of this indicator has attracted market attention. According to Paulson's analysis, the “Walmart recession signal” has clearly risen before the past four recessions, and since 1990, there have been similar changes before every round of the Fed's easing cycle began.
Goldman Sachs put a sharp brake on AI infrastructure financing: the $5 billion AI loan only dared to accept 1.3 billion dollars, and the 11% high interest rate did not dare to fully cover it. Komo and Goldman Sachs have taken a rare step to limit their risk exposure to a $5 billion loan sale to AI startup Volta Infrastructure Holdings Ltd., as investors are demanding higher yields on risky debts associated with the AI boom. The two banks are leading loan issuances for Volta, a newly formed AI cloud company. According to people familiar with the matter, the two banks underwrote a $1.3 billion term loan for Volta, while a $3.7 billion chip loan was not underwritten by the two banks — a move aimed at protecting themselves from potential risks. Volta's debt is being promoted to investors at a yield of around 11%, which is one of the highest borrowing costs in the leveraged loan market, which has become a popular channel for AI financing.
ETF buying is difficult to support the overall situation! Bank of America analysts predict that the price of gold will not hold $4,000 in the next three months? According to a precious metals research report recently released by Wall Street financial giant Bank of America, the agency is inclined to place the $4,000 mark for gold in the next three months under multiple selling stress tests — that is, demand for physical spot gold is weak, gold ETF purchases are difficult to support the market alone, and even some central banks around the world may restart gold sales. The agency's analysts expect it will be difficult for gold to continue to fluctuate above the $4,000 key point in the next three months or so. Bank of America said that in order for gold prices to find a bottom and resume a long-term upward trend, the market needs more clear guidance from the Federal Reserve. Although the Federal Reserve's shift to a dovish monetary policy will be a more important driver for gold, gold may also regain upward momentum if market concerns about currency value being diluted heat up again.
Individual stock news
J.P. Morgan Chase (JPM.US) Q3 revenue and EPS fell short of expectations, and the decline in fixed income transactions dragged down performance. Financial reports show that J.P. Morgan Chase's Q3 revenue was US$50.97 billion, up 8% year on year, lower than market expectations; adjusted earnings per share of US$5.75 were also lower than market expectations. Net profit was US$15.305 billion, up 6% year over year. Net interest income was $27.1 billion, up 13% year over year. Results that fell short of expectations were mainly dragged down by declining revenue and rising costs from fixed income transactions. Market revenue for the quarter was US$10.3 billion, up 15% year over year. Among them, stock trading revenue was 4.954 billion US dollars, a sharp increase of 49% year on year; fixed income transaction revenue was 5.366 billion US dollars, down 4% year on year, significantly lower than market expectations of about 6 billion US dollars. CEO Dimon said that all business lines performed well. “Huge fiscal deficits, sticky inflation, high asset prices, rising interest rates, and geopolitical conditions” continue to evolve. These forces “may be controlled,” but the company is “prepared for all possible outcomes.” As of press release, J.P. Morgan Chase's US stock rose nearly 1% in the premarket on Tuesday, before falling more than 3%.
The lifting of regulatory restrictions failed to generate strong revenue, and Wells Fargo (WFC.US) Q3 revenue fell short of expectations. According to financial reports, Wells Fargo's Q3 revenue increased 2% year over year to US$21.87 billion, but fell short of market expectations of about US$22.32 billion; GAAP earnings per share were 1.87 US dollars, up 13% year on year, slightly higher than market expectations. Net interest income in Q3 increased 5% to US$12.52 billion; driven by rising loan and investment securities balances, declining interest rate repricing of fixed-interest assets, and market business expansion, this was partly offset by lower returns on floating rate assets and higher costs of interest-bearing commercial deposits. The credit loss provision for the quarter was US$1,029 million, far higher than the US$681 million in the same period last year. It mainly reflects the increase in reserves due to rising balances of industrial and commercial loans and automobile loans, while commercial real estate reserves declined somewhat. Since the Federal Reserve lifted a multi-year regulatory cap on the bank's assets, the bank has been able to deploy more balance sheets, giving it more room to compete for loans. Wells Fargo relies on credit cards and car loans to expand its consumer loan business. As of press release, Wells Fargo shares fell more than 1% before the market on Tuesday.
UnitedHealth (UNHUS) Q3 results surpassed expectations: falling medical claims boosted profits and raised full-year profit guidelines once again. Financial reports show that UnitedHealth's third-quarter revenue fell 0.4% year on year to US$112.694 billion, still higher than market expectations of about US$111 billion; adjusted earnings per share increased 61% year over year to US$4.69, exceeding market expectations. Cost control is the main driver of performance. The medical reimbursement rate for the quarter was 88.4%, better than analysts' expectations of 89.9% and 89.90% for the same period last year. The company attributed this to insurance product design adjustments and new pricing. In terms of guidance, the company raised the adjusted earnings per share guide for the full year of 2026 to at least $20.50 (previously $19.50-$20.00), and the GAAP diluted earnings per share guide to at least $19.50. This is the third time in the year that the company has raised its full-year guidelines. According to LSEG data, analysts previously expected the company's adjusted earnings per share for the full year 2026 of $19.86, and the lower limit of the new guidelines is already higher than the consensus. As of press release, UnitedHealth's US stocks rose more than 1% before the market on Tuesday.
Johnson & Johnson (JNJ.US) Q3 earnings exceeded expectations and raised annual results guidance! The innovative drug business is expanding, and the device business still needs to be improved. Financial reports show that Johnson & Johnson's third-quarter sales increased 5.9% year over year to US$25.4 billion, in line with general market expectations. GAAP net profit plummeted 95.9% year over year to US$210 million. After dilution, earnings per share were only $0.09 ($2.12 in the same period last year), mainly due to one-time pre-tax expenses relating to the proposed settlement of the US$5,519 billion talc lawsuit. Adjusted net profit was US$6.339 million; adjusted earnings per share were US$2.59, exceeding the market's agreed expectations of approximately US$2.53, but fell 7.5% year over year (US$2.80 in the same period last year). Revenue from the innovative drug business increased 7.7% year on year to US$16.757 billion. The new drug sales performance was a highlight; the medical device business was clearly weak, with revenue rising 2.5% year over year to US$8.642 billion, of which overseas performance was basically the same. In terms of guidance, Johnson & Johnson raised the median sales revenue guide for the full year of 2026, from about US$101.1 billion to US$101.2 billion (range of US$1010-101.4 billion), and the adjusted median earnings per share guidance was raised from US$11.04 to US$11.10 (range of 11.05 to 11.15 US dollars), all higher than the agreed market expectations. As of press release, Johnson & Johnson's US stocks fell more than 2% in the premarket on Tuesday, mainly due to poor performance in the medical device business or lukewarm market response.
Apple (AAPL.US) will hold a new smart home product launch on Tuesday. Apple will hold a “Welcome Home” themed event on October 13, local time, focusing on the smart home product line. According to the latest news from well-known journalist Mark Gurman, in addition to HomeView, the much-publicized smart home hub, the new Apple TV 4K and the new HomePod Mini will also be released on the same stage. The latter two products are expected to go on sale on October 30, while HomeView is expected to launch in mid-November. Although many people in the industry expect that some upgrades to Apple TV and HomePod are only modest performance improvements, chip iterations will actually bring unprecedented new capabilities to Apple's smart home product line. The devices are expected to have better connectivity and further integrate Siri's artificial intelligence (AI) capabilities.
Key economic data and event forecasts
The next day at 04:00 Beijing time 2028 FOMC voting committee and Boston Federal Reserve Chairman Collins delivered a speech
Performance Forecast
Wednesday pre-market: ASML.US (ASML.US), Bank of America (BAC.US), Morgan Stanley (MS.US), BlackRock (BLK.US)