
Ocular Therapeutix (OCUL) Heads To AAO With Axpaxli Hopes While Valuation Debate Builds
Ocular Therapeutix (OCUL) is stepping onto a busy conference stage in New Orleans, with back to back presentations at Eyecelerator @ AAO 2026, Innovate Retina, and AAO Retina Subspeciality Day.
Ocular Therapeutix shares trade at US$7.56, after a steep 30 day share price return decline of 27.93% and a year to date share price return loss of 36.04%. However, the three year total shareholder return is up a little more than 3x, which hints that recent weakness may reflect shifting risk perceptions as much as changing views on long term potential.
Scan other hand-picked biotech plays showing similar conference catalysts and clinical milestones through the 20 high quality undiscovered gems that might be flying under most investors' radar.
Ocular Therapeutix is pitching a growing retinal pipeline and US$52.1 million in annual revenue into a share price that has dropped sharply this year. Are you paying for a strong platform or a sagging sentiment story?
Most Popular Narrative: 72% Undervalued
Against a fair value estimate of about $27.09, Ocular Therapeutix at $7.56 reflects a wide gap that the prevailing narrative ties directly to Axpaxli’s retinal potential and execution risk.
The anticipated approval of AXPAXLI, potentially the first wet AMD product with a superiority label and longer dosing intervals (every 6 to 12 months), may allow Ocular Therapeutix to capture significant market share in a rapidly growing population of elderly patients with retinal disease, unlocking large revenue growth opportunities as the global prevalence of ophthalmic disorders increases.
See why 10 investors see Ocular Therapeutix as 72% undervalued.
Result: Fair Value of $27.09 (UNDERVALUED)
Still, Axpaxli carries heavy single drug risk, and any trial setback or weaker than expected real world uptake could quickly puncture the Ocular Therapeutix undervaluation story.
Find out about the key risks to this Ocular Therapeutix narrative.
Another View: Ocular Therapeutix And The Price To Sales Gap
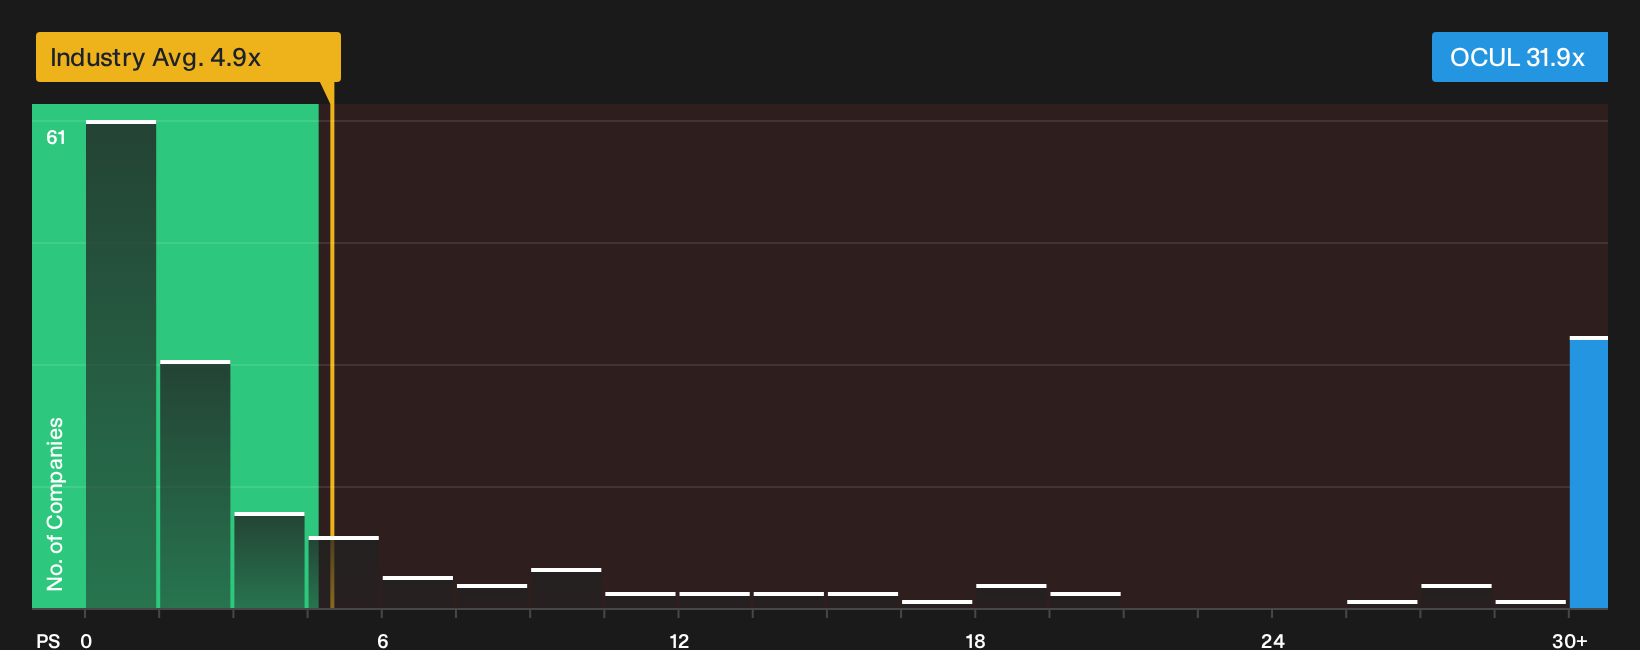
The story looks very different once you shift from fair value models to simple sales multiples. Ocular Therapeutix trades on a P/S ratio of 31.9x, which is far above the US Pharmaceuticals industry at 4.9x and the peer group at 5.5x, and even further from its fair ratio of 0.1x. That kind of gap concentrates valuation risk if Axpaxli or the broader pipeline do not live up to high expectations.
Our preferred multiple work points in the opposite direction to the fair value estimate. This puts the burden on you to decide which framework better matches your view of Axpaxli’s real commercial potential. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling pulled between the bullish fair value story and the rich P/S multiple on Ocular Therapeutix? Act while sentiment is still unsettled and pressure test the data for yourself, starting with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ocular Therapeutix?
Do not stop with a single ticker when the broader market could hold better fits for your goals and risk comfort.
- Target higher potential upside by scanning a curated pool of smaller, higher risk opportunities through the 11 elite penny stocks with strong financials.
- Prioritize value by filtering for quality companies with lower valuation markers using the 29 high quality undervalued stocks.
- Stack resilience into your watchlist by screening for businesses with stronger finances via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com