
Alibaba (BABA) Stock Still Looks Undervalued After Its 40% Run
Alibaba Group Holding has seen a mix of sharp setbacks and longer term gains in its share price, which raises a simple question for anyone looking at the ticker today. Is the current valuation supported by what the business is earning right now and what those earnings can realistically fund in the years ahead?
- Over the past 3 years the stock has returned 39.5%, which puts real weight on whether those gains line up with the company’s earnings power.
- Management’s push to grow cloud revenue, AI infrastructure and related services can shift expectations for future profitability, cash generation and the earnings base investors are effectively paying for at today’s price.
- Your read on Alibaba Group Holding is one view; the desks covering it have another. See what analysts think Alibaba Group Holding's shares could be worth.
The issue now is whether Alibaba’s current share price is justified by its earnings when you strip the story back to what the business is actually making today.
If you are comparing Alibaba Group Holding's AI and cloud push with other opportunities, a focused stock screen is a useful second lens, starting with 92 AI infrastructure stocks.
Is Alibaba Group Holding a Bargain on Earnings?
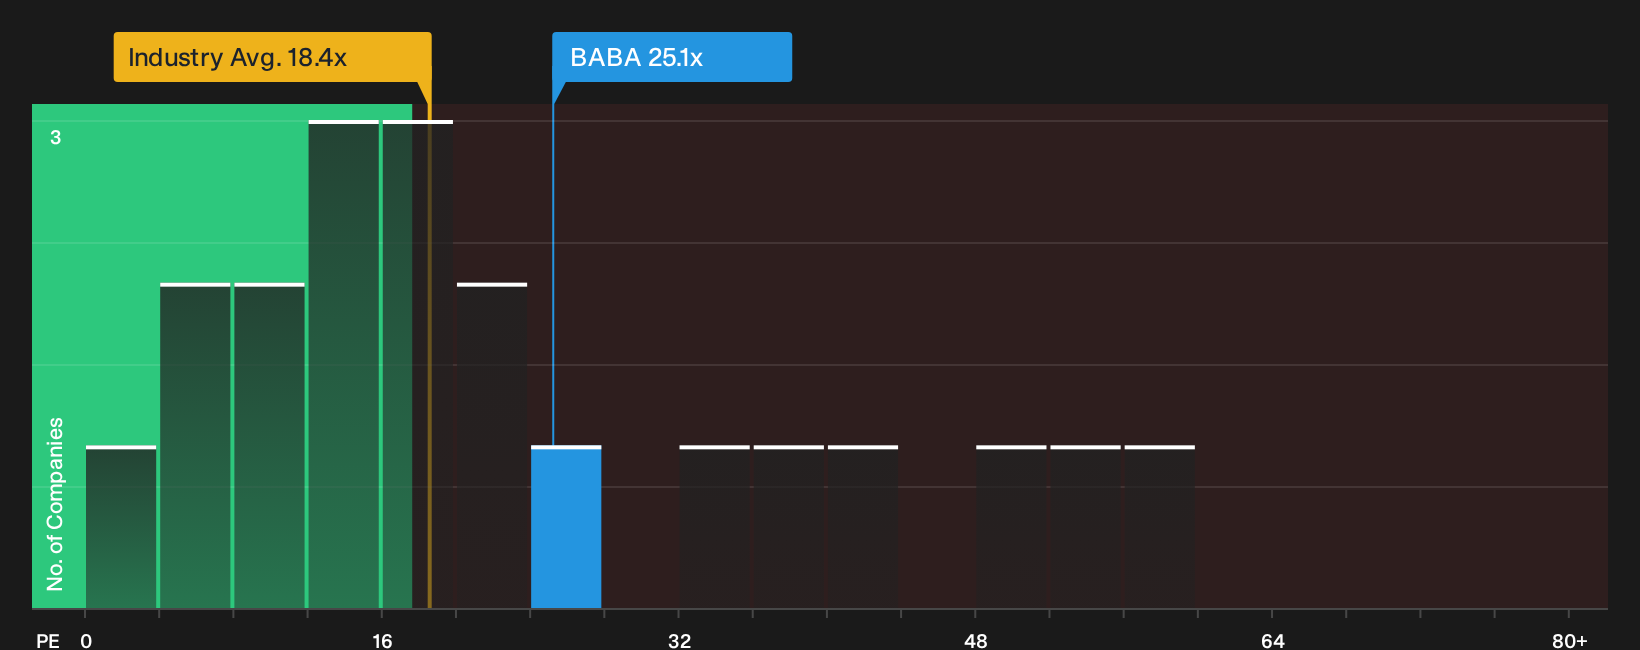
The P/E ratio is a useful way to frame Alibaba Group Holding because earnings still anchor how investors think about the business. Right now the stock trades on about 25.1x earnings, which is below the wider peer group on roughly 29.7x and above the broader Multiline Retail sector at about 18.4x. Because that figure sits under what a tailored model suggests would be typical for Alibaba given its growth profile, margins and risk mix, the multiple appears undervalued on this lens.
Because the recent AI and cloud headlines have put Alibaba in the same conversations as large global platforms, the gap to peers matters. Despite the attention around Qwen AI models, new data centers and a push into next generation computing, the current P/E still prices Alibaba at a discount to similar companies that investors often compare it against, which leaves the earnings multiple looking comparatively restrained at today’s share price. Explore the numbers behind Alibaba Group Holding's P/E valuation.
The Alibaba Group Holding Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the Alibaba Group Holding valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than it is today, and they sit on the platform's Community page. Rather than leaning on a single P/E or one model output, each scenario lays out the assumptions behind its fair value view so you can line those expectations up with Alibaba Group Holding's reported results over time.
One of the top community narratives on Alibaba Group Holding: 54% undervalued
"The thesis is that investors today are buying a leading e-commerce platform, one of the world's largest cloud businesses, a major AI player…"
Discover why this Narrative puts Alibaba Group Holding at 54% undervalued.
An unanswered question on Alibaba Group Holding that matters before you move on
Valuation only tells part of Alibaba Group Holding's story. Separate checks have raised specific concerns that could change how you view the risk side of the equation once you look at them closely. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com