
Boeing (BA) Stock Looks Reasonable Despite Its 17% Slide
Boeing has had a tough run in 2026, and with the share price under pressure, the live question for investors is whether today's valuation can still be explained by the earnings power behind the stock.
- The share price is down 16.8% year to date, which puts fresh focus on whether the current level already reflects the business's earning capacity.
- New multi billion dollar defense work and a reported order backlog of US$715b may support expectations for future profit streams, while high leverage and capital constraints keep attention on how much of that demand can translate into sustainable earnings.
- There is a second opinion on Boeing worth weighing. See what analysts think Boeing's shares could be worth.
The stock's next move may depend on whether Boeing's recent share price still lines up with what its earnings justify.
If you want a wider watchlist while you assess Boeing's earnings story, a focused stock screen built around solid balance sheet and fundamentals stocks screener (25 results) can give you more candidates to research next.
Where Does Boeing Sit on Earnings?
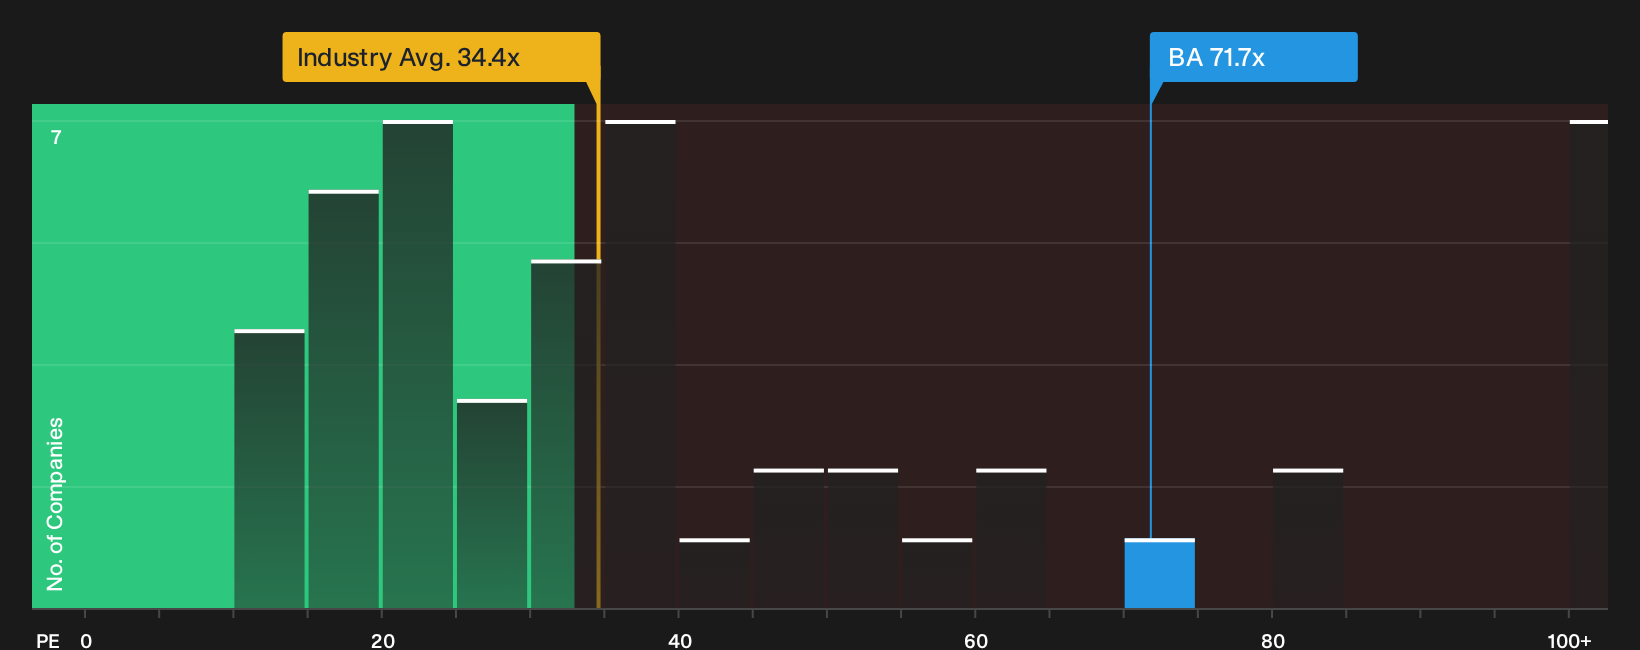
The P/E ratio suits Boeing because earnings are the core way many investors think about paying for its recovery story. Right now the stock trades on a P/E of 71.7x, which is more than double the Aerospace & Defense sector average of 34.4x and also well above the peer group at 29.6x. That points to a market that is already attaching a rich price tag to each dollar of current earnings.
On this framework, the tailored fair P/E that reflects Boeing's mix of growth potential, profitability profile, size and risk sits close to the current multiple, so the valuation screens about right rather than appearing clearly cheap or expensive on earnings alone. Because the recent multi billion dollar F/A XX fighter contract and the US$715b backlog are already well flagged, the current P/E suggests investors are largely pricing that work into expectations rather than treating it as a bonus. Explore the numbers behind Boeing's P/E valuation.
The Boeing Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Boeing valuation puzzle leaves off, spelling out what kind of future growth, profitability and earnings profile would need to play out for the stock to be worth much more or much less than today’s price on the market. Instead of centering on a single multiple or model output, each Narrative lays out the key assumptions behind its view of fair value so you can track those against Boeing's actual results as they arrive on Simply Wall St's Community page.
Community views on Boeing are split between a recovery that still has room to run and a rebound that already prices in a lot of good news.
Bull case: 37% undervalued
"Boeing's vast $522 billion commercial backlog, with 5,900 aircraft sold firm into the next decade, positions the company to disproportionately benefit from the expected doubling of global air travel demand by 2040..."
Discover why this Narrative puts Boeing at 37% undervalued.
Bear case: 18% overvalued
"What today's price requires At the same 10% discount, justifying $230.63 needs roughly 9.3% revenue growth, a 10% net margin, and a 25x exit multiple..."
Explore why this Narrative puts Boeing at 18% overvalued.
The Boeing share price is only one piece of the picture
What you pay today is just one side of the puzzle, because professional research houses have laid out where they think Boeing could be a few years from now, and that forecast path is the next lens to compare with the current valuation. Explore where analysts expect Boeing to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com