
HVACR Testing Expansion Might Change The Case For Investing In UL Solutions (ULS)
- UL Solutions expanded its HVACR Center of Excellence in Plano, Texas, adding larger test capacity and advanced environmental chambers for energy efficient, AI oriented cooling equipment certification across global markets.
- The facility now concentrates safety, performance, compliance and R&D testing in one site, which can simplify manufacturers’ product cycles and support earlier issue detection for complex HVACR and data center cooling systems.
- The next area of focus will be how this expanded HVACR capacity in Plano could influence UL Solutions’ broader investment narrative.
Scan for other companies building the hardware and plumbing behind AI demand by reviewing a hand-picked set of 92 AI infrastructure stocks alongside UL Solutions’ latest testing expansion story.
UL Solutions Investment Narrative Recap
To own UL Solutions, you need to believe the testing, inspection and certification model can keep pulling in steady demand across industrial, consumer and software clients, even as earnings are forecast to edge down 0.9% per year over the next 3 years. The Plano HVACR expansion fits that view because it adds capacity in a regulated, technically complex niche tied to data center and building cooling.
The key near term swing factor is execution on these facility and capability roll outs without putting too much pressure on free cash flow or margins, which already face some valuation scrutiny given a 28.4x P/E. The biggest risk is that macro or regulatory slowdowns delay customer projects, leaving new labs underutilized while costs are already locked in.
The most directly connected recent move is UL Solutions’ new certification program for direct to chip liquid cooling subassemblies, which targets the same AI and high density data center demand that the expanded Plano lab is designed to support. Investors watching AI infrastructure as a theme can now track UL Solutions on both the component certification and full system testing fronts.
This tightening link to data center hardware testing creates an additional operational catalyst if manufacturers lean more on independent safety and interoperability credentials to win business. The flip side is concentration risk, since any pause in AI related compute investment would hit this newer revenue stream first while the company is still digesting higher capex and managing an earnings profile that consensus already expects to soften.
UL Solutions' current analyst narrative points to revenues of $3.8b and earnings of $492.1 million by 2029. That path assumes revenue growth of 6.1% per year and an earnings decline of $13.9 million from $506.0 million today.
Discover how UL Solutions' fair value indicates a 38% potential upside to its current price that may not last much longer.
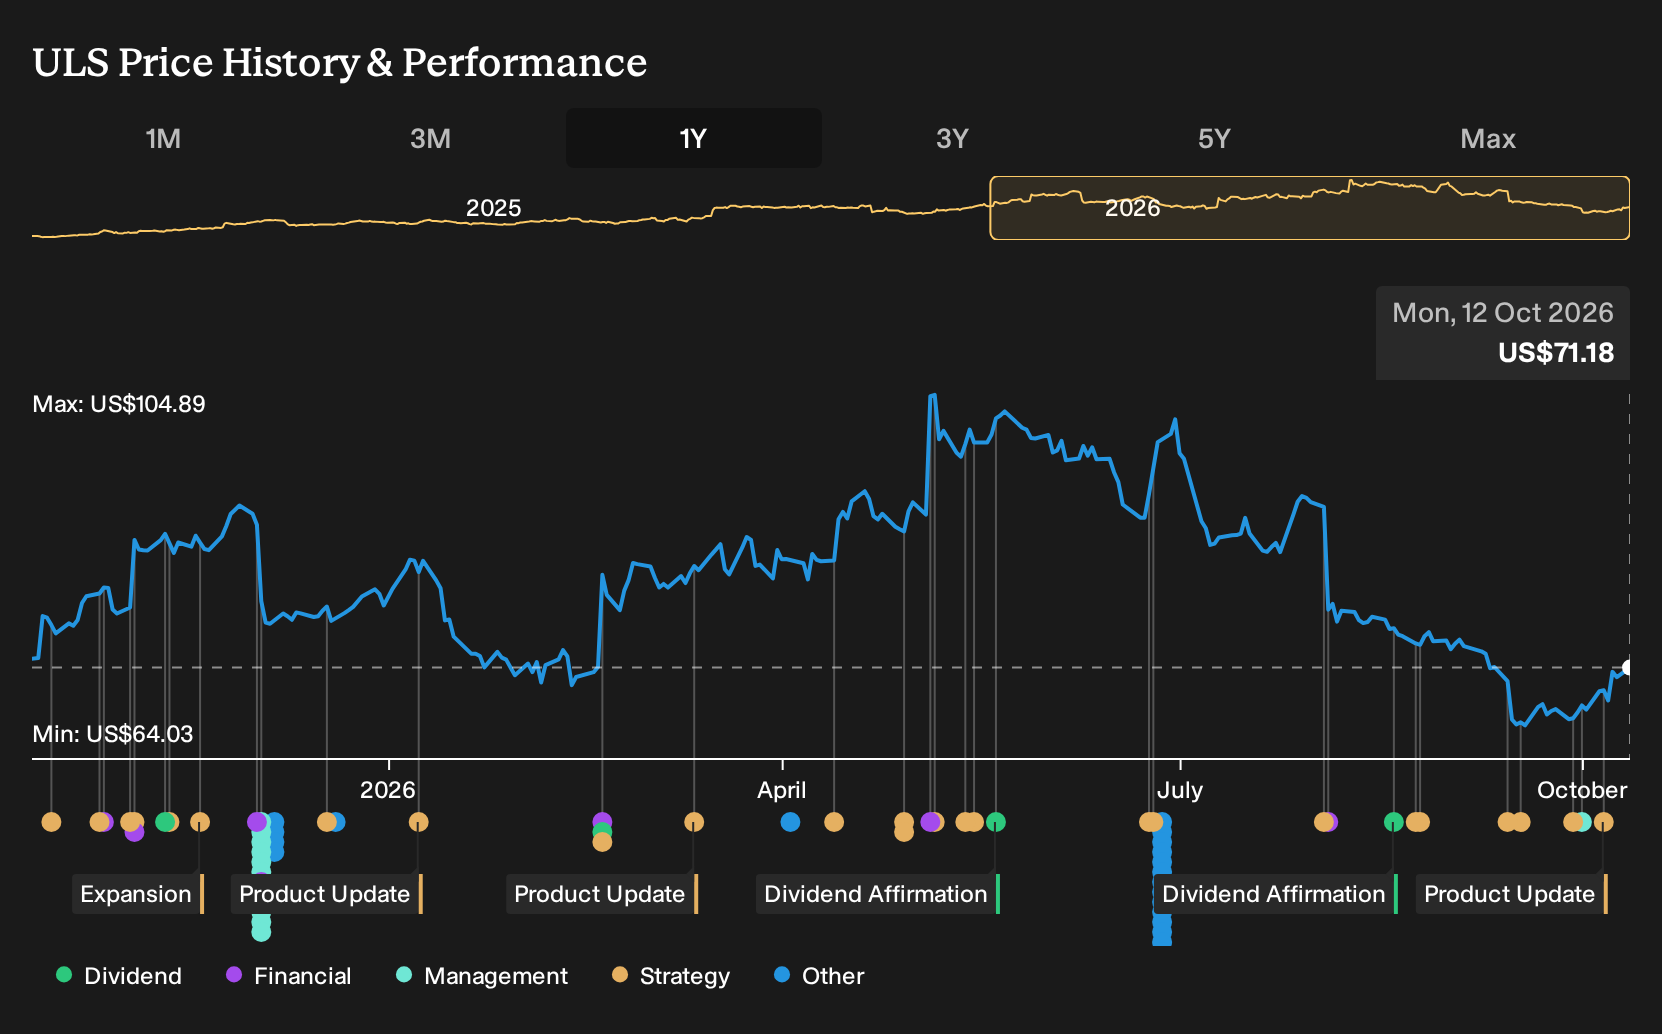
Exploring Other Perspectives
One alternate view leans into the AI and electrification catalyst far more aggressively. The most optimistic analysts were already penciling in 8.0% annual revenue growth and earnings of about $535.2 million by 2029 for UL Solutions before this Plano expansion. You can treat this new HVACR capacity as a fresh test of those higher expectations.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your UL Solutions research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for UL Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UL Solutions' overall financial health at a glance.
Looking for more investment ideas beyond UL Solutions?
If UL Solutions has put testing and infrastructure on your radar, it can be useful to line it up against a wider watchlist built around clear financial traits.
- If capital protection sits high on your list, check out 31 resilient stocks with low risk scores that score well on resilience and stability.
- For investors who care most about rock solid finances, scan a curated list of solid balance sheet and fundamentals (25 results) and compare their strength to UL Solutions.
- If you want potential upside with quality to back it up, review a focused 20 high quality undiscovered gems that the market may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com