
Bristol Myers Squibb (BMY) Stock May Be Undervalued Despite Fresh Phase 3 Trial Wins
Bristol-Myers Squibb has delivered a strong 38.1% share price gain over the past year, even as the stock has pulled back in recent weeks, which puts fresh attention on whether that move is adequately backed by its earnings power. With a series of positive late stage trial readouts and an expanded approval in cardiology on the table, the question now is how much of that clinical momentum is already reflected in what investors are paying for Bristol-Myers Squibb today.
- The 38.1% return over the past 12 months raises the stakes for anyone asking whether the current valuation is still grounded in what the business is earning rather than recent share price momentum alone.
- Positive Phase 3 data in idiopathic pulmonary fibrosis, gastroenteropancreatic neuroendocrine tumors and multiple myeloma, along with a broader CAMZYOS approval, can shape expectations for future profit streams that investors often try to capitalise into today’s earnings multiple.
- Your read on Bristol-Myers Squibb is one view; the desks covering it have another. See what analysts think Bristol-Myers Squibb's shares could be worth.
For investors, the debate is whether Bristol-Myers Squibb's current share price is appropriately aligned with what its earnings justify after this mix of strong one year performance and clinically focused newsflow.
To evaluate whether Bristol-Myers Squibb's recent 38.1% one-year gain and late-stage pipeline news affect how you think about paying for earnings, it can be helpful to compare across 29 high quality undervalued stocks.
Is Bristol-Myers Squibb a Bargain on Earnings?
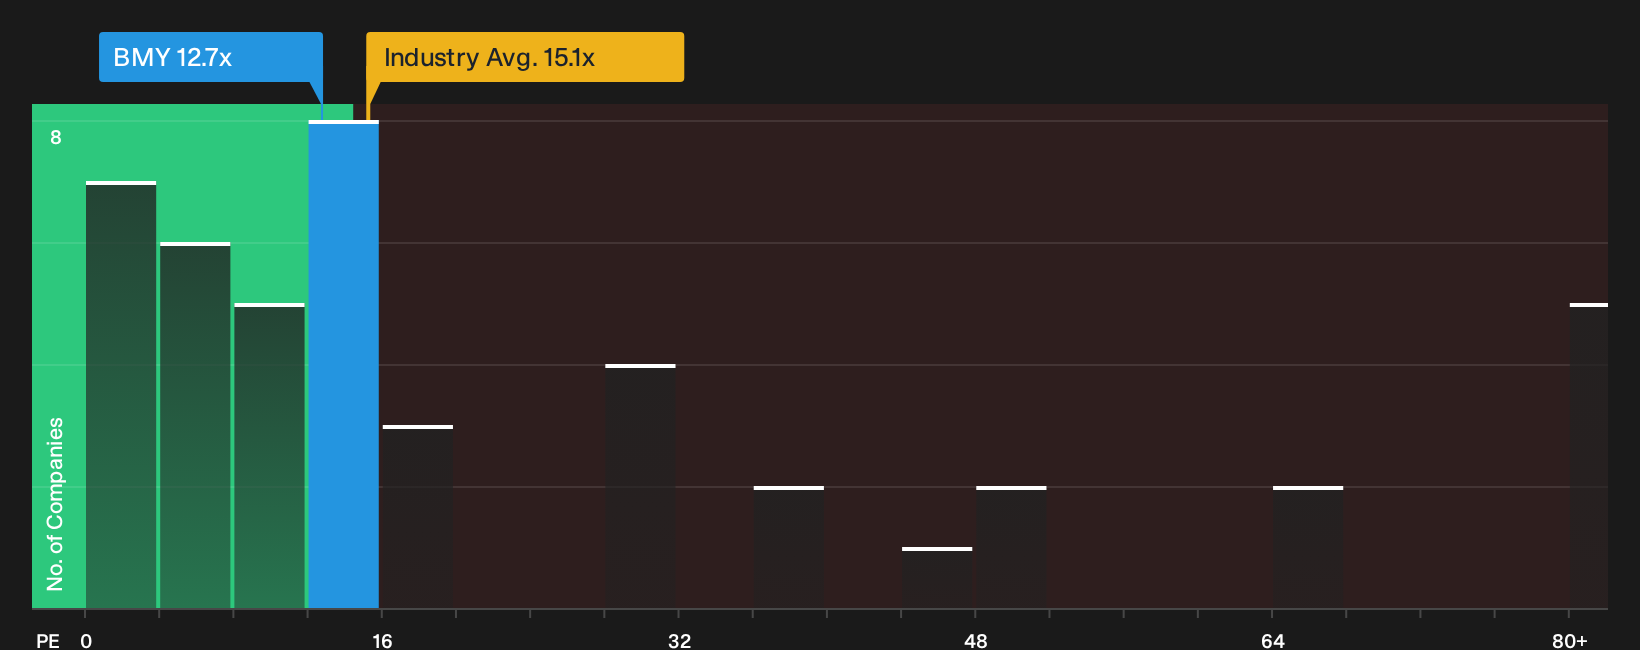
The P/E ratio is a useful yardstick for Bristol-Myers Squibb because earnings still anchor how investors weigh its large drug portfolio and late stage pipeline. On this metric, the stock trades at about 12.7x earnings compared with a pharmaceuticals industry average near 15.1x and a peer group sitting around 62.5x. That puts Bristol-Myers Squibb on a noticeably lower multiple than both its sector and similar large drug makers.
The fair P/E that a tailored model suggests for this business, which tries to account for its margins, risk profile, size and sector, is above where the shares change hands today. Because the recent positive Phase 3 data across idiopathic pulmonary fibrosis, gastroenteropancreatic neuroendocrine tumors and multiple myeloma, as well as the broader CAMZYOS approval, have not pushed the P/E up toward peer levels, the stock currently prices those clinical developments at a discount to what comparable companies command. Explore the numbers behind Bristol-Myers Squibb's P/E valuation.
The Bristol-Myers Squibb Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Bristol-Myers Squibb's valuation puzzle leaves off by spelling out which expectations for growth, profitability and earnings would need to hold for the stock to look meaningfully cheaper or more expensive than it does today on the Community page. Each narrative links its number to a clear view on how Bristol-Myers Squibb's growth, margins and risk profile might evolve, giving you a reference point you can revisit as fresh information comes through.
Community views on Bristol-Myers Squibb split between confidence in the newer portfolio and caution around patent cliffs and trial timing.
Bull case: 30% undervalued
"Bullish analysts expect Bristol-Myers Squibb to keep shifting revenue toward its newer oncology, cardiovascular, and immunology drugs as growth products such as Eliquis, Reblozyl, Breyanzi, Opdualag, Camzyos, Qvantig and Sotyktu scale from their current contribution of nearly 60% of total sales..."
Discover why this Narrative puts Bristol-Myers Squibb at 30% undervalued.
Bear case: 18% overvalued
"Bearish analysts expect loss of exclusivity and pricing pressure on key drugs to continue eroding Bristol-Myers Squibb’s revenue mix and margin profile, even as the newer portfolio grows..."
Explore why this Narrative puts Bristol-Myers Squibb at 18% overvalued.
One more Bristol-Myers Squibb check that belongs beside the P/E math
Bristol-Myers Squibb’s share price and earnings multiple tell only part of the story. The research screen has also highlighted specific concerns that investors may want to review before taking the next step. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com