
Undervalued Small Caps In Global With Insider Action For October 2026
In October 2026, global markets are navigating a landscape marked by volatility in energy prices and geopolitical tensions, with the Russell 2000 Index experiencing a decline amidst these challenges. As small-cap stocks face fluctuating market conditions, identifying those with strong fundamentals and insider activity can be crucial for investors seeking potential opportunities.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| China Aircraft Leasing Group Holdings | 6.9x | 0.9x | 39.43% | ★★★★★☆ |
| Centurion | 16.8x | 3.3x | 44.15% | ★★★★☆☆ |
| Diversified Royalty | 25.4x | 10.1x | 46.02% | ★★★★☆☆ |
| Nexus Industrial REIT | 9.9x | 3.0x | 9.95% | ★★★★☆☆ |
| Saniona | 6.8x | 2.9x | 36.81% | ★★★★☆☆ |
| Yellow Pages | 8.4x | 0.8x | 29.06% | ★★★☆☆☆ |
| Citicore Energy REIT | 13.2x | 10.0x | 27.26% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 21.48% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -202.58% | ★★★☆☆☆ |
| Coveo Solutions | NA | 2.0x | -4.94% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
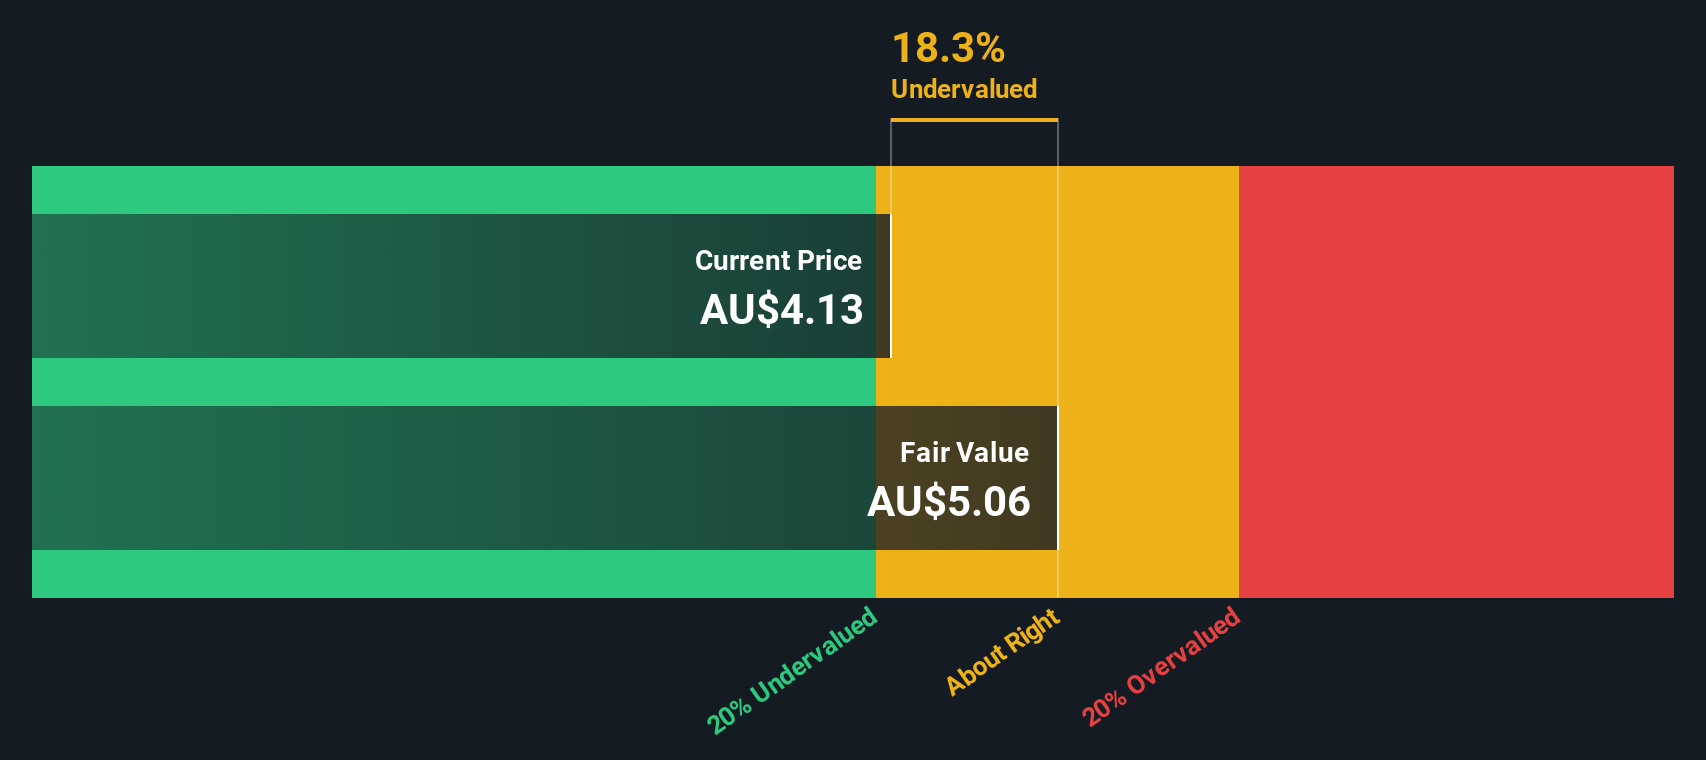
Charter Hall Long WALE REIT (ASX:CLW)
Simply Wall St Value Rating: ★★★★★☆
Overview: Charter Hall Long WALE REIT is an Australian real estate investment trust focused on commercial properties, with a market cap of A$4.45 billion.
Operations: The company generates revenue primarily from its commercial real estate investments, with a recent quarterly revenue of A$194.35 million. Its cost of goods sold (COGS) was A$57.89 million, leading to a gross profit margin of 70.21%. Operating expenses are relatively low at A$3.69 million, while non-operating activities have significantly impacted net income due to negative expenses recorded in this area.
PE: 8.6x
Charter Hall Long WALE REIT, a smaller player in the real estate investment sector, recently declared an unfranked distribution of A$0.06375 per security for Q3 2026. Despite achieving net income growth to A$275.9 million from A$120.84 million last year, earnings are projected to decline by 5.3% annually over the next three years due to reliance on external borrowing and large one-off items impacting results. With insider confidence shown through recent share purchases, this company presents a mixed opportunity for investors seeking undervalued stocks with potential challenges ahead.
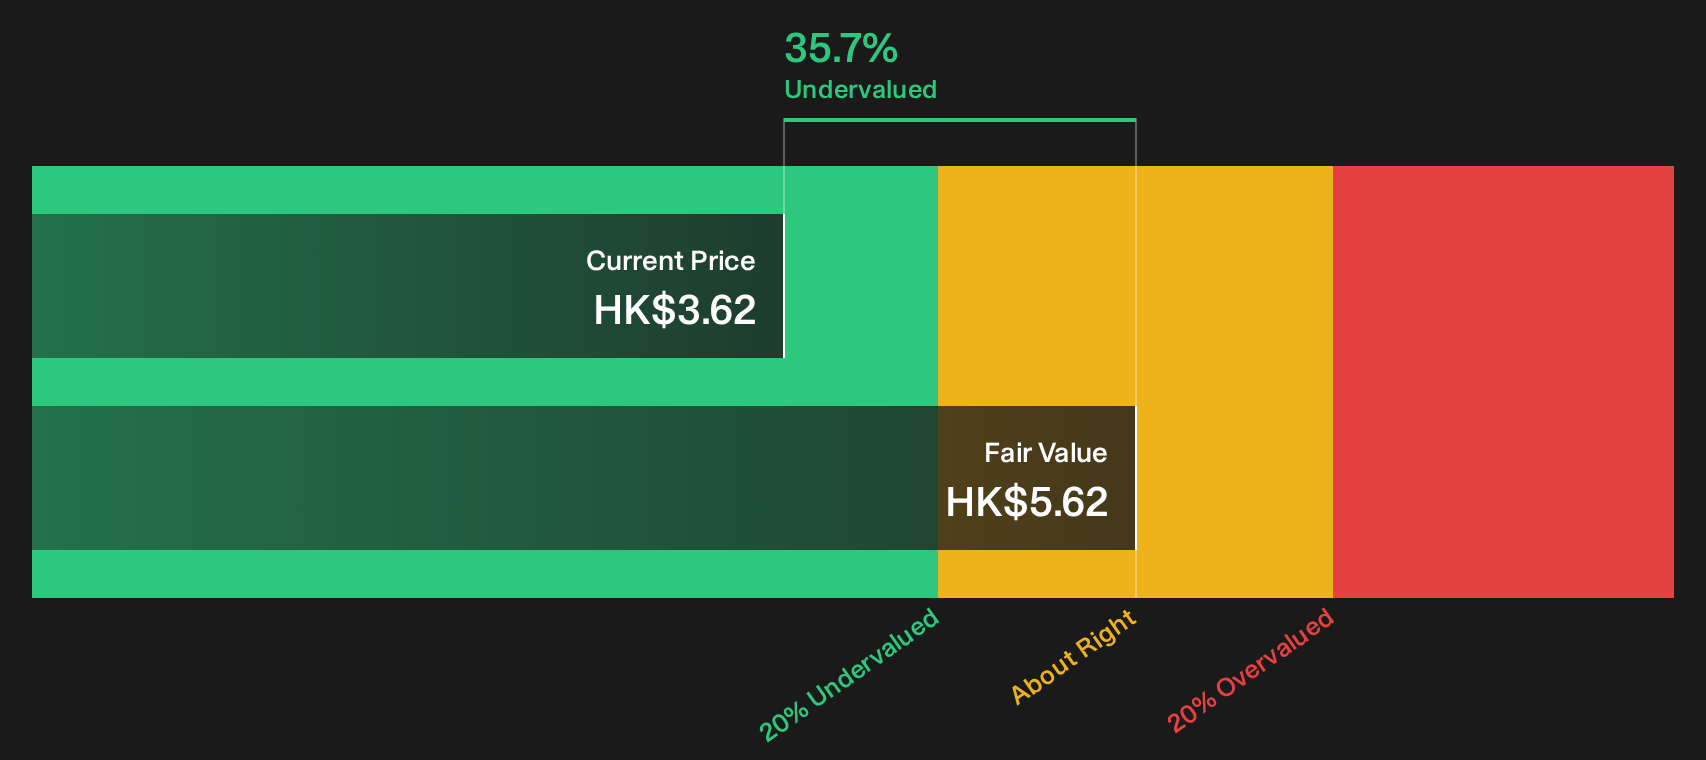
China Aircraft Leasing Group Holdings (SEHK:1848)
Simply Wall St Value Rating: ★★★★★☆
Overview: China Aircraft Leasing Group Holdings is a company that provides aircraft leasing services and has a market capitalization of approximately HK$3.13 billion.
Operations: The company generates revenue primarily from aircraft leasing services, with recent figures reaching HK$2.78 billion. Its cost structure includes significant operating expenses and depreciation & amortization costs, which impact net income margins. Notably, the gross profit margin has recently been recorded at 68.59%.
PE: 6.9x
China Aircraft Leasing Group Holdings, a smaller player in the aviation leasing sector, recently reported an impressive increase in half-year sales to HK$829.4 million from HK$136.43 million last year, with revenue rising to HK$3.91 billion. Despite using higher-risk external borrowing for funding, insider confidence is evident as they have been purchasing shares over the past year. The company declared an interim dividend of HK$0.14 per share with a scrip option at a discount, indicating potential growth and shareholder value focus amidst its financial challenges.
- Take a closer look at China Aircraft Leasing Group Holdings' potential here in our valuation report.
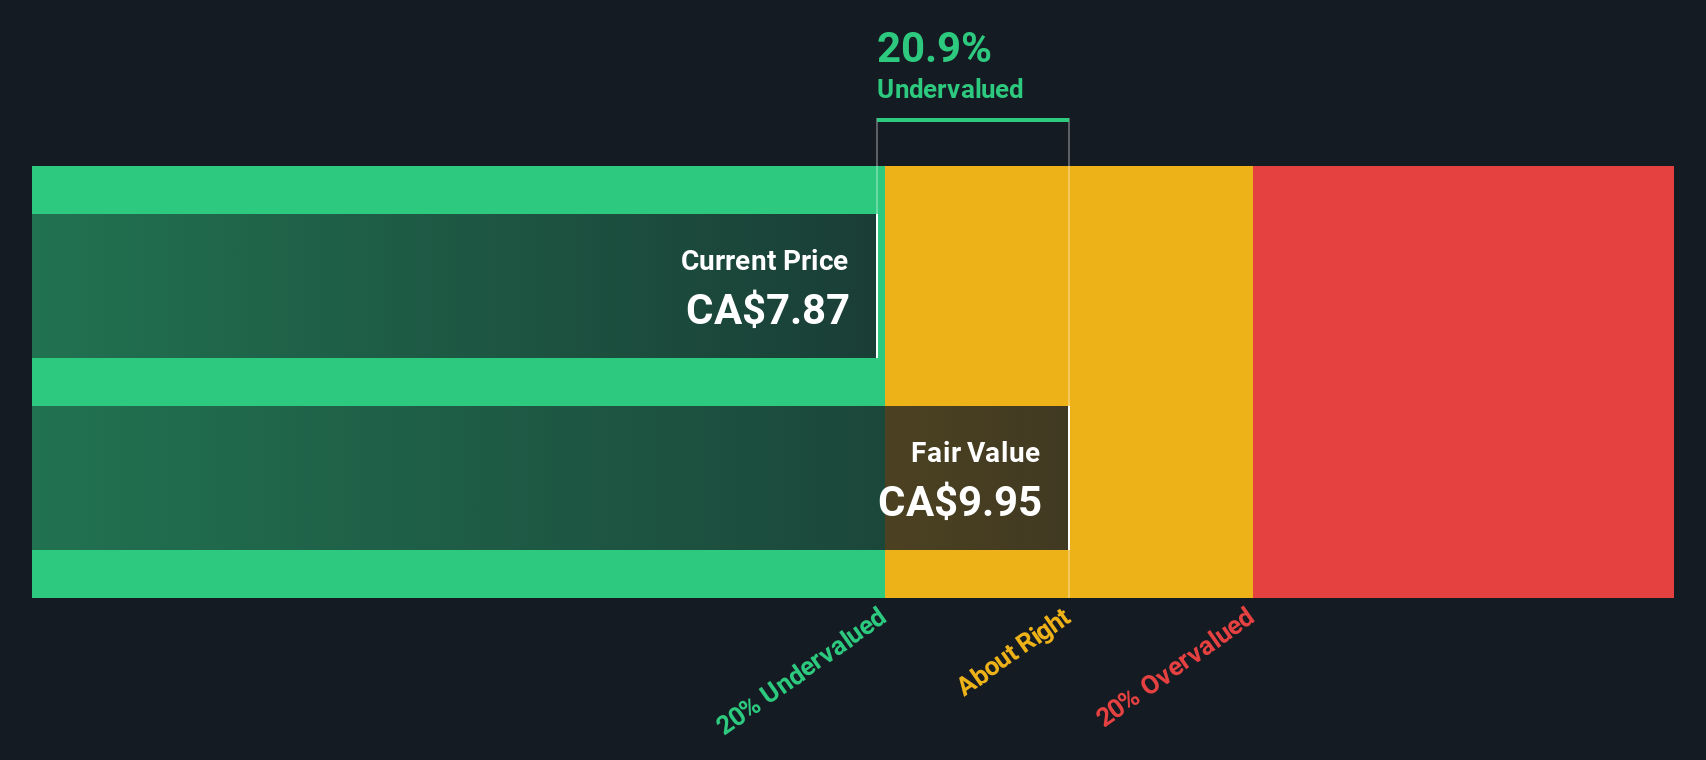
Nexus Industrial REIT (TSX:NXR.UN)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Nexus Industrial REIT is a real estate investment trust focused on owning and managing a diversified portfolio of industrial properties, with a market capitalization of CA$1.24 billion.
Operations: Nexus Industrial REIT generates revenue primarily from its investment properties, with a recent quarter showing CA$178.40 million in revenue. The company's cost of goods sold (COGS) was CA$47.67 million, resulting in a gross profit margin of 73.28%. Operating expenses were reported at CA$9.02 million, impacting the net income margin which stood at 29.93%.
PE: 9.9x
Nexus Industrial REIT, a smaller player in the industrial real estate sector, recently completed a CAD 300 million debt offering with a fixed annual interest rate of 4.563%, aimed at refinancing existing debts. Despite reporting CAD 46.62 million in Q2 sales, the company faced a net loss of CAD 12.81 million. However, insider confidence is evident as CFO Michael Rawle purchased 37,500 shares valued at approximately C$299,775 between August and October 2026. This suggests potential optimism about future prospects despite current financial challenges.
- Click here and access our complete valuation analysis report to understand the dynamics of Nexus Industrial REIT.
Gain insights into Nexus Industrial REIT's past trends and performance with our Past report.
Turning Ideas Into Actions
- Access the full spectrum of 120 Undervalued Global Small Caps With Insider Buying by clicking on this link.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com