
Global Growth Companies With High Insider Ownership To Watch
As global markets navigate through volatility driven by AI-related stock fluctuations, Middle East tensions, and fluctuating energy prices, investors are increasingly focused on identifying resilient growth opportunities. In such a climate, companies with high insider ownership often stand out as they suggest strong confidence from those who know the business best and can be particularly appealing in uncertain times.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
We're going to check out a few of the best picks from our screener tool.
Advanced Petrochemical (SASE:2330)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Advanced Petrochemical Company, with a market cap of SAR5.77 billion, produces and sells propylene, polypropylene, isopropyl alcohol, polysilicon, and related products both in Saudi Arabia and internationally.
Operations: The company's revenue is primarily generated from its Specialty Chemicals segment, which reported SAR4.10 billion.
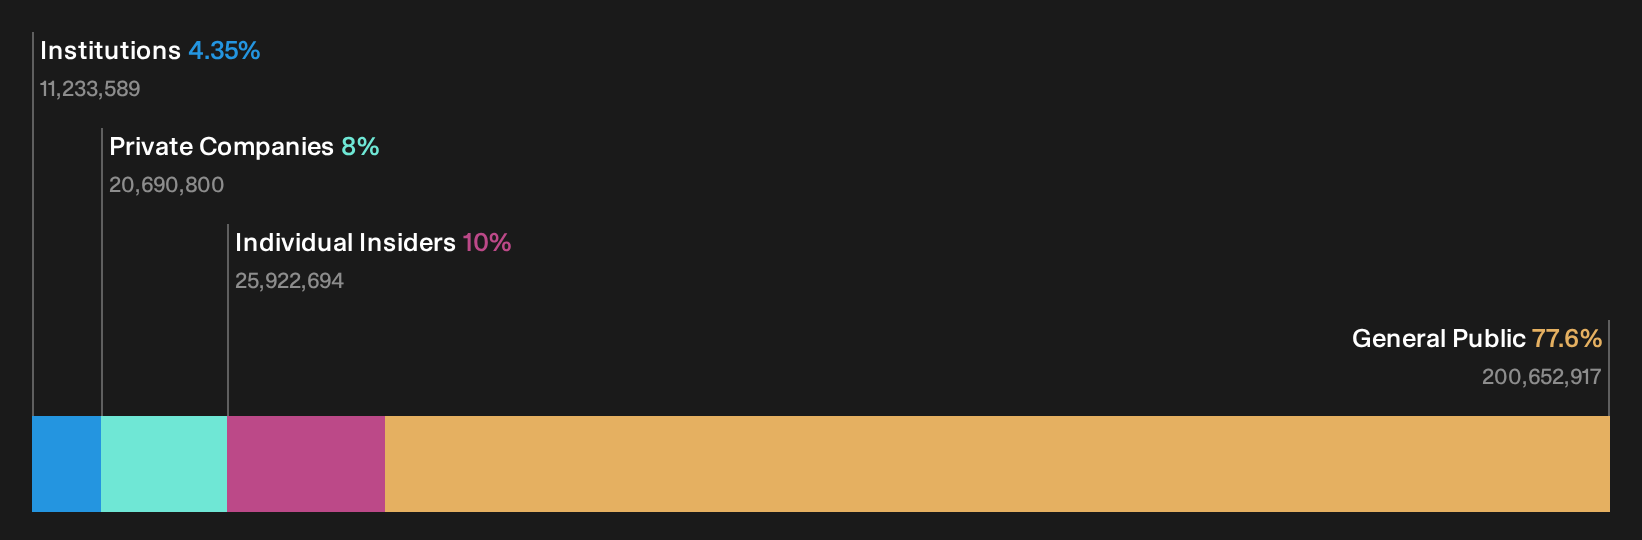
Insider Ownership: 10%
Earnings Growth Forecast: 83.7% p.a.
Advanced Petrochemical is trading significantly below its estimated fair value, suggesting potential upside. Despite becoming profitable this year, recent earnings show a net loss of SAR 98.41 million for Q2 2026, impacted by one-off items. Revenue growth is expected at 13.1% annually, outpacing the South African market but falling short of high-growth benchmarks. Earnings are forecast to grow substantially over the next three years, though interest coverage remains a concern.
- Delve into the full analysis future growth report here for a deeper understanding of Advanced Petrochemical.
- Our comprehensive valuation report raises the possibility that Advanced Petrochemical is priced lower than what may be justified by its financials.
Shanghai Chicmax Cosmetic (SEHK:2145)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Shanghai Chicmax Cosmetic Co., Ltd. is a multi-brand cosmetics company involved in the research, development, manufacture, and sale of cosmetics both in Mainland China and internationally, with a market cap of HK$8.77 billion.
Operations: The company's revenue primarily comes from the manufacture and sale of cosmetic products, amounting to CN¥8.83 billion.
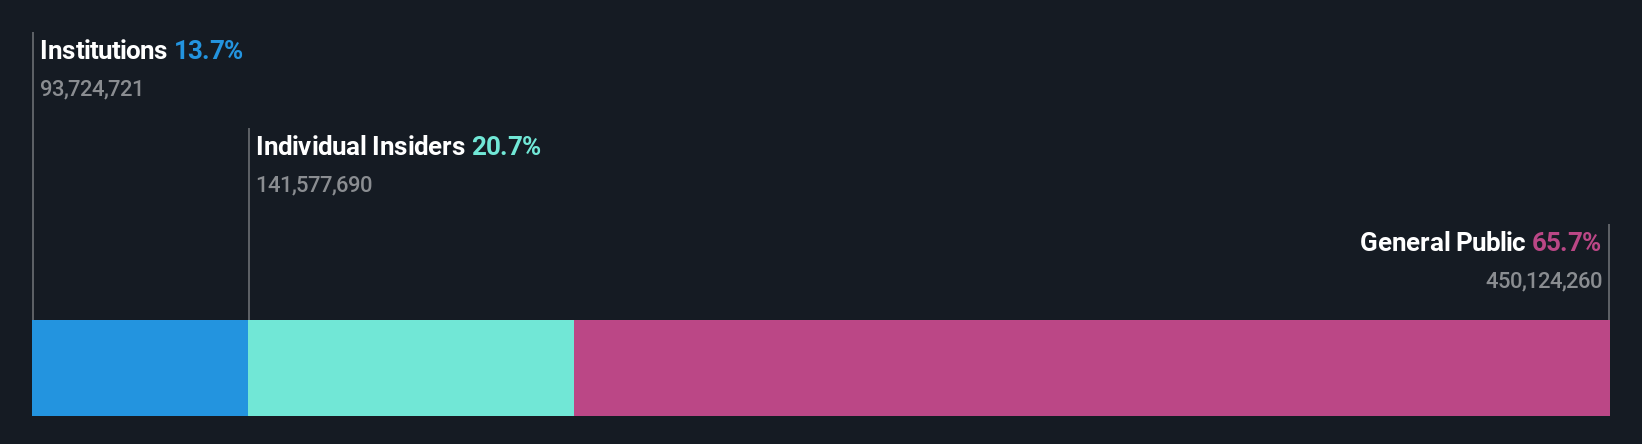
Insider Ownership: 39.5%
Earnings Growth Forecast: 26.2% p.a.
Shanghai Chicmax Cosmetic is trading at a good value, 23.5% below its estimated fair value, with earnings forecast to grow significantly at 26.2% annually, outpacing the Hong Kong market. Insider buying has occurred recently without substantial selling. However, recent financials show a decline in revenue and profit due to market factors affecting its KANS brand. The company is undergoing strategic changes with new board appointments and share repurchase plans underway.
- Dive into the specifics of Shanghai Chicmax Cosmetic here with our thorough growth forecast report.
- According our valuation report, there's an indication that Shanghai Chicmax Cosmetic's share price might be on the cheaper side.

Hunan Zhongke Electric (SZSE:300035)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Hunan Zhongke Electric Co., Ltd. specializes in the research, development, production, and sales of electromagnetic metallurgy products both in China and internationally, with a market cap of CN¥8.74 billion.
Operations: The company's revenue is primarily derived from its operations in the research, development, production, and sales of electromagnetic metallurgy products within China and on an international scale.
Insider Ownership: 15.3%
Earnings Growth Forecast: 63.3% p.a.
Hunan Zhongke Electric is positioned for growth with revenue projected to increase by 20.2% annually, surpassing the CN market's average. Despite a decline in profit margins from 7.3% to 3.4%, earnings are expected to grow significantly at 63.27% per year, outpacing the market's 27%. The company trades at a favorable P/E ratio of 25.4x compared to the market's 40.4x and has announced a private placement aiming for up to CNY 2.4 billion in proceeds, pending regulatory approvals.
- Unlock comprehensive insights into our analysis of Hunan Zhongke Electric stock in this growth report.
- Insights from our recent valuation report point to the potential undervaluation of Hunan Zhongke Electric shares in the market.
Seize The Opportunity
- Click through to start exploring the rest of the 705 Fast Growing Global Companies With High Insider Ownership now.
- Want To Explore Some Alternatives? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com