
Altria Group (MO) Faces A Valuation Test Following Its Credit Facility Extension
Altria Group (MO) has extended the expiration of its US$3.0b senior unsecured 5 year revolving credit facility by one year, continuing the agreement with JPMorgan, Citibank and other lenders to October 24, 2030.
The revolving credit extension comes as Altria Group’s share price has climbed 25.04% year to date and the 1-year total shareholder return is 17.79%, while multi-year total shareholder returns above 100% suggest that longer-term holders have seen far stronger gains than recent momentum implies.
Scan how Altria Group compares with other income heavyweights by reviewing our hand picked list of 8 dividend fortresses.
Altria Group’s share price now sits close to the average analyst target, yet screens at a large intrinsic discount. Where does fair value really lie after this latest leg higher?
Most Popular Narrative: 2% Overvalued
On the most followed view, Altria Group screens on a fair value of $70 per share, slightly below the latest $71.66 close. This puts the recent rally against a tight margin of safety built on smoke free execution and capital returns.
Earlier views centred on regulatory and competitive pressures that could weigh on e vapor and oral tobacco revenue. The focus now leans more on smoke free products like on! and on! PLUS, with specific shipment data and FDA approvals supporting potential contributions to revenue and earnings.
See why 257 investors see Altria Group as 2% overvalued.
Result: Fair Value of $70 (OVERVALUED)
Still, that fair value story can crack if discount cigarettes keep taking share from Marlboro or if legal and regulatory investigations into on! PLUS deepen and add costs.
Find out about the key risks to this Altria Group narrative.
Another View: What Altria Group’s Ratios Are Saying
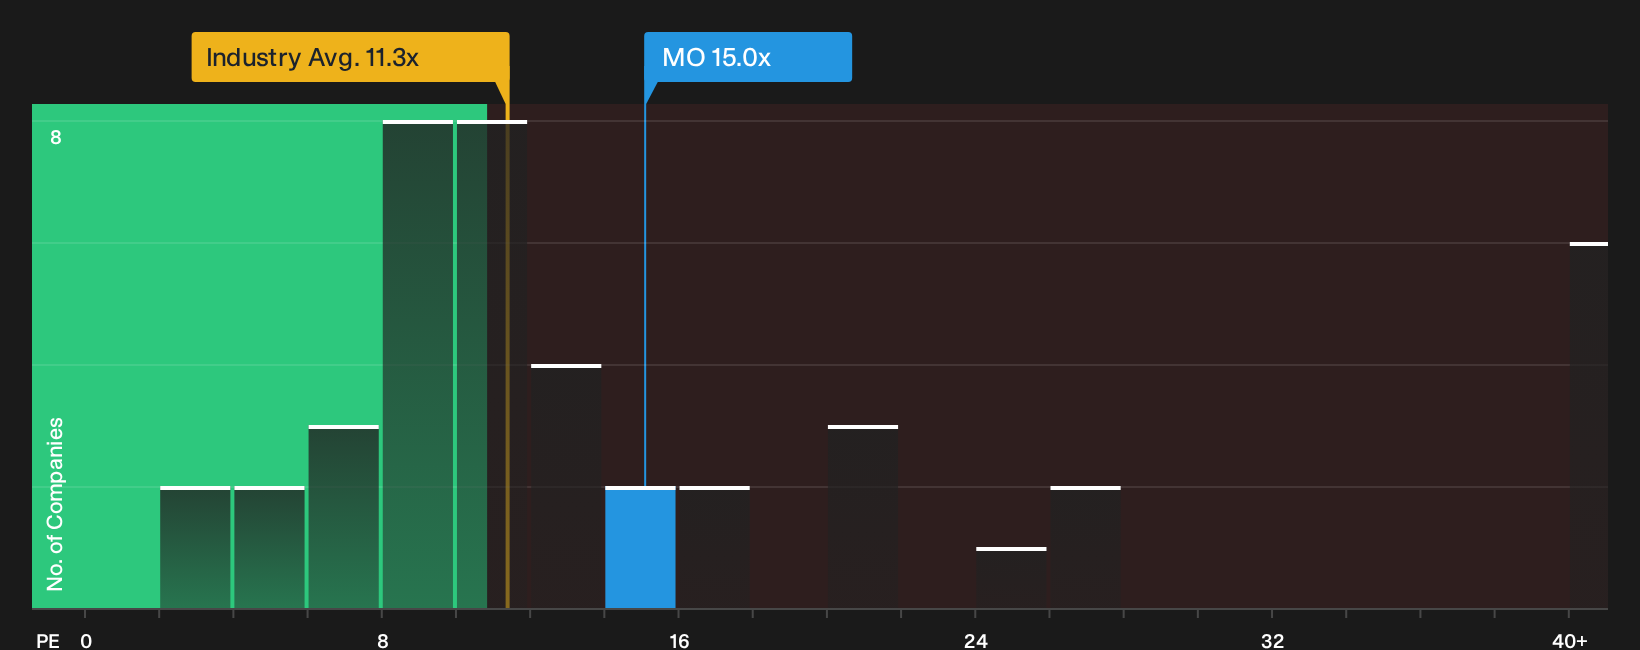
While the consensus fair value for Altria Group points to a 2% premium at $70, the price tag looks different when viewed through earnings multiples. The stock trades on a P/E of 15x, above the global tobacco average of 11.3x, yet below a fair ratio of 20.5x that our model suggests the market could move toward over time. That mix of relative expensiveness to the sector and a discount to the fair ratio frames both valuation risk and upside potential, so which side of that trade off do you think matters more for your own thesis?
See what the numbers say about this price in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
For a visual read on how Altria Group’s valuation stacks up against peers, take a closer look at
Next Steps
Mixed messages so far on Altria Group, which is exactly why it helps to look under the hood yourself and move quickly while the market is debating the story. To see both the concerns and the potential upside clearly laid out, start with 3 key rewards and 2 important warning signs.
Looking for more Altria Group sized opportunities?
You have seen what is moving Altria Group today, so do not stop there. Broaden your watchlist and give yourself more quality options.
- Target resilient cash generators and scan a 29 high quality undervalued stocks that combine solid fundamentals with prices that still look appealing.
- Balance return and resilience by searching through a 31 resilient stocks with low risk scores that score well on financial strength and business stability.
- Get ahead of the crowd and review a 20 high quality undiscovered gems before they attract wider attention and potential capital flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com