
IonQ (IONQ) Stock Looks About Right After Its 239% Five Year Run
IonQ has delivered very large 5 year returns for shareholders, yet the recent share pullback and fresh quantum security deals leave a pointed question about how its current market value compares with the book value on its balance sheet. With the stock now trading well below its 1 year high and sentiment swinging around major contract and acquisition headlines, investors are asking how much of the story is already priced in relative to IonQ's net assets.
- Over 5 years IonQ has gained about 239.3%, which puts a lot of pressure on the current share price to be supported by more than just the book value reported on its balance sheet.
- The agreed all stock purchase of Elisity, valued at up to US$1.3b and expected to close in late 2026, could reshape IonQ's asset base and future capital needs, which may change how investors interpret its price against book value over time.
- There is a second opinion on IonQ worth weighing. See what analysts think IonQ's shares could be worth.
The stock's next move may depend on whether IonQ's current price can be reconciled with its book value when set against the industry average.
If you are weighing IonQ against other quantum-focused opportunities, it can help to see how a wider set of listed players are priced on this theme through 25 quantum computing stocks.
Where Does IonQ Sit on Book Value?
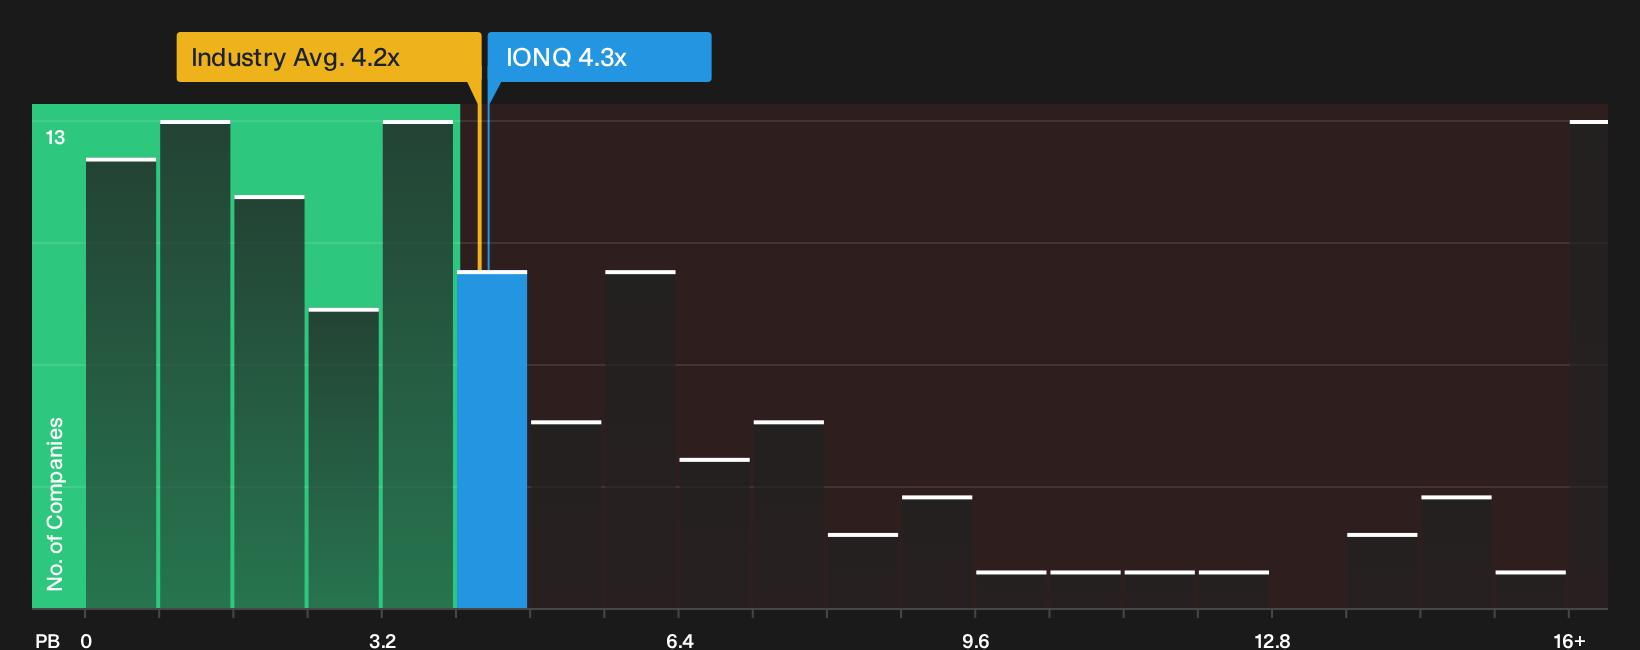
P/B tends to matter for IonQ because investors often anchor early stage quantum hardware bets to the cash, intangibles and acquired tech recorded on the balance sheet. Right now, IonQ trades on a P/B of about 4.3x, which is very close to the semiconductor industry average of roughly 4.2x.
The peer group referenced here screens at a higher level, with an average P/B of about 13.4x, so IonQ changes hands at a sizeable discount to that subset even though it prices broadly in line with the wider sector. Despite the recent Elisity all stock acquisition agreement drawing attention to future dilution and shifting asset mix, the current P/B suggests the market is valuing IonQ roughly in step with the typical semiconductor business rather than assigning a clear premium for its quantum focus. Explore the numbers behind IonQ's P/B valuation.
The IonQ Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the IonQ valuation puzzle leaves off by spelling out which future paths for growth, profitability and earnings would need to hold for the stock to trade meaningfully above or below today's level. Rather than leaning on a single multiple or one model output, each scenario lays out the underlying assumptions behind its fair value so you can track those against IonQ's actual results on the Community page as they are reported.
IonQ inspires sharply different stories, with some community members seeing a future quantum heavyweight and others worried the valuation is racing far ahead of the business.
Bull case: 57% undervalued
"IonQ has systematically de-risked its thesis, and is now fully funded to execute a 'winner-take-all' land grab, positioning it as the potential 'Nvidia of Quantum'…"
Discover why this Narrative puts IonQ at 57% undervalued.
Bear case: 617% overvalued
"At current prices, IonQ trades at well over 100 times revenue, a level rarely sustained even among the fastest growing technology companies…"
Explore why this Narrative puts IonQ at 617% overvalued.
One more IonQ check investors should not skip
Price and book value only tell part of the story for IonQ, because Simply Wall St's broader review has also highlighted specific caution flags that deserve a closer look beside the headline multiples. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com