
Did Autotrader Group's Fall Catch You Out? What Investors Missed
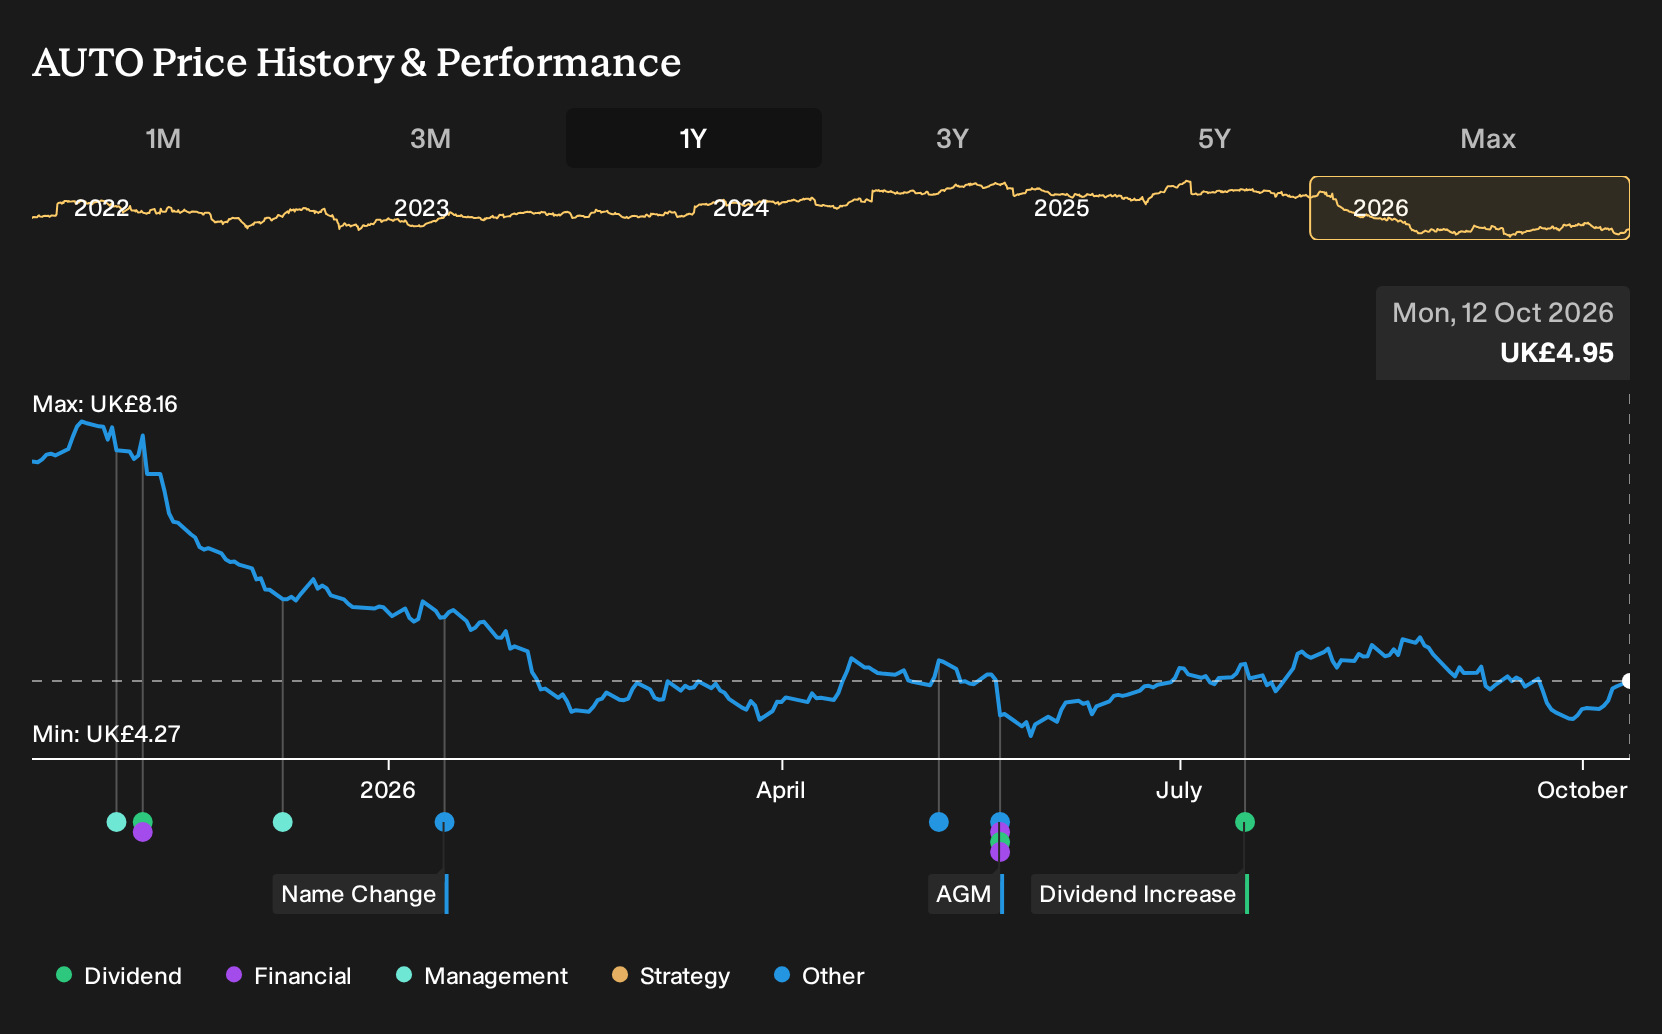
If you only glanced at Autotrader Group’s headlines about AI tools and new car partnerships, the eventual outcome might come as a shock. For Autotrader Group shareholders, the loss over the past year was 33.9%, including dividends. Revenue ended the period higher while net margin slipped and profit stayed flat, so the setback did not come from an obvious collapse in earnings. If you had been weighing a purchase in October 2025, what clues were really available?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Autotrader Group has already moved. See which of 7 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Weigh On Auto Trader Group
The shares cost £7.68 at the start of the period, and anyone looking at Auto Trader Group then had two clear stories to compare.
The bullish narrative put Fair Value at £8.53, assuming tools like Deal Builder and the Co-Driver AI suite lifted customer engagement enough to support higher revenue and stronger net margins.
The bearish narrative pointed to a Fair Value of £6.50, leaning on risks from shared mobility, tighter regulation and direct-to-consumer car sales potentially reducing Auto Trader Group’s long term market opportunity.
What The Evidence Did To The Auto Trader Group Argument
Chinese car brands providing virtually all UK new car market growth gave Auto Trader Group fresh product demand to plug into, which leaned toward the bullish story around new car partnerships and EV focus. The hard numbers were less flattering. Total revenue reached £306.6m while net income stayed at £143m and net margin slipped to 46.6% from 47.9%. Overall, the evidence cut both ways.
The real hinge here was margin resilience. When you see a story built on higher pricing power or product uptake, watch whether net margin and absolute profit actually move together in reported results.
What You Would Be Paying For In Auto Trader Group Today
Auto Trader Group now trades at £4.95. The selected Narrative sees Fair Value above that level, anchored on AI led products, deeper data usage and a capital return plan that together frame a more optimistic earnings path than the current price implies.
For the recent fall to look like an opportunity rather than a warning, a buyer today would need to believe Deal Builder and the wider AI toolkit become the default UK used car journey, while retailers stay engaged despite pressure on forecourt economics.
"The current valuation and capital return plan, including a target of around £500m of share buybacks in FY27 and a willingness to carry modest leverage, suggests the market is not fully pricing in the cash generation and per share earnings potential that Auto Trader’s existing business already supports."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking Beyond Auto Trader Group
Once you have mapped Auto Trader Group’s role in car buying, another pattern appears nearby.
Searchable listings rely on people finding vehicles online quickly through simple queries.
The same routine of typing questions into a search box guides how shoppers discover almost everything else.
One giant infrastructure company spends heavily on search, video and cloud tools that help businesses reach those same users across the wider internet.
If car retailers keep leaning on online discovery, that broader traffic engine could shape an important parallel story to watch.
One Narrative has already put a figure on it. → Uncover the company trading 19% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com