
UK Stocks Estimated Below Intrinsic Value In October 2026
The UK stock market has recently experienced fluctuations, with the FTSE 100 index closing lower due to weak trade data from China, highlighting global economic interconnections and their impact on domestic markets. Despite these challenges, investors often seek opportunities in undervalued stocks that may offer potential for growth by trading below their intrinsic value, making them particularly appealing in uncertain economic climates.
Top 10 Undervalued Stocks Based On Cash Flows In The United Kingdom
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Stelrad Group (LSE:SRAD) | £1.39 | £2.48 | 43.9% |
| Smiths News (LSE:SNWS) | £0.748 | £1.45 | 48.4% |
| Smith & Nephew (LSE:SN.) | £10.38 | £17.46 | 40.5% |
| Shell (LSE:SHEL) | £38.36 | £68.67 | 44.1% |
| Property Franchise Group (AIM:TPFG) | £4.125 | £7.34 | 43.8% |
| LSL Property Services (LSE:LSL) | £2.60 | £4.56 | 43% |
| IG Group Holdings (LSE:IGG) | £9.765 | £15.81 | 38.2% |
| Hollywood Bowl Group (LSE:BOWL) | £2.55 | £5.02 | 49.2% |
| Gamma Communications (LSE:GAMA) | £10.94 | £20.15 | 45.7% |
| Distribution Finance Capital Holdings (AIM:DFCH) | £0.724 | £1.35 | 46.4% |
We're going to check out a few of the best picks from our screener tool.
M.P. Evans Group (AIM:MPE)
Overview: M.P. Evans Group PLC, with a market cap of £998.91 million, owns and develops oil palm plantations in Indonesia and Malaysia through its subsidiaries.
Operations: The company's revenue primarily comes from its oil palm plantations in Indonesia, generating $387.78 million.
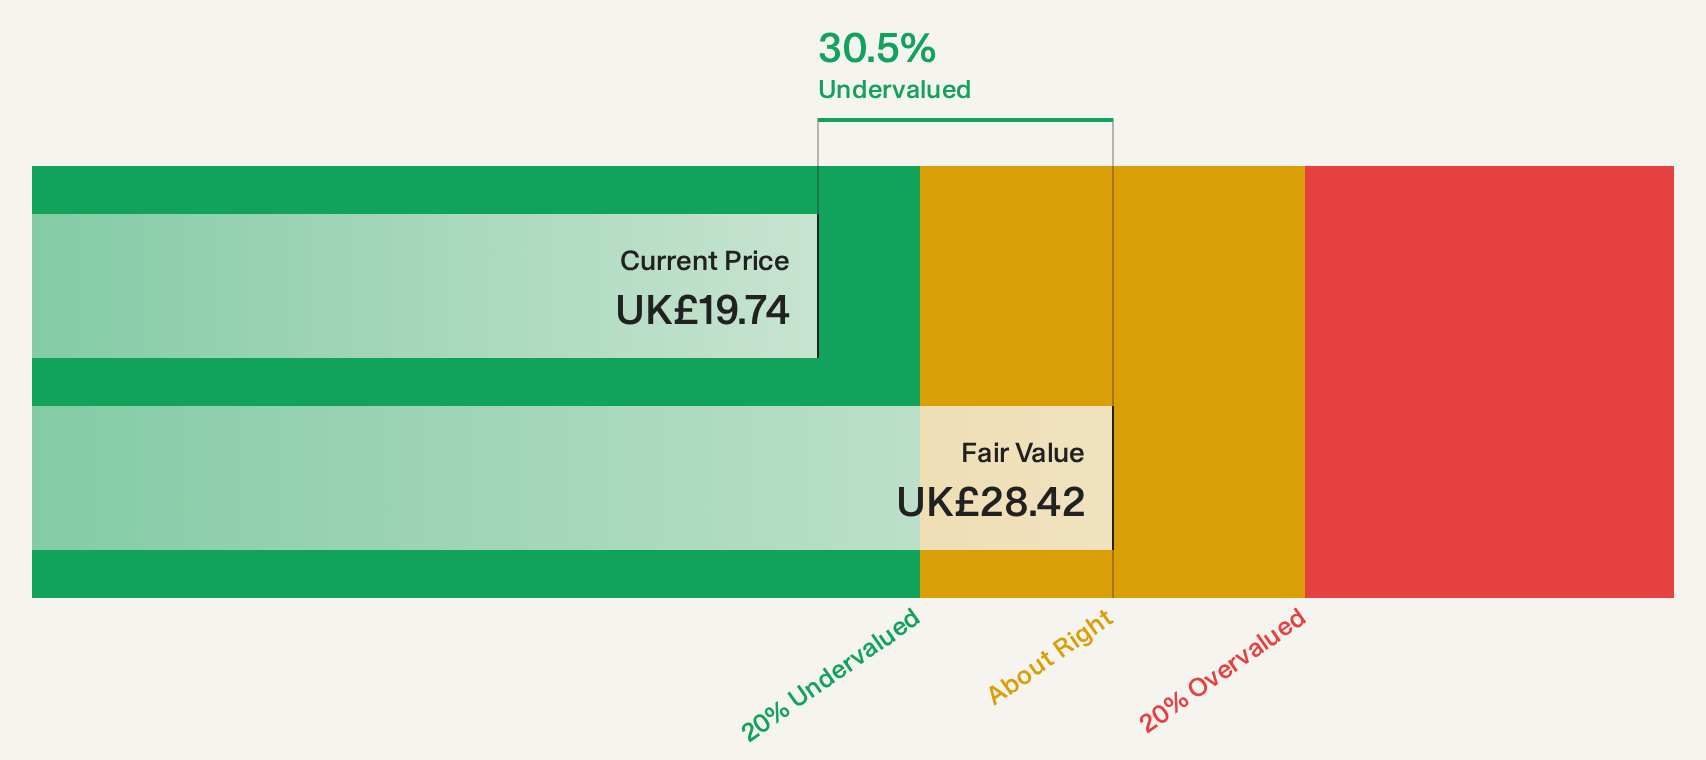
Estimated Discount To Fair Value: 32.3%
M.P. Evans Group is trading at a significant discount to its estimated future cash flow value, with shares priced at £19.22 compared to a projected £28.37. Despite forecasts of declining revenue and earnings over the next three years, recent acquisitions and expansions in Indonesia may bolster long-term growth potential. The company reported improved half-year earnings with net income rising to US$61.01 million, alongside an interim dividend increase, reflecting ongoing shareholder returns amidst strategic investments.
- The analysis detailed in our M.P. Evans Group growth report hints at robust future financial performance.
- Take a closer look at M.P. Evans Group's balance sheet health here in our report.
Genus (LSE:GNS)
Overview: Genus plc is a company that specializes in producing and selling animal genetics to farmers across various regions including North America, Latin America, Europe, the Middle East, Russia, Africa, and Asia with a market capitalization of approximately £1.50 billion.
Operations: The company's revenue is primarily derived from its Genus ABS segment, which contributes £299.80 million, and the Genus PIC segment, which adds £355.80 million.
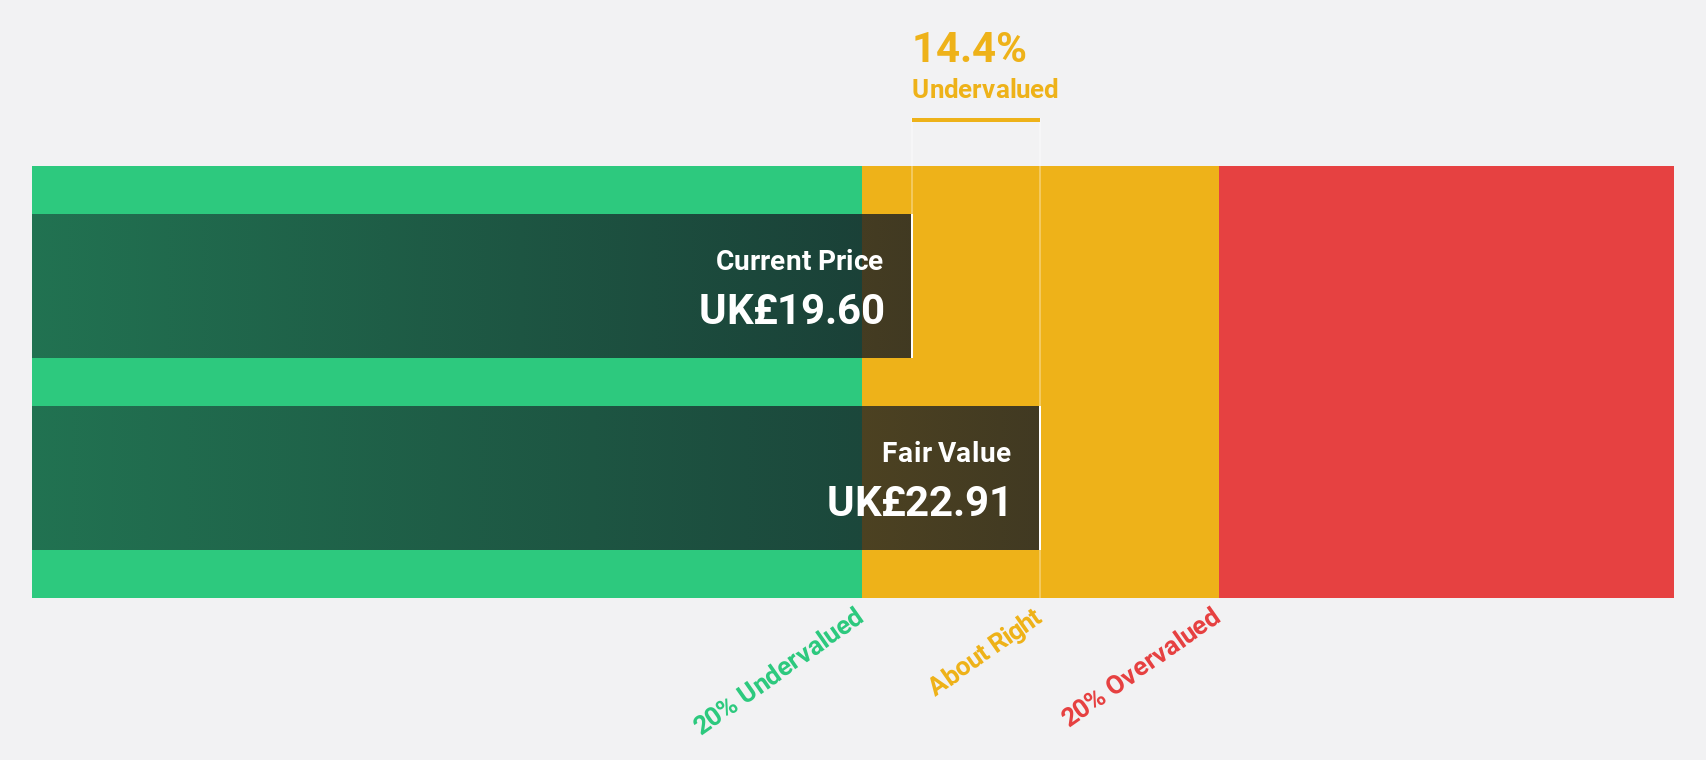
Estimated Discount To Fair Value: 30.4%
Genus is trading at £22.72, significantly below its estimated future cash flow value of £32.65, suggesting it may be undervalued based on cash flows. Despite a recent surge in net income to £285.3 million from £19.3 million last year, earnings are forecast to decline by 43.3% annually over the next three years, with revenue growth expected at just 2.7% per year—below the UK market average of 3.7%.
- The growth report we've compiled suggests that Genus' future prospects could be on the up.
- Unlock comprehensive insights into our analysis of Genus stock in this financial health report.
Howden Joinery Group (LSE:HWDN)
Overview: Howden Joinery Group Plc supplies kitchen, joinery, and hardware products across the United Kingdom, France, Belgium, and the Republic of Ireland with a market capitalization of approximately £4.20 billion.
Operations: The company generates revenue primarily from its Howden Joinery segment, which accounted for £2.45 billion.
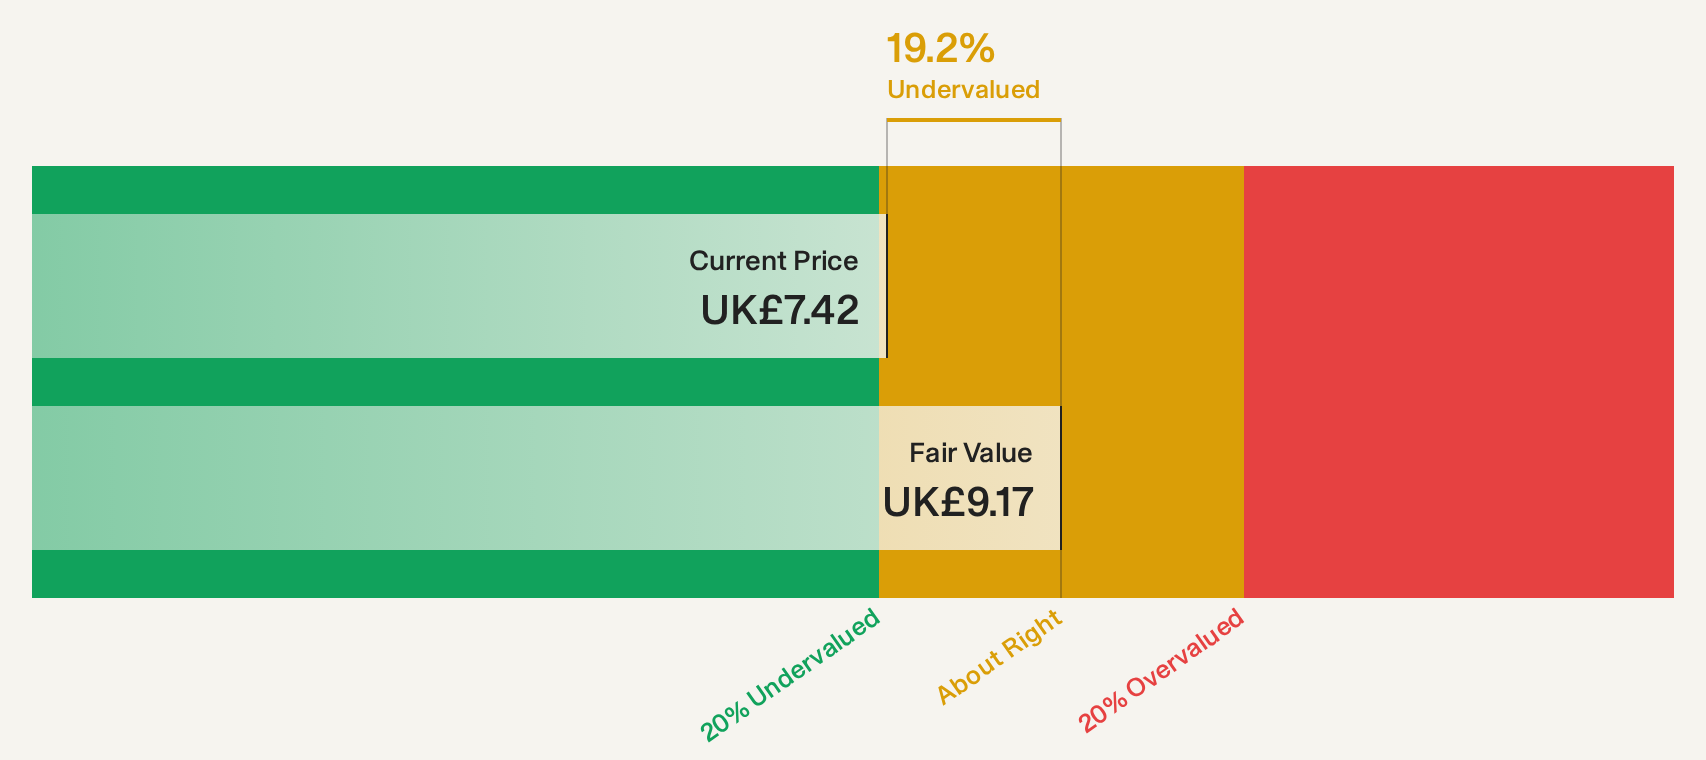
Estimated Discount To Fair Value: 16.4%
Howden Joinery Group is trading at £7.68, below its estimated future cash flow value of £9.18, highlighting potential undervaluation based on cash flows. Recent earnings reports show stable performance with sales reaching £1.03 billion and net income slightly declining to £88 million. Analysts agree on a 31.3% potential stock price rise, although earnings growth forecasts of 8.2% per year trail the UK market average of 11.1%. The dividend track record remains unstable despite a recent increase in payouts.
- Our growth report here indicates Howden Joinery Group may be poised for an improving outlook.
- Click here and access our complete balance sheet health report to understand the dynamics of Howden Joinery Group.
Summing It All Up
- Click here to access our complete index of 27 Undervalued UK Stocks Based On Cash Flows.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com