
Elite Undervalued Stocks To Watch In October 2026
The IMF is warning that heavy government borrowing and rising bond yields could strain markets, which puts more pressure on investors to be selective about what they own. When funding costs climb, businesses with solid, visible cash coming in can appear especially appealing if their share prices still lag their underlying value. This article highlights three such cash focused stocks that screen as potentially mispriced today.
The three stocks below are just a starter set. The full screen on Simply Wall St surfaces 460 more companies with similarly cash rich stories and pricing that still looks out of sync with their estimated fair value. To go straight to the source and identify, compare, and analyze your own shortlist of ideas, head into the Undervalued Stocks Based On Cash Flows screener.
NVIDIA (NVDA)
Overview: NVIDIA builds AI focused data center platforms and graphics chips that power cloud computing, gaming, professional visualization, and automotive systems.
Operations: NVIDIA generates about US$275.4b from Compute & Networking and US$27.6b from Graphics, with most revenue from the United States and Taiwan.
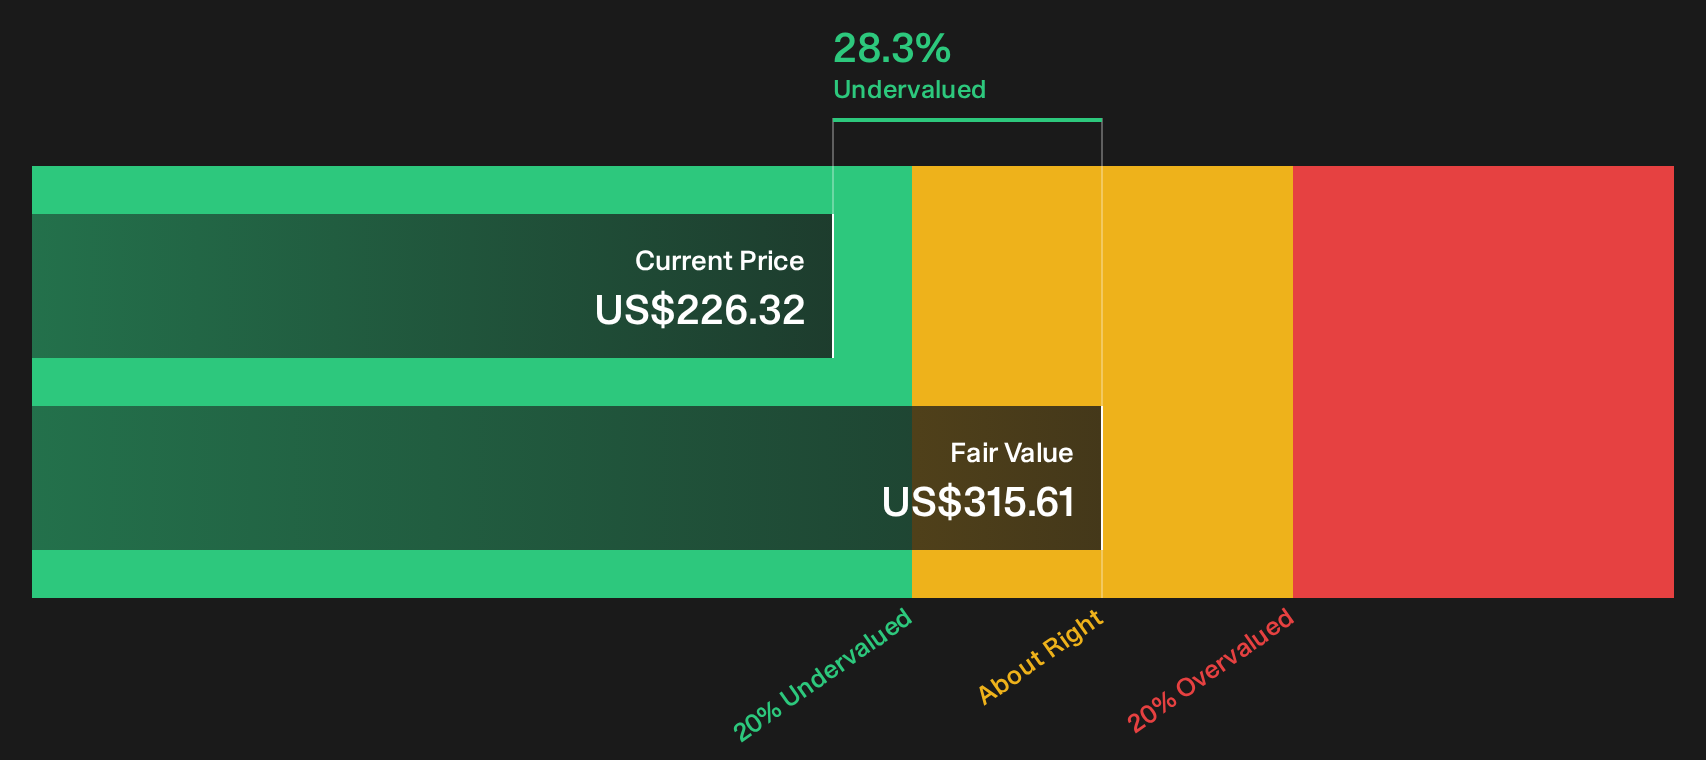
Market Cap: US$5,464.9b
NVIDIA matters for this screener because its AI data center hardware and software turn massive compute demand into fee like cash flows that the valuation model still treats cautiously.
"Main challenges for achieving these targets: • $400b annual revenue assumes Nvidia continues to be dominant in GPU design and AI software stack. Successful competition from AMD, Intel, or a Chinese firm could undermine this."
What happens to those rich data center economics if a single unseen pressure starts to weaken the pricing power behind them?
If that pricing power question is on your mind, read the full narrative for NVIDIA to see how NVIDIA’s moat, cash engine, and competitor risk fit together.
Alphabet (GOOGL)
Overview: Alphabet runs Google Search, YouTube, Android, and Google Cloud, where AI driven infrastructure and software subscriptions underpin recurring enterprise cash flows.
Operations: Alphabet generates about US$367.1b from Google Services, US$77.6b from Google Cloud, and US$1.5b from Other Bets, mainly across the United States and EMEA.
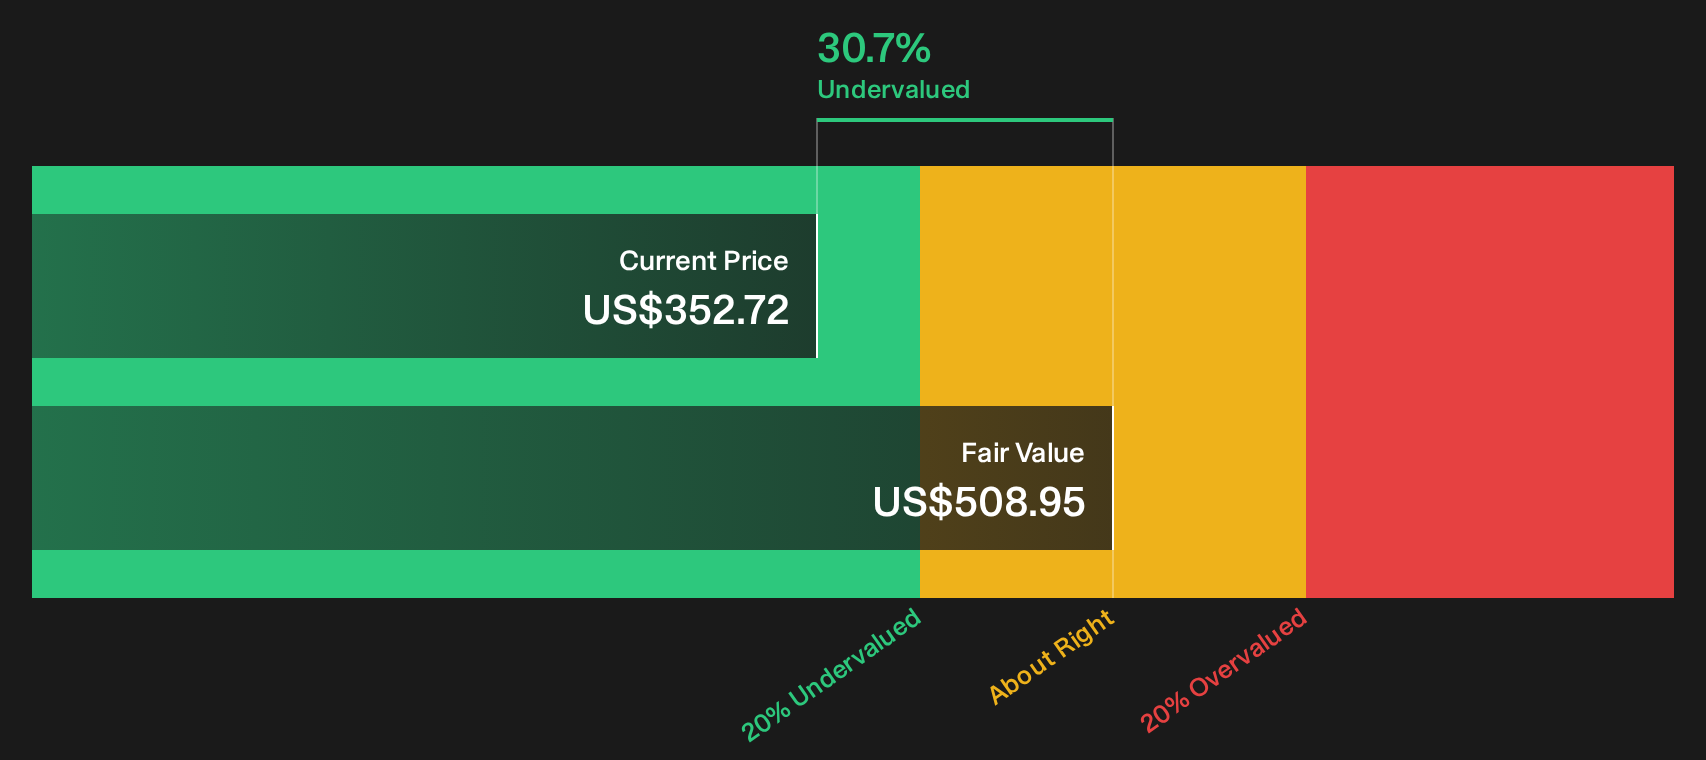
Market Cap: US$4,293.0b
Alphabet matters for this cash flow focused screen because Google Cloud’s AI and infrastructure stack turns long-term enterprise contracts into subscription style inflows that DCF models treat as central to the valuation gap.
"Google Cloud has gone from “meh” to money-maker. • Now #3 globally behind AWS and Azure, with over 11% market share."
The durability of that AI heavy cloud backlog, if a single assumption about enterprise spend shifts, could reshape both margins and perceived fair value.
If that shift is what you are weighing, the full narrative for Alphabet outlines how Alphabet’s cash engine, AI bets, and risk factors could be changing expectations.
Yadea Group Holdings (SEHK:1585)
Overview: Yadea Group Holdings designs, manufactures, and sells branded electric scooters, bicycles, and related accessories across China and selected export markets.
Operations: Yadea Group Holdings generates about CN¥34.1b from electric two-wheeled vehicles and accessories and CN¥7.7b from batteries and electric drives, almost entirely in China.
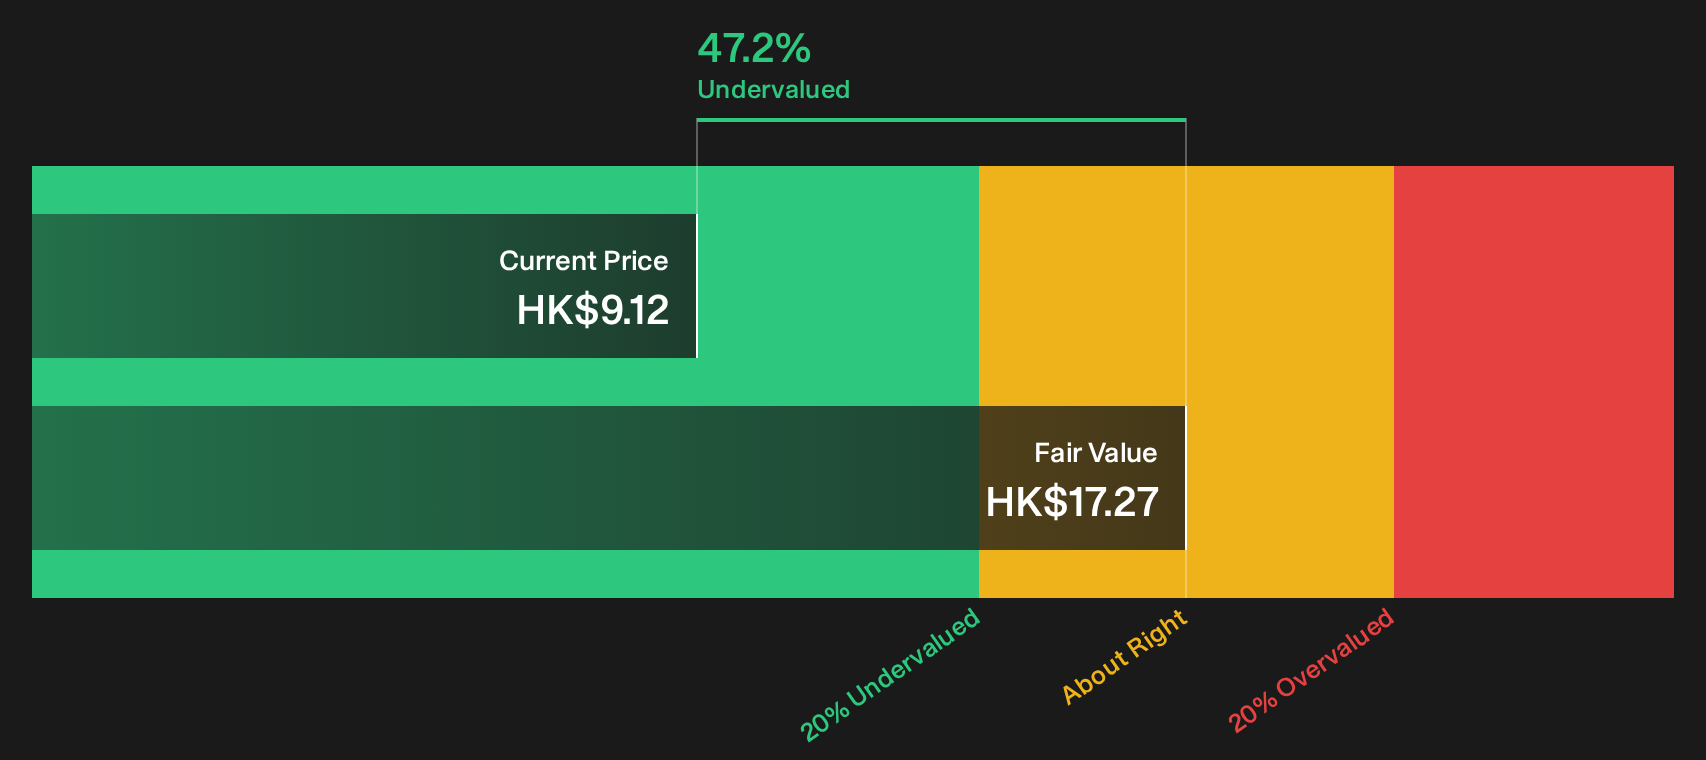
Market Cap: HK$27.8b
Yadea Group Holdings is linked to the undervalued cash flow theme through its large electric scooter and bike franchise. Branded demand, a forecast 16.39% earnings growth rate, and a P/E around 9.6x sit alongside an SWS DCF value that screens higher than the share price. The key variable is how any pressure on EV demand and pricing affects margins.
If that margin squeeze risk is what you are weighing, go straight to the 4 key rewards and 1 important warning sign to see how Yadea Group Holdings’ cash strength and pressure points line up.
Seeking Fresh Alternatives Before Others Do
New ideas move first, prices move next. Fresh candidates can build breakout momentum while old stories get caught dropping. Scan what is still under the radar for now and act now.
- Spot cash rich leaders quietly building momentum and run them through the 20 high quality undiscovered gems while that edge still belongs to early movers.
- Target durable income streams by scanning the 8 dividend fortresses that focus on high yields backed by balance sheets built to handle rougher markets.
- Ride the AI build out with the 92 AI infrastructure stocks before infrastructure demand shifts from “emerging theme” to fully priced expectation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com