
How Investors Are Reacting To Wintrust Financial (WTFC) Higher Earnings Estimates
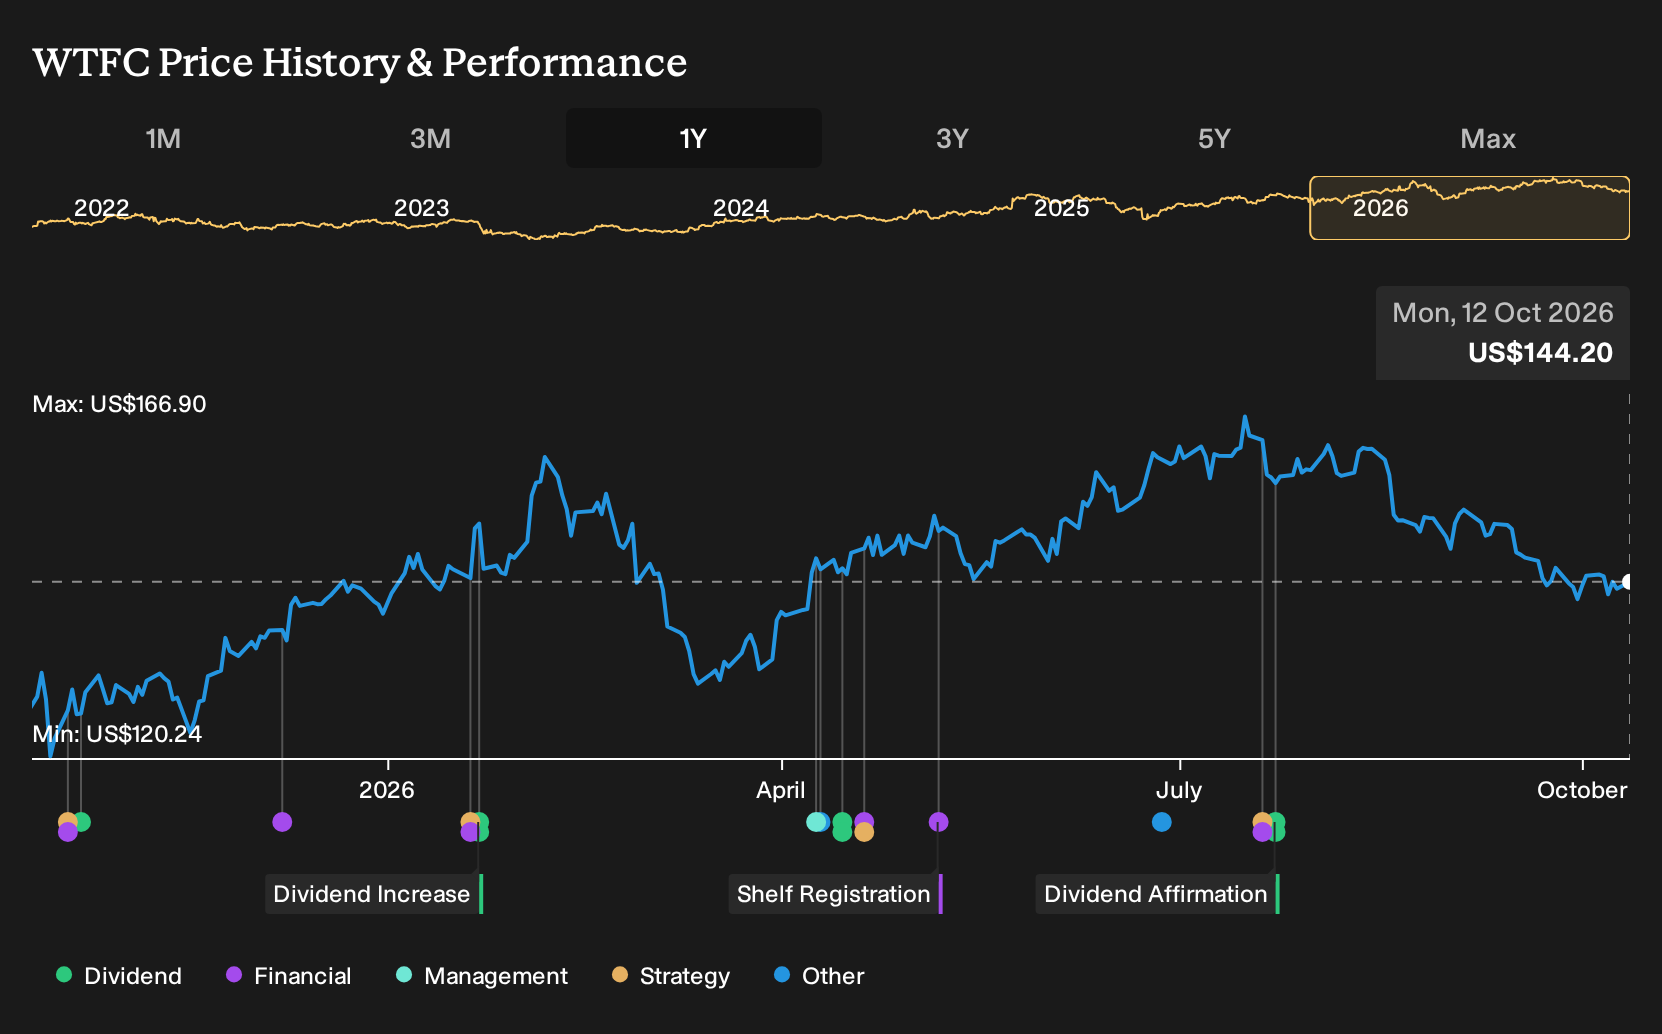
- Wintrust Financial is heading into its September 2026 quarter update with analysts projecting higher earnings on increased revenue, supported by positive estimate revisions in recent weeks.
- The key shift is growing confidence that Wintrust Financial’s lending and fee businesses can support stronger quarterly profitability despite earlier margin pressure.
- We will now look at how this rising earnings optimism could reshape Wintrust Financial’s investment narrative around core profitability drivers.
Scan 29 high quality undervalued stocks that pair stronger earnings momentum with sturdier margins than Wintrust Financial so you can compare this setup against other potential breakout candidates.
Wintrust Financial Investment Narrative Recap
To own Wintrust Financial, you need to believe its community banking, specialty finance and wealth businesses can keep turning a growing base of loans and deposits into solid earnings, even as net interest margin feels pressure. The short term swing factor is whether upcoming quarters show that margin stabilising alongside steady credit quality.
The biggest risk right now is that competition in commercial and commercial real estate lending, plus repricing in premium finance, keeps squeezing loan yields while expenses stay elevated from technology and branch investment. Recent earnings optimism does not erase that risk, but it could soften the impact if fee income and volumes hold up.
The most relevant recent development is the expectation that Wintrust Financial will report higher earnings on increased revenue for the September 2026 quarter, with several analysts raising near term estimates. This is where you see whether the bank’s lending and fee engines are offsetting the reported net interest margin contraction.
If the update confirms revenue growth across community banking and specialty finance, it would support the idea that organic volume and noninterest income can shoulder more of the load while margins stay under pressure. If net interest margin or credit costs surprise negatively instead, the risk side of the story around pricing competition and commercial real estate exposure moves back into focus.
Wintrust Financial's narrative projects US$3.5b revenue and US$1.1b earnings by 2029. This is based on an assumption of 8.6% yearly revenue growth and an earnings increase of about US$252.1m from current earnings of US$847.9m.
Uncover why Wintrust Financial's fair value indicates a 22% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$153.55 to about US$229.43, so retail views on Wintrust Financial’s upside vary sharply. Use that spread as a reference point and weigh it against risks around loan pricing pressure, higher tech spending and the upcoming September 2026 earnings catalyst.
Explore 2 other Wintrust Financial fair value estimates, including one that suggests as much as 59% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Wintrust Financial research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wintrust Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wintrust Financial's overall financial health at a glance.
Looking For More Ideas Beyond Wintrust Financial?
Once you have formed a view on Wintrust Financial, it can help to compare that thesis with other stocks that have different strengths but similar risk profiles, so you can see where the best trade offs might lie for your portfolio.
- For investors hunting for smaller companies with room to develop and stronger balance sheets, scan the 11 elite penny stocks with strong financials that pass the Simply Wall St filters for financial quality.
- If you want potential value with some built in resilience, sort through the 31 resilient stocks with low risk scores to see which stocks pair steadier risk scores with fundamentals you are comfortable owning.
- To widen your watchlist with companies that have solid finances but receive less attention, review the 20 high quality undiscovered gems and see which under the radar ideas best complement your view on Wintrust Financial.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com