
Cytokinetics (CYTK) Stock Leaves Valuation Questions Open As MYQORZO Sales Impress
Cytokinetics shares have climbed 81.2% over the past three years, helped by momentum around its heart drugs, which raises a clear question for investors. Is the current US$62.79 price meaningfully supported by what the company has built up on its balance sheet, especially its book value?
- An 81.2% three year gain puts past buyers in a strong position. However, it also places more emphasis on whether that move lines up with the underlying equity on the balance sheet.
- Recent traction for MYQORZO and positive late stage data for aficamten may support expectations for future cash generation, which matters for how much of a premium or discount investors are willing to place on Cytokinetics' net assets.
- The analysts covering Cytokinetics have run their own numbers. See what analysts think Cytokinetics's shares could be worth.
The issue now is whether that share price can be squared with Cytokinetics' book value once you set the recent performance and drug news to one side and focus on the balance sheet.
If you want more than one heartbeat stock in your watchlist, a focused screen of 33 healthcare AI stocks is a clear way to find other health technology names to research.
Where Does Cytokinetics Sit on Book Value?
P/B is usually a clean way to gauge what you are paying for each dollar of net assets, which matters a lot for a research heavy biotech like Cytokinetics.
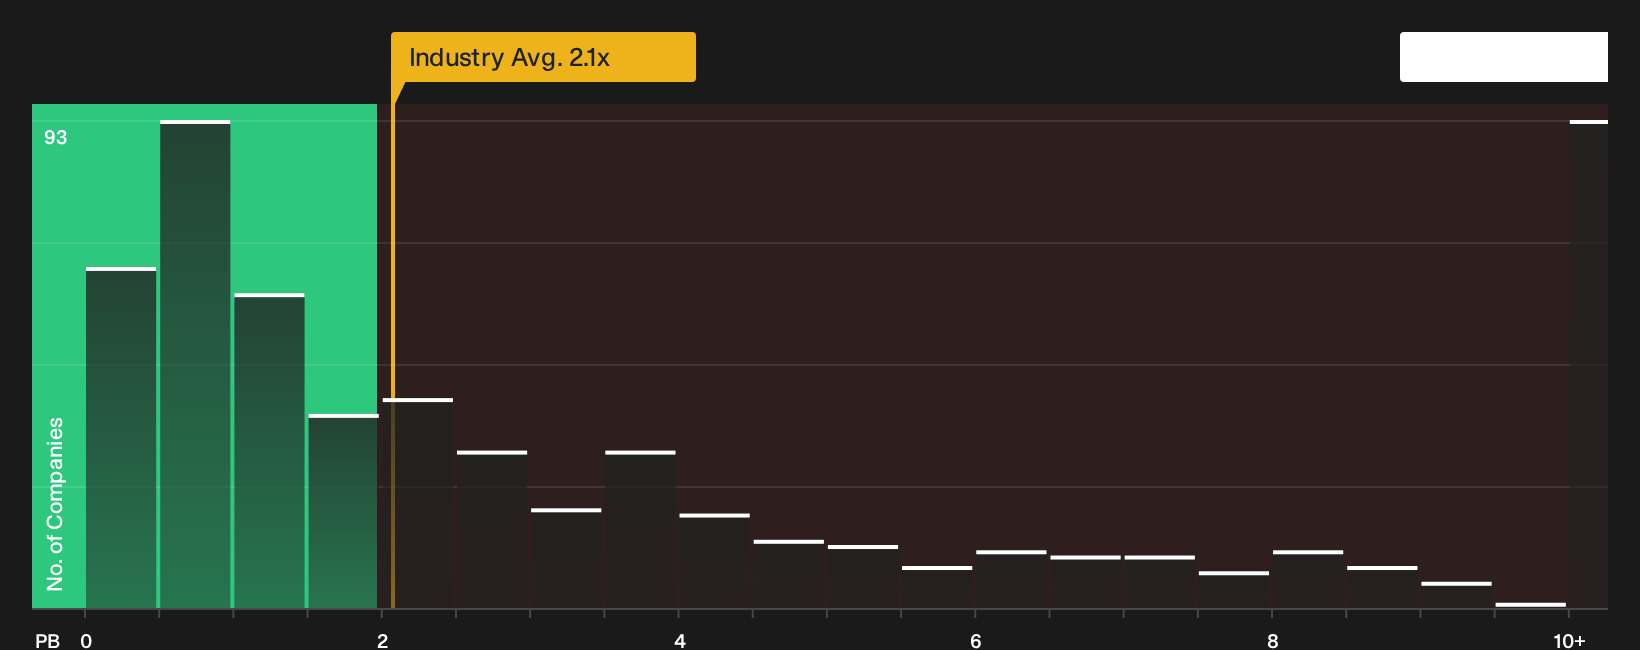
Right now Cytokinetics trades on a P/B of 50.3x, but that figure is negative because the company reports negative shareholder equity. That means there is no positive asset base for the ratio to anchor to, so the multiple itself does not give a useful read on whether the shares are expensive or cheap relative to the balance sheet. Because the stock cannot be framed against a stable equity value, you have to rely much more on expectations around the pipeline and future cash flows when judging the current price, including how investors weigh the recent MYQORZO sales and aficamten trial news against the ongoing losses that drove equity below zero. With this multiple ruled out, take a closer look at what Cytokinetics's balance sheet and debt position show instead.
The Cytokinetics Narrative: What Would Justify Today's Price?
Narratives for Cytokinetics pick up exactly where the book value puzzle leaves off. They spell out which assumptions on future growth, profitability and earnings would need to hold for the share price to sit meaningfully above or below today's level, and they sit on Simply Wall St's Community page. Each narrative treats fair value as a thesis about Cytokinetics' business that you can track over time, rather than a one off snapshot.
One of the top community narratives on Cytokinetics: 42% undervalued
"Commercial launch readiness for aficamten is progressing with a newly hired, experienced cardiovascular salesforce in the U.S. and tailored strategies for Europe..."
Discover why this Narrative puts Cytokinetics at 42% undervalued.
One more angle on Cytokinetics that should not be skipped
Before moving on from Cytokinetics, it is worth knowing that Simply Wall St’s broader checks have highlighted specific areas of concern that some investors may want to examine closely. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com