
Does Board Shake Up Change The Bull Case For Hub Group Stock (HUBG)?
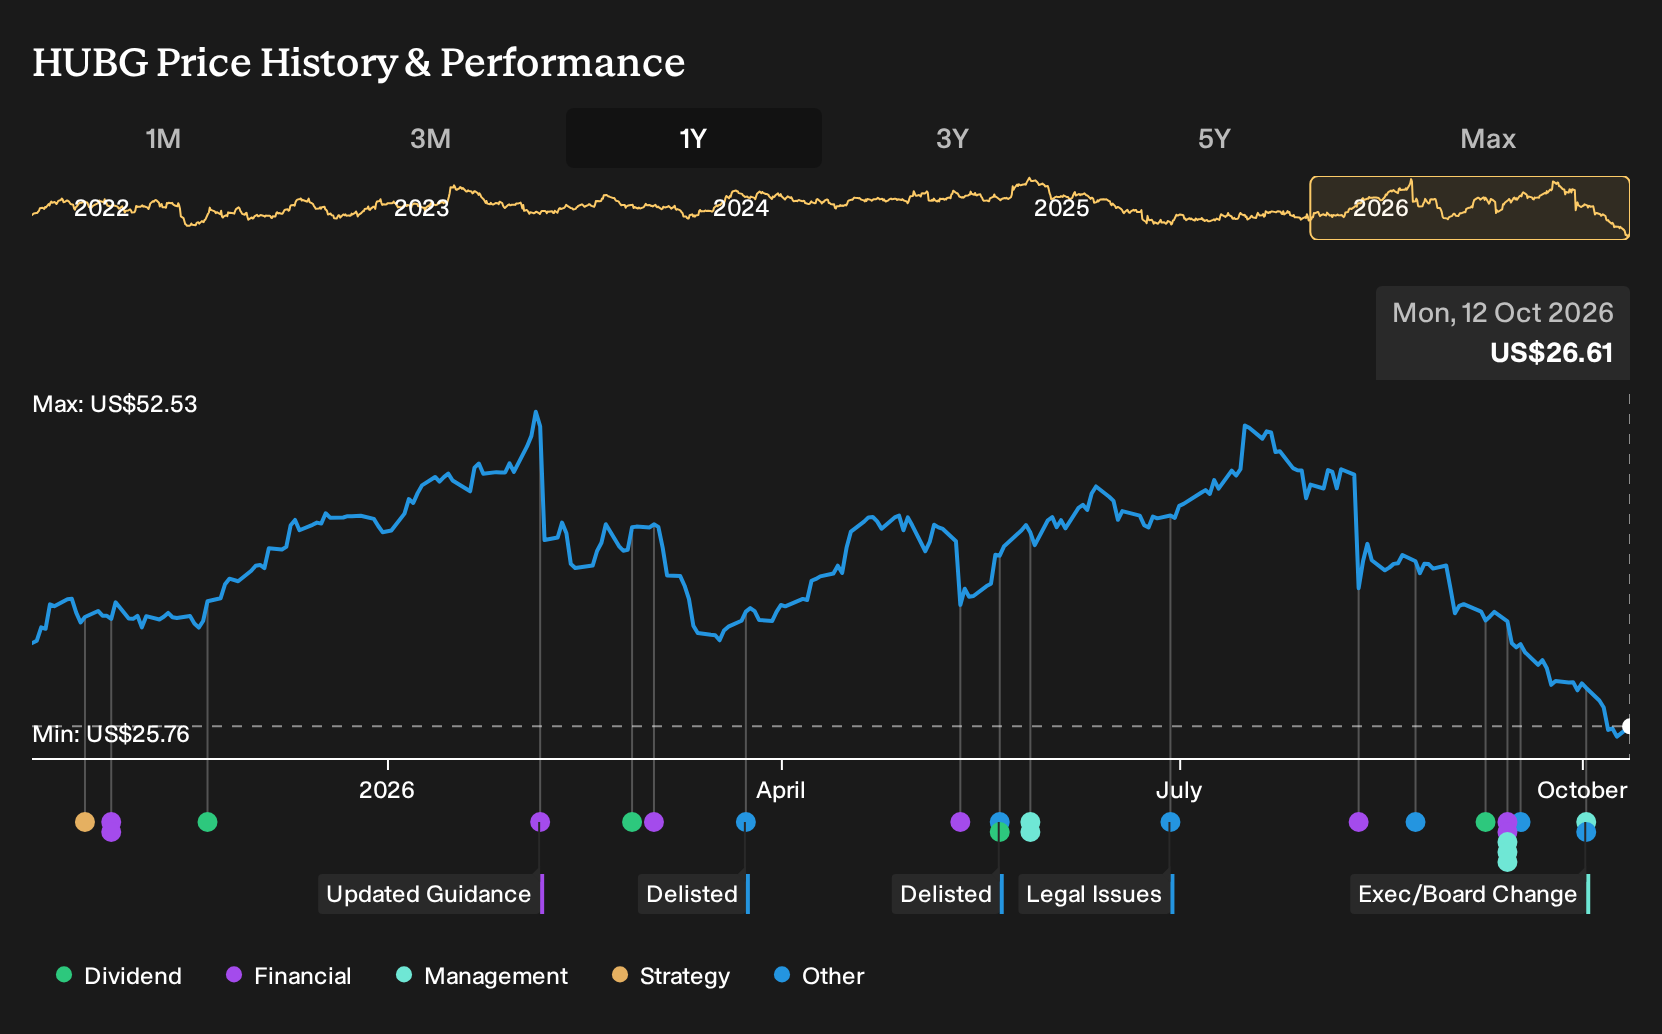
- In early October 2026, Hub Group overhauled its governance by removing three directors without cause through stockholder consent, accepting three additional resignations, appointing four new directors with deep legal, academic, and operating backgrounds, and adopting second amended and restated bylaws.
- The refreshed board includes a former Hub Group CFO, a long-tenured M&A attorney, and a Chicago Booth entrepreneurship professor, which indicates a sharper focus on transactions, capital allocation, and business model execution rather than incremental adjustments to existing operations.
- Attention now turns to how Hub Group's refreshed board and new bylaws could influence the investment narrative and future governance direction.
What Is Hub Group's Investment Narrative?
Owning Hub Group means buying into a fairly asset heavy logistics platform, with intermodal, trucking and third party logistics under one roof. The core belief is that management can keep those containers, tractors and drivers busy enough, at disciplined pricing, to turn a 2.8% net margin into something that justifies tying up capital in fleets and equipment. Recent share performance has been weak, which puts more pressure on execution and contract quality rather than blue sky narratives about volume.
The sweeping board and bylaw reset plugs directly into those near term issues. A fresh mix of legal, deal and operating experience can influence how Hub Group pursues M&A, allocates cash between fleets and technology, and balances contracts against spot exposure. The catalyst, if any, comes from sharper decisions around capital intensity and returns. The risk is that such rapid governance change distracts leadership right when the logistics cycle and customer budgets are already demanding tight execution.
Even so, there is one structural pressure point in the Hub Group story that could still upset this thesis if ...
There's only one way to know the right time to buy, sell or hold Hub Group. Head to Simply Wall St's company report for the latest analysis of Hub Group's Fair Value.
Exploring Other Perspectives
Some of the most optimistic Hub Group analysts were leaning hard into a catalyst that now looks very exposed. They were assuming revenue growth of 6.2% a year and earnings of US$171.3 million by about 2029, backed by operational gains. You might read this board shake up and wonder whether that story now needs a rewrite.
Explore 2 other Hub Group fair value estimates, including one that suggests as much as 342780% upside from the current price!
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hub Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Hub Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hub Group's overall financial health at a glance.
Looking for more investment ideas beyond Hub Group?
Once you have a view on Hub Group, it often helps to widen the search and see how other businesses line up on quality, value, and resilience using the Simply Wall St Screener.
- If you want potential upside but still care about balance sheet strength, scan a 20 high quality undiscovered gems that pair solid finances with less crowded ownership.
- For readers who want to prioritize capital preservation first, filter for 32 resilient stocks with low risk scores that score well on stability and business risk.
- If steady income is your focus, check companies that have historically shared more cash with investors by reviewing 8 dividend fortresses offering higher yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com