
Sat Out Gilead Sciences' Rally? Here Is What Holders Saw
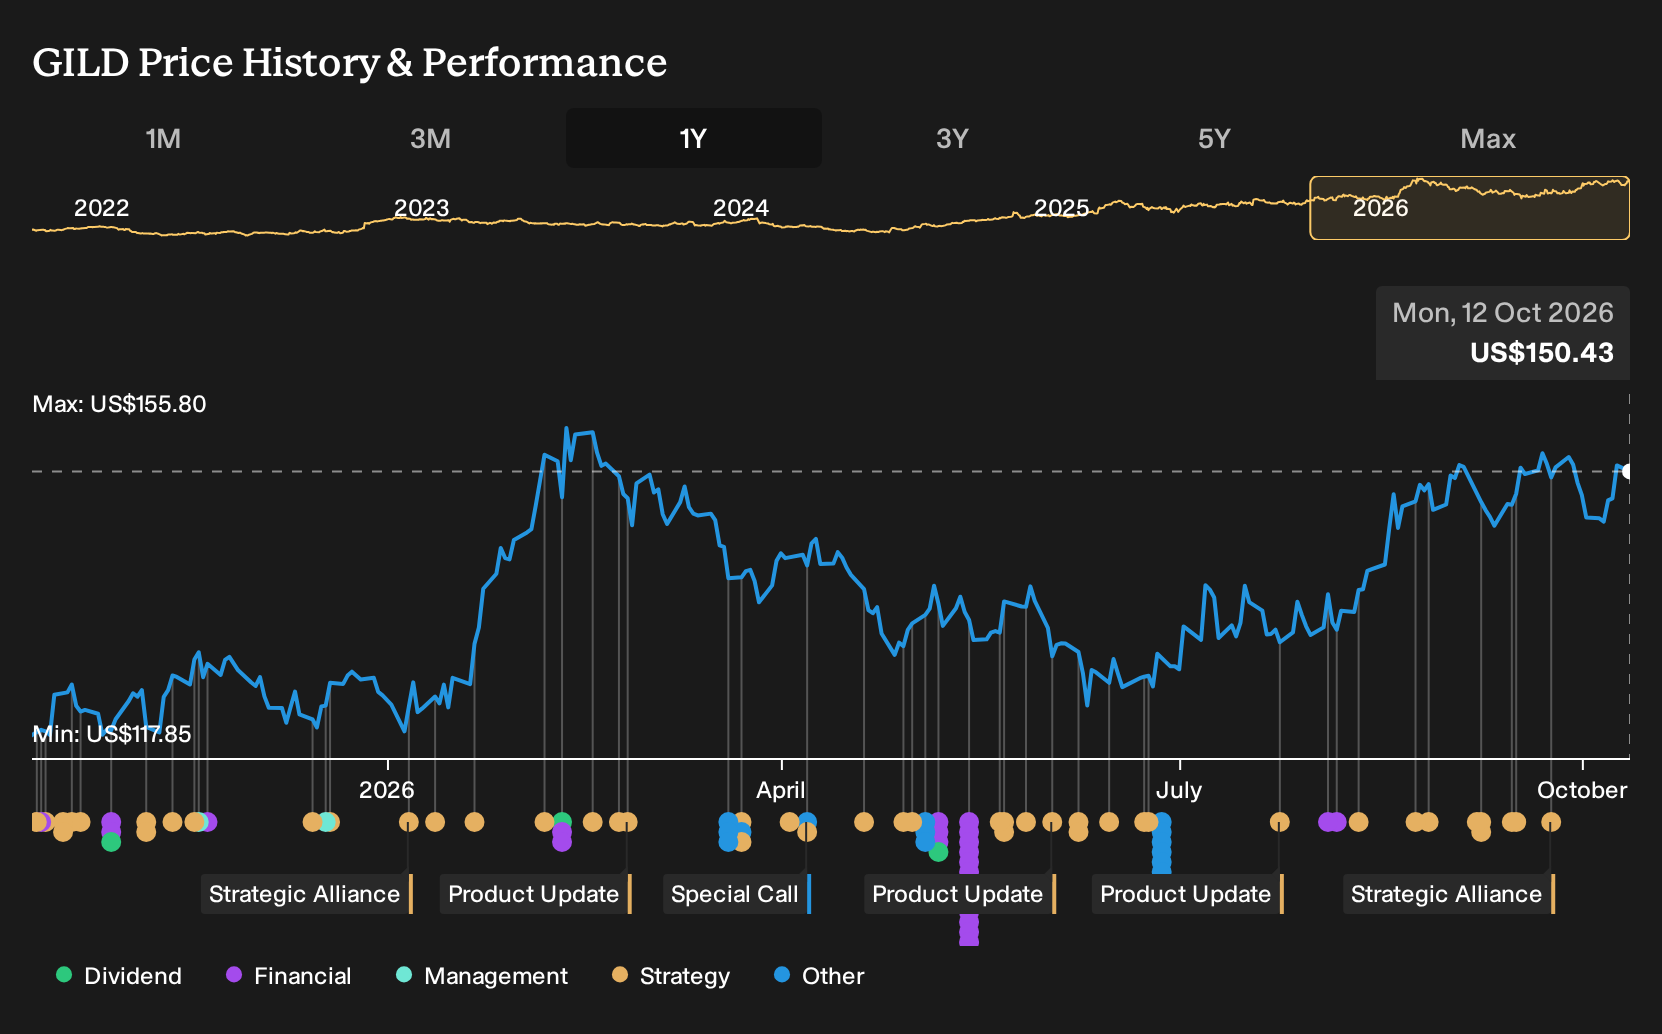
If Gilead Sciences was on your watchlist instead of in your portfolio, the gap may feel a bit raw. For Gilead Sciences shareholders, the return over the past year was 30.4%, including dividends. That outcome forces a simple question. Back on 12 October 2025, when analysts were arguing over whether modest revenue growth and fatter profit margins could justify a higher future P/E, what signals were already on record that this business mix shift might matter more than the policy and patent worries?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Gilead Sciences has already moved. Pinpoint other ways to investigate the theme among 33 healthcare AI stocks.
The Two Gilead Sciences Stories Investors Had To Weigh
The shares cost US$117 at the start of the period, and Gilead Sciences sat between two very different stories about where its mix of HIV, oncology and newer therapies might head next.
On the optimistic side, one narrative put Fair Value at US$125, or 7% above the start price. This view hinged on revenue growth of 3.8% a year and profit margins reaching 31.0% within three years.
The cautious view set Fair Value at US$91, or 22% below the start price. It stressed risks from Medicare Part D redesign that could leave HIV sales flat and keep overall revenue progress muted.
What The Evidence Did To The Gilead Sciences Story
The completion of the Tubulis and Arcellx acquisitions, plus FDA and European approvals that broadened Trodelvy and Hepcludex use, clearly leaned toward the optimistic Gilead Sciences case about a richer oncology and liver mix. The hard check came from Q2 2026, where revenue reached US$7,803m yet net income swung to a US$10,496m loss and net margin fell to 134.5% in the red. The evidence cut both ways.
The lesson is simple. When a thesis leans on higher future profitability, do not stop at new products and deals. Track whether net margin, not just sales, is moving toward the promised level in each quarterly report.
What Today's Gilead Sciences Price Already Assumes
Gilead Sciences now trades at US$150, up from US$117 over the past year. The selected Narrative places its Fair Value below that level and argues that the current quote already builds in a stronger earnings profile than recent history alone might justify.
The question for anyone paying today is what must keep going right for that to hold. The specific hurdle is whether heavy spending on HIV prevention, oncology and cell therapy genuinely turns into products that offset policy and pricing pressure on the existing virology base.
"The main thing that has to go right is for Gilead Sciences to convert its heavy R&D and deal spending into commercially successful products in oncology, cell therapy, and inflammation that can offset policy pressure and competition in HIV and hepatitis C."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 27% below our estimate - uses a super app and credit models to expand secured lending while managing default risk.
- Company 2 - 31% below our estimate - scales branded and private label coconut beverages while containing packaging and freight expenses.
- Company 3 - 34% below our estimate - advances late stage therapies for kidney, blood and endocrine conditions beyond its initial specialty.
Those are three of them. See every one of the 29 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com