
What TFI International Doubters Overlooked
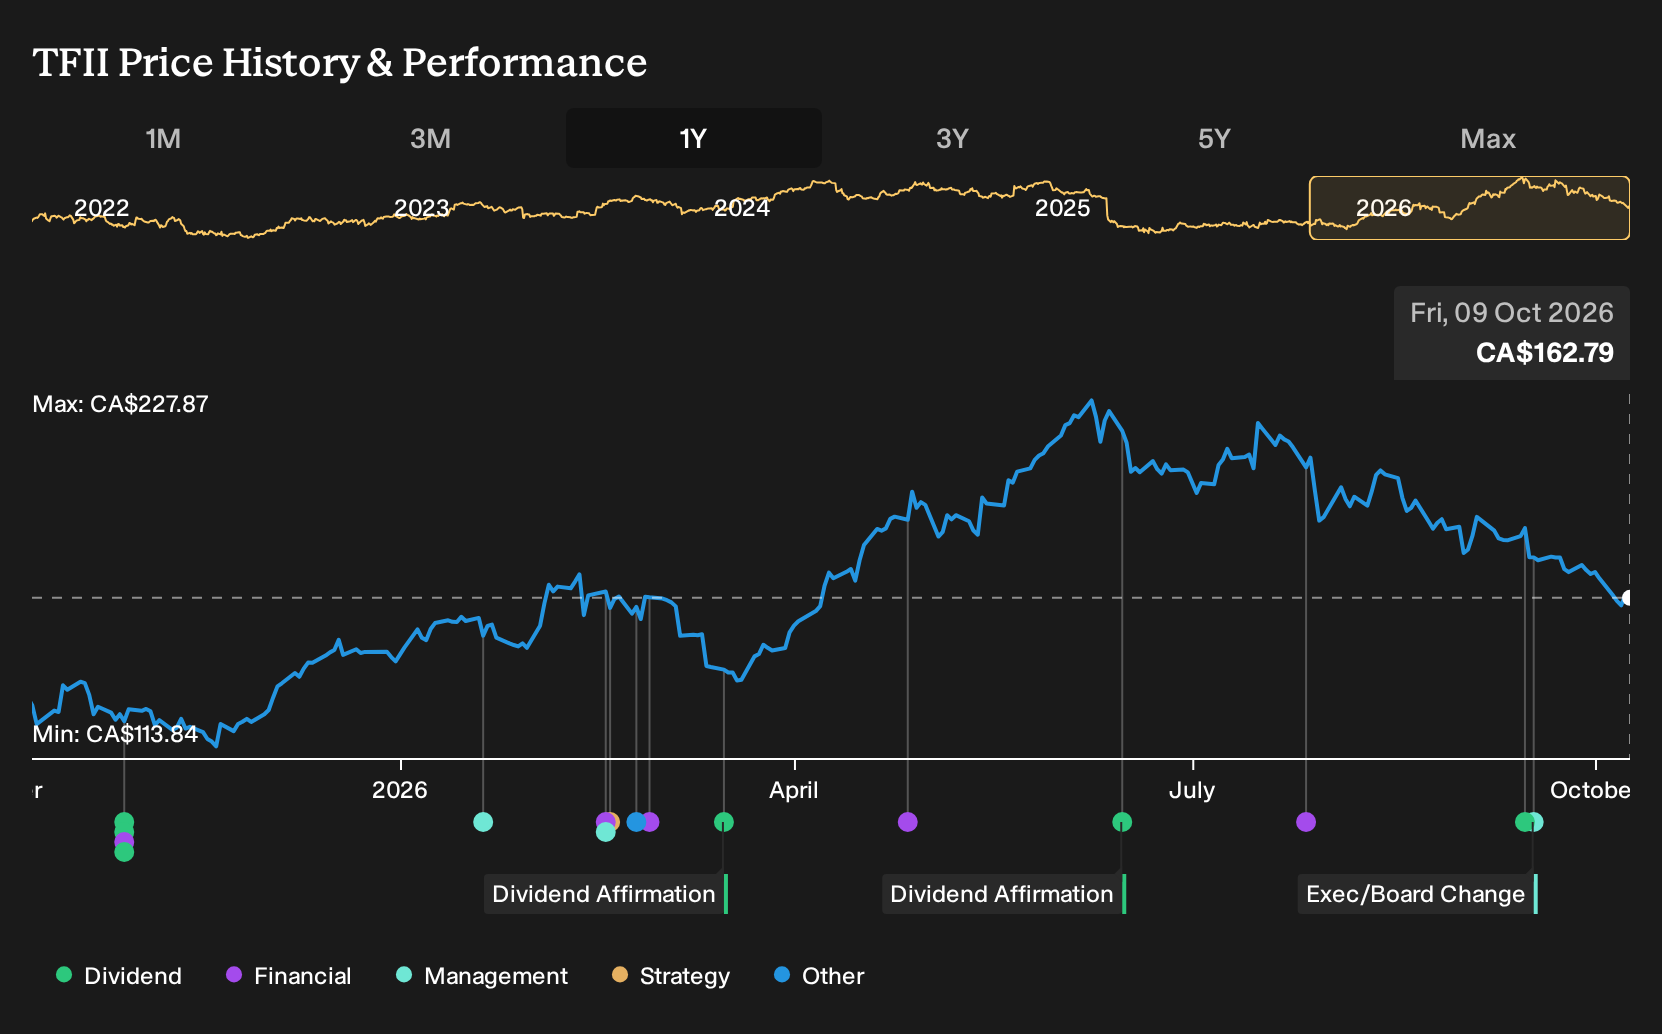
For TFI International shareholders, the return over the past year was 36.5%, including dividends. If you had been weighing a purchase back on 9 October 2025, you would have seen analysts split between a bullish case tied to cross border freight and efficiency gains, and a bearish view focused on disruption and decarbonization costs. With that outcome now on the table, which of those early concerns and hopes deserved more weight at the time?
If the move has made TFI International harder to judge, start where the gap is still open and scan 8 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On TFI International
The shares cost CA$127 at the start of the period, and investors in TFI International were really choosing between two clear stories about where the business might head next.
On the bullish side, the Cross-Border Freight And Digital Efficiency narrative argued that a Fair Value of CA$141, a price implied by its assumptions, was reasonable. That view leaned on revenue rising 3.6% a year and profit margins reaching 6.1% within three years.
The bearish Autonomous Vehicles And Decarbonization Costs story pointed to a Fair Value of CA$96.4 and warned that new logistics technology could shrink traditional freight volumes. It also stressed that decarbonization rules might require heavy spending on the fleet.
What The Results Changed For TFI International
The key development for TFI International was the Q2 2026 report. Revenue reached US$2.29b and net income was US$136.2m, with the net margin at 5.9% compared with 4.8% a year earlier. That pattern supported the efficiency-focused bull story more than the disruption-focused bear case, although LTL margin pressure in the news kept some of the cautious thesis alive. Overall, the evidence cut both ways.
The useful lesson is where to look. When a thesis leans on better efficiency and pricing, it can be helpful to track net margin and segment operating ratios against the original forecast, rather than focusing only on headline revenue or the share price.
What TFI International's Price Now Assumes
TFI International now trades at CA$163 after a 36.5% gain over the past year. This Narrative’s Fair Value sits above the current price, based on how its freight mix, LTL turnaround work and logistics projects are shaping margins and returns.
The Narrative suggests the market price still does not fully credit sustained free cash flow deployment into higher return truckload niches, U.S. LTL improvements and Logistics scale.
"The main requirement is that TFI International continues to execute on higher return, asset light truckload niches, the U.S. LTL turnaround, and the growth of its Logistics and value added services so that margins and returns on invested capital remain aligned with management's long run targets."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 23% below our estimate - focuses on expanding boutique footprint and modernizing online experience to boost engagement.
- Company 2 - 34% below our estimate - ramps advanced networking and AI-focused hardware programs for major infrastructure customers.
- Company 3 - 25% below our estimate - uses a profitable high-margin mine to finance drilling of nearby targets.
That is three of the list. See all 7 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com