
3 Asset Managers With AI Funding Exposure as Higher Yields Test Fee Resilience
Bond yields are grinding higher, AI data centers are soaking up capital, and funding costs are no longer an abstract risk on a slide deck. That mix is reshaping which asset managers and private credit lenders can turn this funding wave into durable fee income and which could feel squeezed as money gets pricier. This article walks through three stocks exposed to that news backdrop and what their setups might mean for your portfolio decisions.
The three stocks covered below are only a sample of this theme, and the full screen surfaced 16 more medium to large cap asset managers and private credit lenders with equally compelling narratives that are not unpacked in this article. To see the full picture, head into the Asset Managers and Private Credit Lenders Financing AI and Infrastructure Capex screener to analyze balance sheets, compare risk profiles, and identify which funding models best fit your own conviction level.
Mercia Asset Management (AIM:MERC)
Overview: Mercia Asset Management is a UK-based private equity and venture capital group providing venture debt, loans and mezzanine financing to high-growth companies.
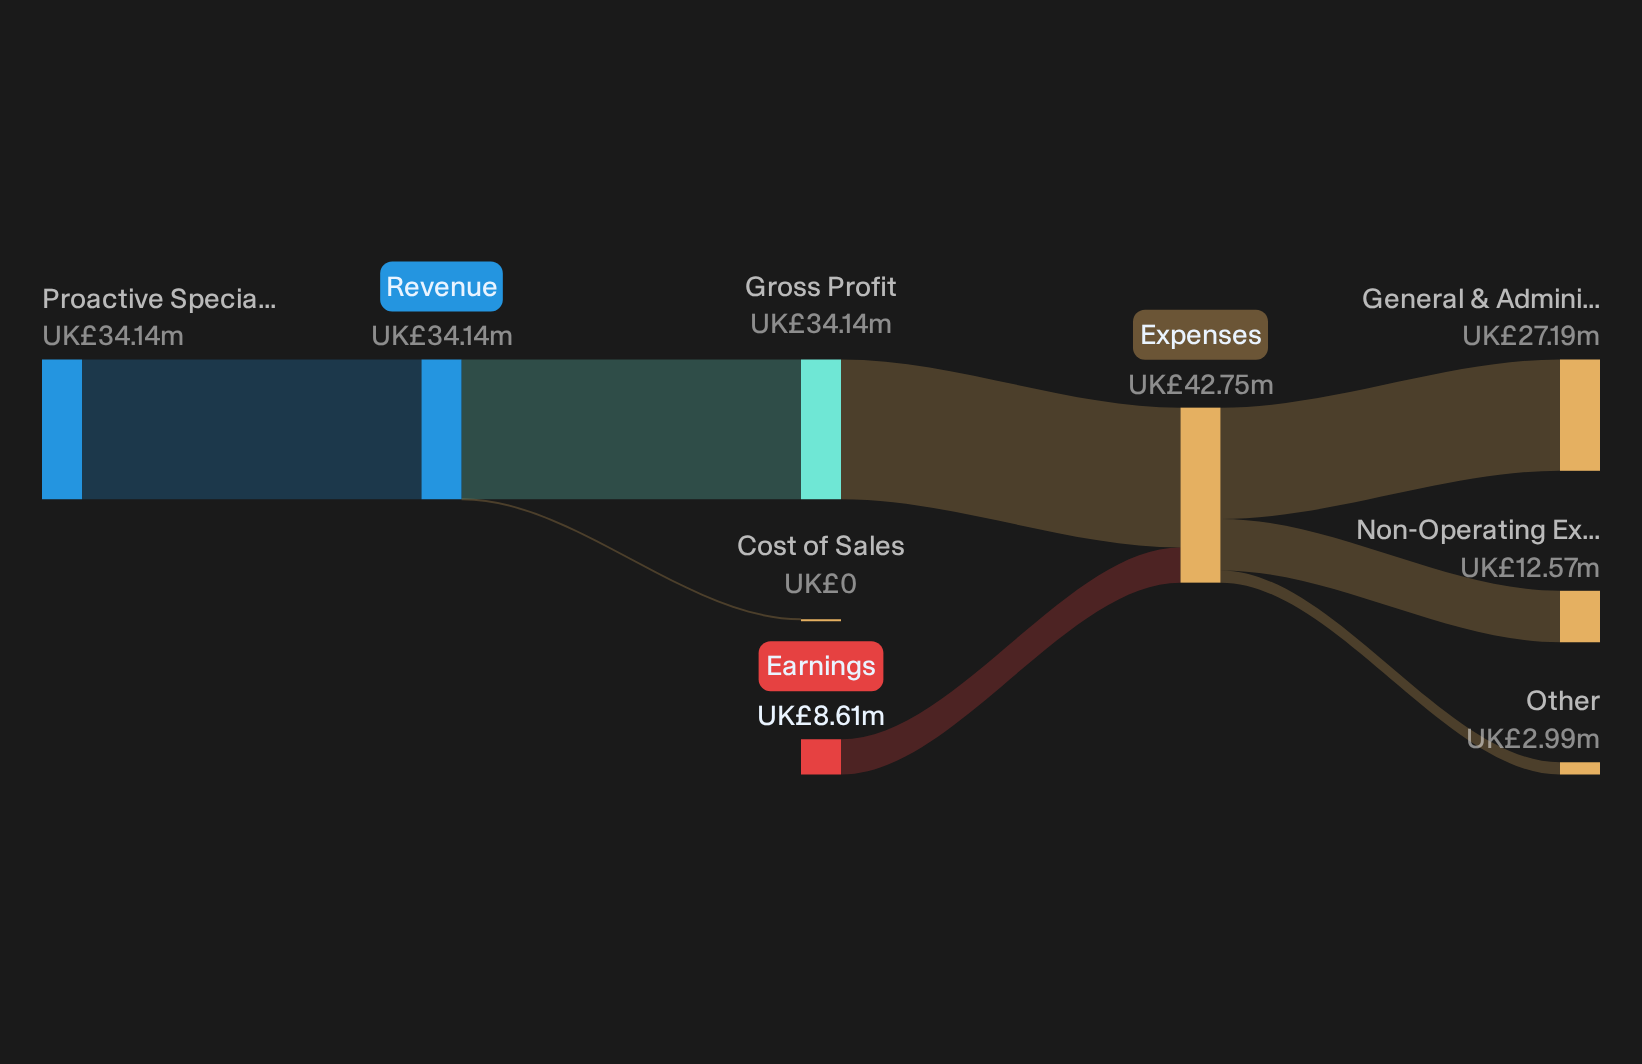
Operations: Mercia generates about £34 million of revenue from proactive specialist asset management activities, entirely sourced from clients and investments in the United Kingdom.
Market Cap: £129 million
Mercia Asset Management gives you direct exposure to private-credit style venture debt and mezzanine lending that can support AI and infrastructure capex, backed by a new three-year borrowing facility with Metro Bank that expands its lending firepower. The key question is how that externally funded growth affects returns once one unseen pressure on its funding costs fully feeds through to margins.
As that margin risk builds, review the 2 key rewards and 1 important major warning sign to see how Mercia Asset Management’s funding structure could amplify both upside and pressure on returns.
Acadian Asset Management (AAMI)
Overview: Acadian Asset Management Inc. is a Boston based asset manager allocating client capital across equities, fixed income, alternatives, and quantitative strategies, including potential exposure to private credit and infrastructure debt linked to AI and data center financing.
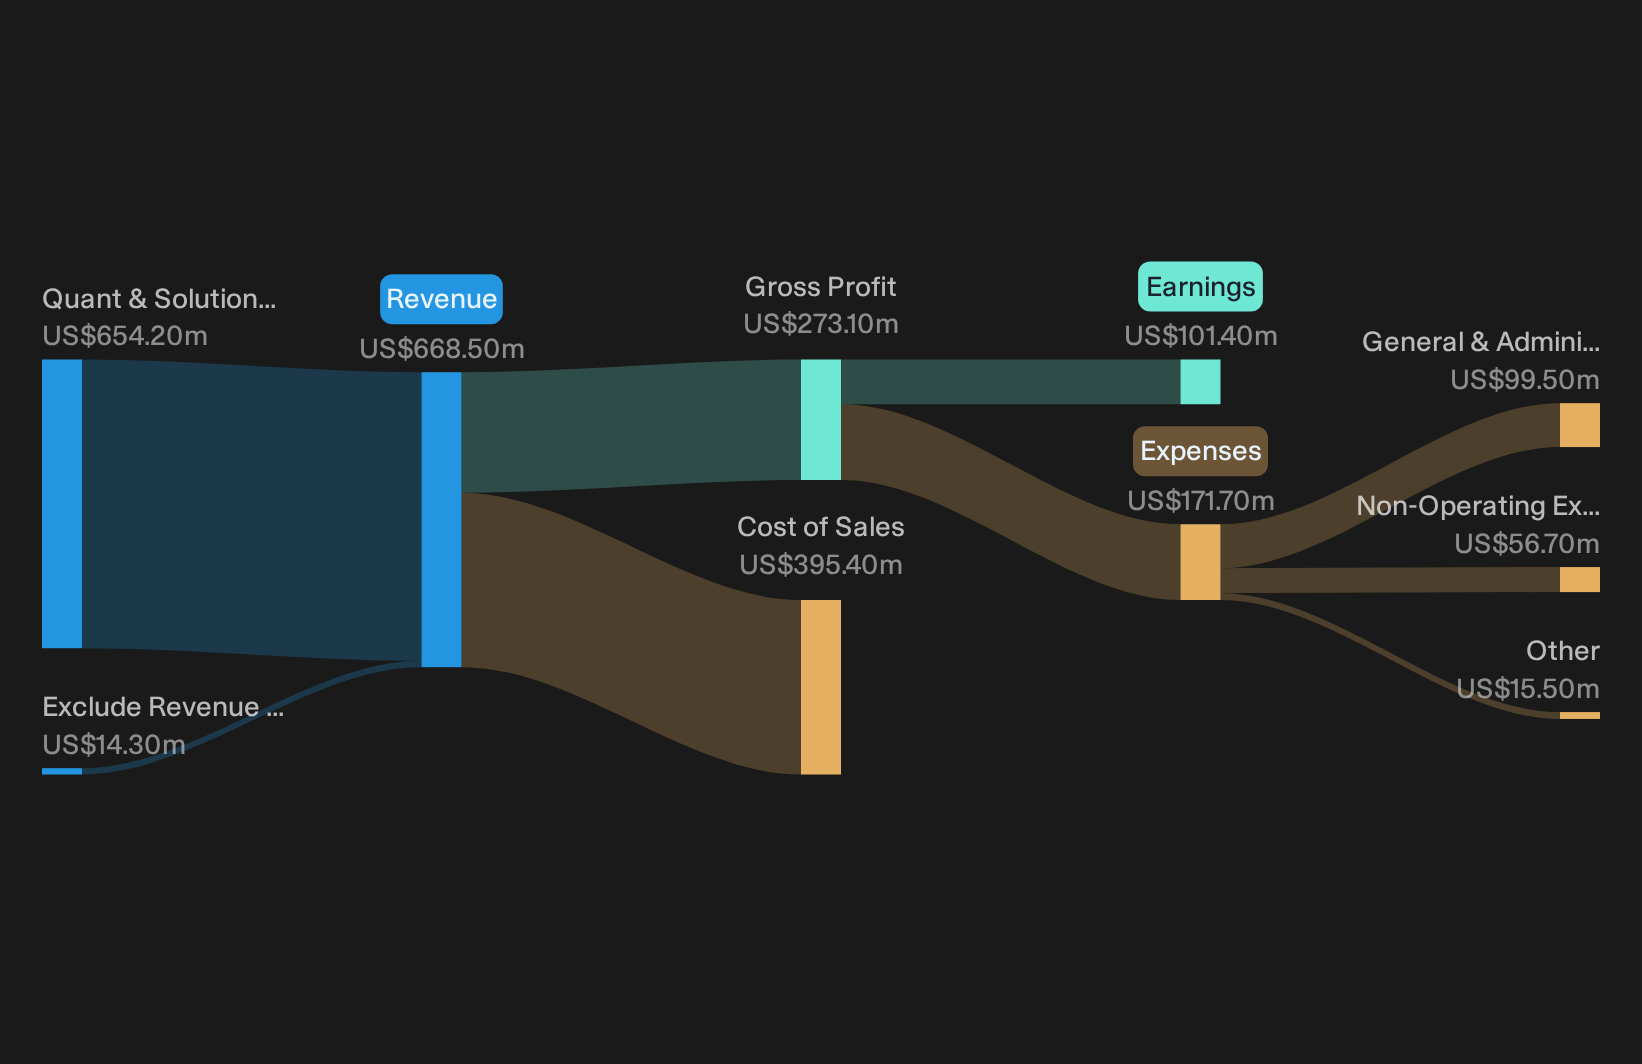
Operations: Acadian Asset Management generates about US$654 million from Quant & Solutions strategies and US$14 million from adjustments, with roughly US$458 million sourced in the United States and US$161 million from other regions.
Market Cap: US$3.3b
Acadian Asset Management provides access to a quant focused manager that can allocate client money to credit and infrastructure themes associated with higher long term yields and AI related capex. Rising U.S. rates, growing non U.S. mandate interest, and a methodical build out in systematic fixed income together create a specific risk and opportunity profile that depends in part on how one unseen pressure on its funding resilience and fee durability develops.
That funding resilience question is exactly why it is worth reading the analysis report for Acadian Asset Management to see how Acadian Asset Management’s model could react if conditions accelerate or stall
Liontrust Asset Management (LSE:LIO)
Overview: Liontrust Asset Management is a London based asset manager running equity, fixed income and multi asset funds, giving indirect access to infrastructure and AI related financing themes.
Operations: Liontrust Asset Management generates about £134 million of revenue from Investment Management activities, reflecting its core fund management focus.
Market Cap: £182 million
For investors following the AI and infrastructure funding story, Liontrust Asset Management matters because a broad fund range and growing institutional reach can quietly redirect client capital toward those capex heavy areas if demand continues to build.
"Reduced net outflows to a little under £300 million in the quarter to June 2026, alongside around £800 million of new institutional mandates, may give Liontrust Asset Management room for a future inflection if higher fee bearing institutional and international assets contribute more meaningfully to revenue and AUM."
The key issue is how one unresolved shift in client mix ultimately feeds through to fee levels and earnings resilience.
As that client mix shift plays out, read the full narrative for Liontrust Asset Management to see how Liontrust Asset Management could turn stabilising flows into accelerating earnings power.

Seeking Alternatives Before The Crowd?
Fresh themes are breaking out while attention stays glued to headline stories. Consider your positioning as momentum rotates into under the radar ideas.
- Explore resilient income opportunities by scanning the 1 dividend fortresses before yields change or valuations adjust and the most robust payers move beyond your preferred range.
- Look for emerging AI momentum with the 39 profitable AI stocks that aren't just burning cash while these operators are still treated as niche stories rather than widely recognized market leaders.
- Evaluate long term demand themes with the 16 top copper producer stocks as infrastructure and electrification spending continue to shape attention on these producers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com