
Does AI Support Upgrade Change The Bull Case For Metcash Stock?
- Coveo Solutions Inc. previously announced that Metcash has widened its partnership to add AI-powered conversational tools to Metcash's B2B customer communications portal, with plans to extend similar support into the agent desktop and build on prior AI use in the Sorted online marketplace.
- This deeper AI rollout signals that Metcash is investing in customer service efficiency and content infrastructure, which matters for cost control, support quality, and how independent retailers experience the wholesale platform day to day.
- We will now see how Metcash's investment narrative could be shaped by this AI driven upgrade to its B2B communication platform.
Scan beyond Metcash and this AI rollout by comparing it with a curated field of wholesalers and retailers that are leaning into similar technology shifts through our 92 AI infrastructure stocks.
Metcash Investment Narrative Recap
To own Metcash, you need to be comfortable with a distributor that leans on diversification across Food, Liquor and Hardware, while working with relatively thin net margins of 1.6%. The key near term swing factor is execution in Hardware and broader trade activity, given the risk of lower volumes and pressure on store profitability.
The biggest risk right now is margin pressure across several fronts, from Liquor competition to customers in Superior Foods testing cheaper options. The Coveo AI expansion looks incrementally helpful for service quality and support efficiency, but it does not meaningfully change those volume and margin questions on its own.
The most relevant context for this AI move is Metcash's push to build a more resilient Food segment after acquiring Superior Foods. That acquisition is intended to spread earnings across more customers and channels, supported by a logistics footprint that needs reliable digital tools to keep orders flowing smoothly.
Seen against that backdrop, the upgraded Coveo partnership looks like plumbing for those larger catalysts. Better B2B service, more consistent guidance for support teams and tighter content infrastructure can all help Metcash execute on diversification, while still leaving the core risks of Hardware softness, Liquor margins and declining tobacco volumes firmly on the table.
Metcash AI Rollout Against Analyst Expectations
Metcash's analyst playbook sketches out where this AI driven customer platform sits against the broader financial picture. Forecasts point to revenue rising by 2.1% a year and earnings moving from A$279.1 million today to A$310.9 million by 2029, helped by a modest lift in net margin from 1.6% to 1.7% if the business hits those targets. That is an earnings increase of about A$31.8 million off the current base, which gives a rough sense of how much extra profit the group is expected to generate if Food, Liquor and Hardware all pull their weight.
Metcash's narrative projects A$18.5 billion revenue and A$310.9 million earnings by 2029. This requires 2.1% yearly revenue growth and an earnings increase of about A$31.8 million from A$279.1 million today.
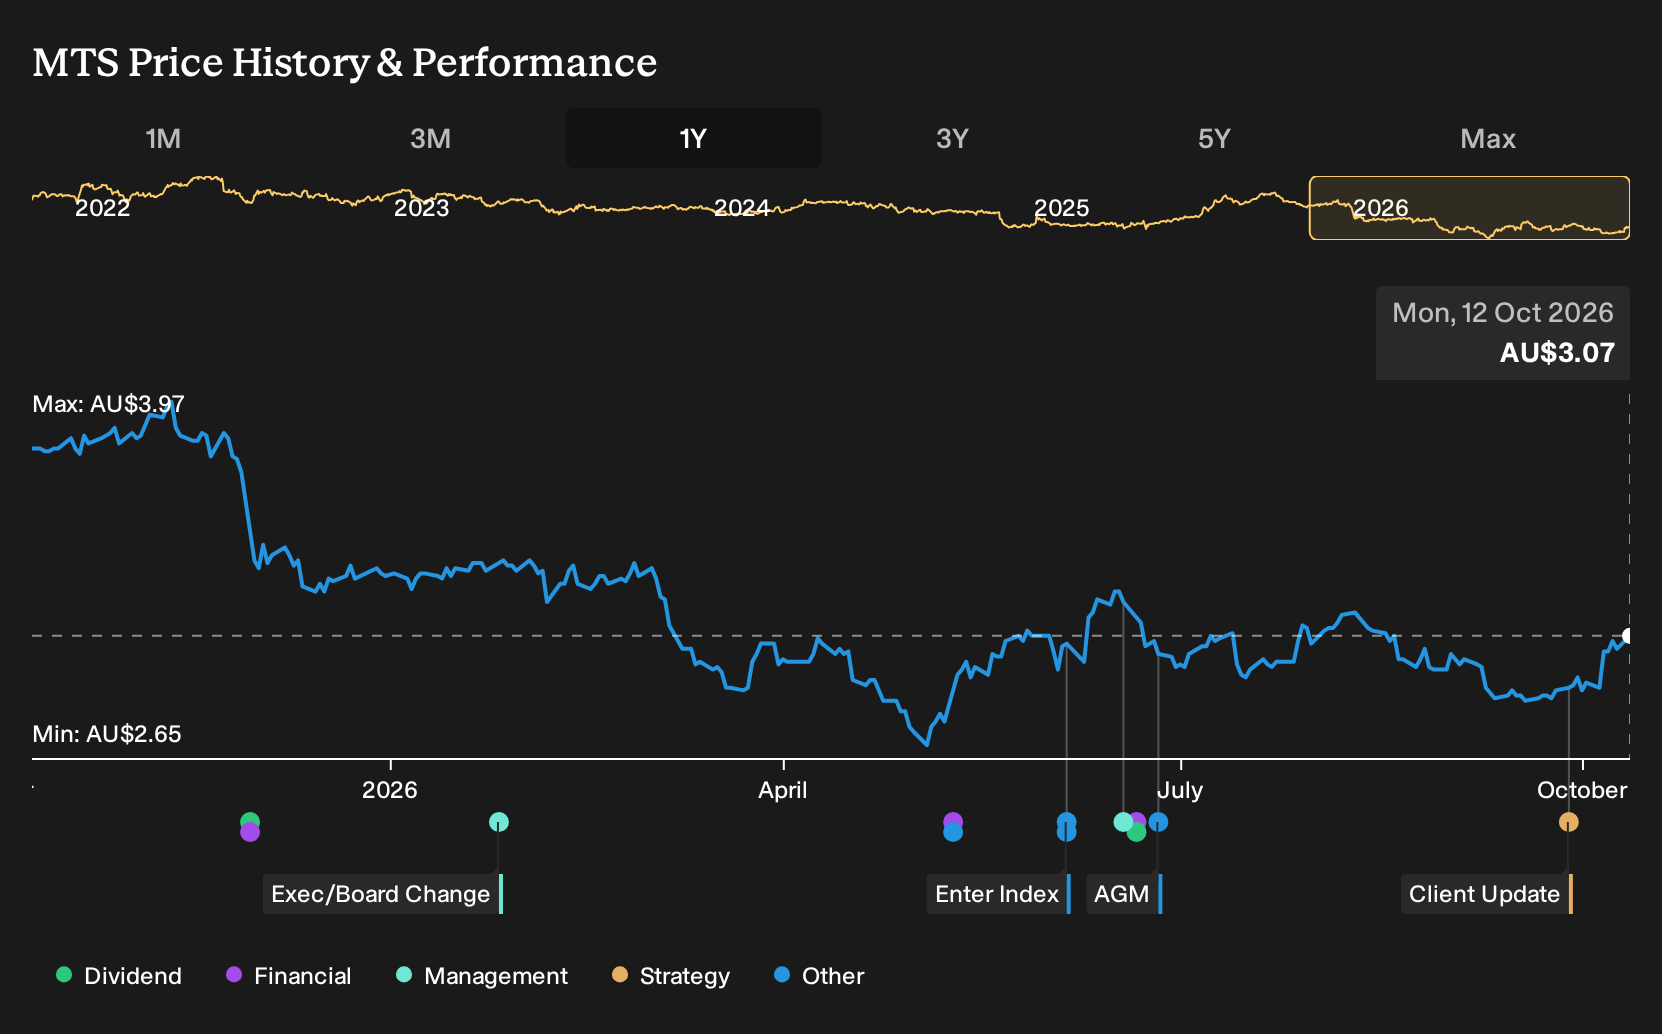
Those same consensus numbers underpin the current valuation debate. Analysts cluster around a A$3.44 price target, built on the idea that by 2029 Metcash could be earning A$310.9 million on A$18.5 billion of sales while trading on a P/E of 15.1x, compared with about 12.0x today and below the wider Australian consumer retail group on 23.6x. The AI build out with Coveo slots into that story as a potential support for smoother ordering, fewer service bottlenecks and better use of Metcash's logistics network, which together can help protect the slim net margin assumptions embedded in that forecast path.
Uncover why Metcash's fair value indicates a 12% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Metcash’s digital push as a potential catalyst, with the Sorted marketplace expected to support A$18.7b of revenue and A$321.9m of earnings by 2029. You can see how the expanded Coveo AI rollout might strengthen that story, or prompt you to question it, which is exactly why comparing competing forecasts matters.
Explore 3 other Metcash fair value estimates, including one that suggests as much as 214% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Metcash research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Metcash. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Metcash's overall financial health at a glance.
Looking for more investment ideas beyond Metcash?
Once you have formed a view on Metcash, it often pays to widen the lens and compare it with other businesses that better match your own risk, income or quality preferences. The Simply Wall St screener can help you filter the market efficiently so you spend time assessing opportunities, not just searching for them.
- If you want income resilience front and center, start with a curated set of high yield payers by checking out 5 dividend fortresses.
- For investors who care most about capital preservation and steadier balance sheets, focus your shortlist using the 7 resilient stocks with low risk scores.
- If you are hunting for quality that is not yet widely followed, build a watchlist around the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com