
Asian Growth Stocks With High Insider Ownership In October 2026
In October 2026, the Asian markets are experiencing a period of volatility influenced by global geopolitical tensions and fluctuating energy prices, similar to trends seen in other major economies. Amid these uncertainties, investors are increasingly focusing on growth companies with high insider ownership as they often indicate strong confidence from those closest to the business.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meiko Electronics (TSE:6787) | 19.2% | 34% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| HUMAN MADE (TSE:456A) | 29.1% | 28.7% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 46.1% |
We'll examine a selection from our screener results.
Beijing Enlight Media (SZSE:300251)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Beijing Enlight Media Co., Ltd operates in the investment, production, and distribution of film and television series both in China and internationally, with a market cap of CN¥32.56 billion.
Operations: The company generates revenue through its core activities of investing in, producing, and distributing films and television series across domestic and international markets.
Insider Ownership: 12.3%
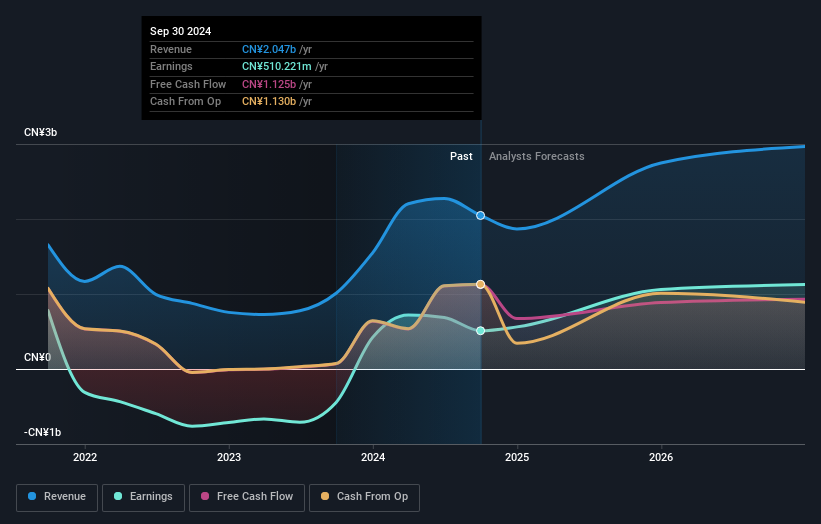
Beijing Enlight Media's revenue is forecast to grow at 33.9% per year, outpacing the Chinese market's 16.8%. Despite recent earnings declines, with sales dropping to CNY 284.63 million for the half-year ending June 2026 from CNY 3,239.07 million a year earlier, it is expected to become profitable in three years. However, its return on equity is projected to be low at 9.6%, and its dividend yield of 1.28% lacks coverage by earnings or cash flows.
- Navigate through the intricacies of Beijing Enlight Media with our comprehensive analyst estimates report here.
- Insights from our recent valuation report point to the potential overvaluation of Beijing Enlight Media shares in the market.
Sineng ElectricLtd (SZSE:300827)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Sineng Electric Co., Ltd. is involved in the research, development, production, and sale of power electronic equipment across China and internationally, with a market capitalization of approximately CN¥13.02 billion.
Operations: Sineng Electric Ltd generates revenue primarily from the Photovoltaic Industry (CN¥4.10 billion), followed by the Energy Storage Industry (CN¥2.08 billion), Power Quality Management Industry (CN¥48.96 million), and Spare Parts and Technical Services (CN¥71.92 million).
Insider Ownership: 28.7%
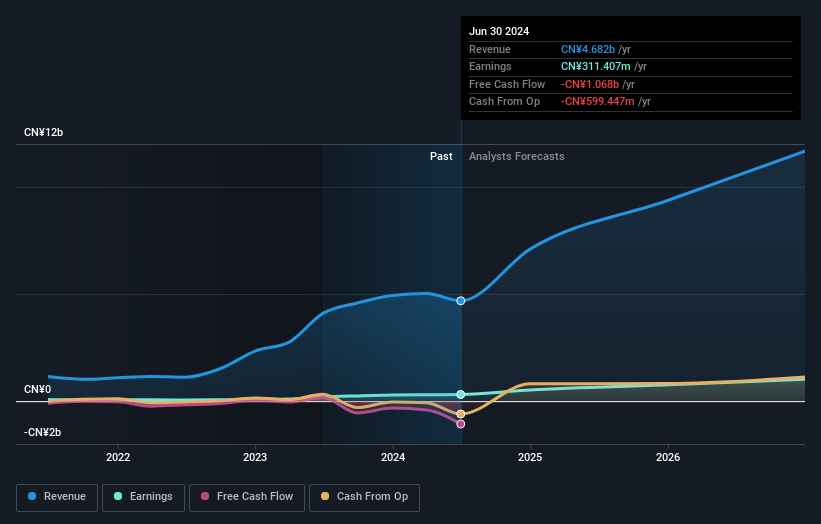
Sineng Electric Ltd. demonstrates strong growth potential with its revenue expected to rise by 20.9% annually, surpassing the Chinese market's 16.8% forecast. Recent half-year results show increased sales and net income, although earnings per share remained stable at CNY 0.39. The company trades at a favorable price-to-earnings ratio of 29.6x compared to the market's 40.4x, despite a low return on equity forecast of 16.5%. Its dividend yield is not well-supported by free cash flows.
- Click here and access our complete growth analysis report to understand the dynamics of Sineng ElectricLtd.
- Upon reviewing our latest valuation report, Sineng ElectricLtd's share price might be too pessimistic.
Tansun Technology (SZSE:300872)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Tansun Technology Co., Ltd. offers IT solutions and services to financial industry clients across China, Hong Kong, Macao, Taiwan, and internationally, with a market cap of approximately CN¥7.82 billion.
Operations: Tansun Technology Co., Ltd. generates its revenue by providing IT solutions and services to clients in the financial sector across various regions including China, Hong Kong, Macao, Taiwan, and internationally.
Insider Ownership: 17.5%
Tansun Technology shows potential for growth with earnings forecasted to increase by 68.29% annually, although revenue growth is expected at a slower pace of 20% per year, still outpacing the Chinese market's 16.8%. Recent half-year results revealed a slight decline in sales and revenue to CNY 963.2 million and CNY 963.88 million respectively, while net income rose to CNY 60.02 million. Insider trading activity over the past three months is not substantial.
- Delve into the full analysis future growth report here for a deeper understanding of Tansun Technology.
- Our comprehensive valuation report raises the possibility that Tansun Technology is priced higher than what may be justified by its financials.

Next Steps
- Reveal the 496 hidden gems among our Fast Growing Asian Companies With High Insider Ownership screener with a single click here.
- Interested In Other Possibilities? Explore 25 top quantum computing companies leading the revolution in next-gen technology and shaping the future with breakthroughs in quantum algorithms, superconducting qubits, and cutting-edge research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com