
3 Undervalued Asian Small Caps With Insider Buying To Consider
In recent weeks, Asian markets have experienced a mix of volatility and opportunity, with geopolitical tensions and fluctuating oil prices influencing investor sentiment. Despite these challenges, small-cap stocks in Asia continue to attract attention due to their potential for growth and the strategic insider buying that often signals confidence in a company's prospects. Identifying undervalued small caps requires careful consideration of market conditions and company fundamentals, making them an intriguing option for investors seeking diversification in uncertain times.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 3.9x | 0.8x | 22.79% | ★★★★★★ |
| Q Technology (Group) | 3.3x | 0.2x | 46.13% | ★★★★★☆ |
| Australian Finance Group | 7.0x | 0.2x | 29.28% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.9x | 0.9x | 39.43% | ★★★★★☆ |
| Mader Group | 19.7x | 1.3x | 49.46% | ★★★★☆☆ |
| Growthpoint Properties Australia | 16.0x | 4.3x | 23.73% | ★★★★☆☆ |
| Clover | 16.0x | 1.7x | 47.68% | ★★★☆☆☆ |
| Fiducian Group | 19.9x | 2.8x | 22.52% | ★★★☆☆☆ |
| Centurion | 16.8x | 3.3x | 17.35% | ★★★☆☆☆ |
| Citicore Energy REIT | 13.4x | 10.2x | 25.72% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
D&L Industries (PSE:DNL)
Simply Wall St Value Rating: ★★★☆☆☆
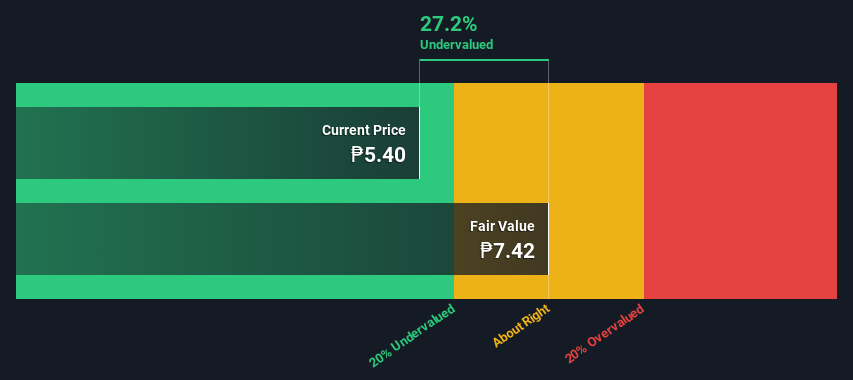
Overview: D&L Industries is a diversified Filipino company involved in food ingredients, colorants and plastic additives, oleochemicals, resins and powder coatings, and consumer products original design manufacturing (ODM), with a market capitalization of ₱64.15 billion.
Operations: D&L Industries generates revenue primarily from Food Ingredients and Oleochemicals, Resins and Powder Coatings, with significant contributions also coming from Colorants and Plastic Additives. The company's cost of goods sold (COGS) has a substantial impact on its gross profit, which has shown variability over the periods with a notable gross profit margin of 21.39% in 2019-06-30. Operating expenses are driven by sales & marketing and general & administrative costs, influencing the overall profitability metrics such as net income margin.
PE: 8.8x
D&L Industries, a smaller player in Asia, shows potential despite its reliance on external borrowing for funding. Recent earnings reveal modest growth, with second-quarter sales at PHP 0.0139 million and net income rising to PHP 0.0008 million from the previous year. Insider confidence is evident as key stakeholders increased their holdings over the past year, suggesting belief in future prospects amid an anticipated annual earnings growth of 8.38%.
- Click to explore a detailed breakdown of our findings in D&L Industries' valuation report.
Evaluate D&L Industries' historical performance by accessing our past performance report.
AEON Credit Service (Asia) (SEHK:900)
Simply Wall St Value Rating: ★★★☆☆☆
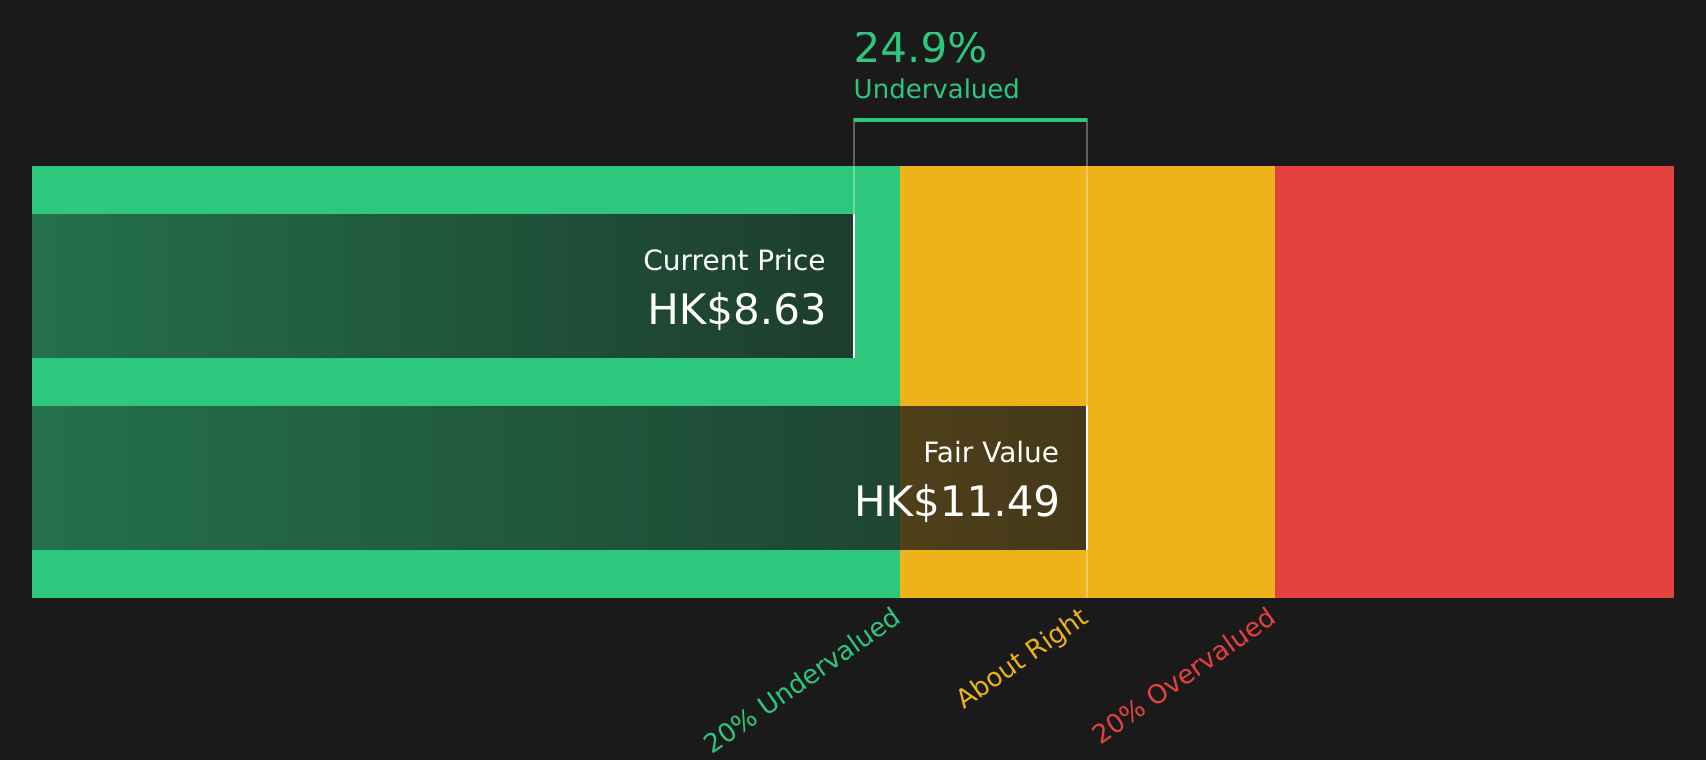
Overview: AEON Credit Service (Asia) is a financial services company primarily engaged in providing credit cards, personal loans, and insurance products, with a market capitalization of HK$2.73 billion.
Operations: The company's revenue is primarily derived from credit cards and personal loans, with insurance contributing a smaller portion. Over recent periods, the gross profit margin has consistently been at 100%, indicating no cost of goods sold reported in financial statements. Operating expenses include significant allocations to general and administrative costs, along with sales and marketing expenses. The net income margin has shown variability but generally remains above 30%.
PE: 7.8x
AEON Credit Service (Asia) demonstrates insider confidence with Yuk Kwong Lai acquiring 10,000 shares valued at HK$86,800 in September 2026. The company reported a net income increase to HK$258.82 million for the half-year ending August 2026, up from HK$233.6 million the previous year. Earnings per share rose to HK$0.6181 from HK$0.5578, reflecting growth potential despite reliance on higher-risk external borrowing for funding. A dividend hike to HKD 0.28 per share further underscores its commitment to shareholder returns amidst financial challenges and opportunities for future growth.
Aspial Lifestyle (SGX:5UF)
Simply Wall St Value Rating: ★★★★☆☆
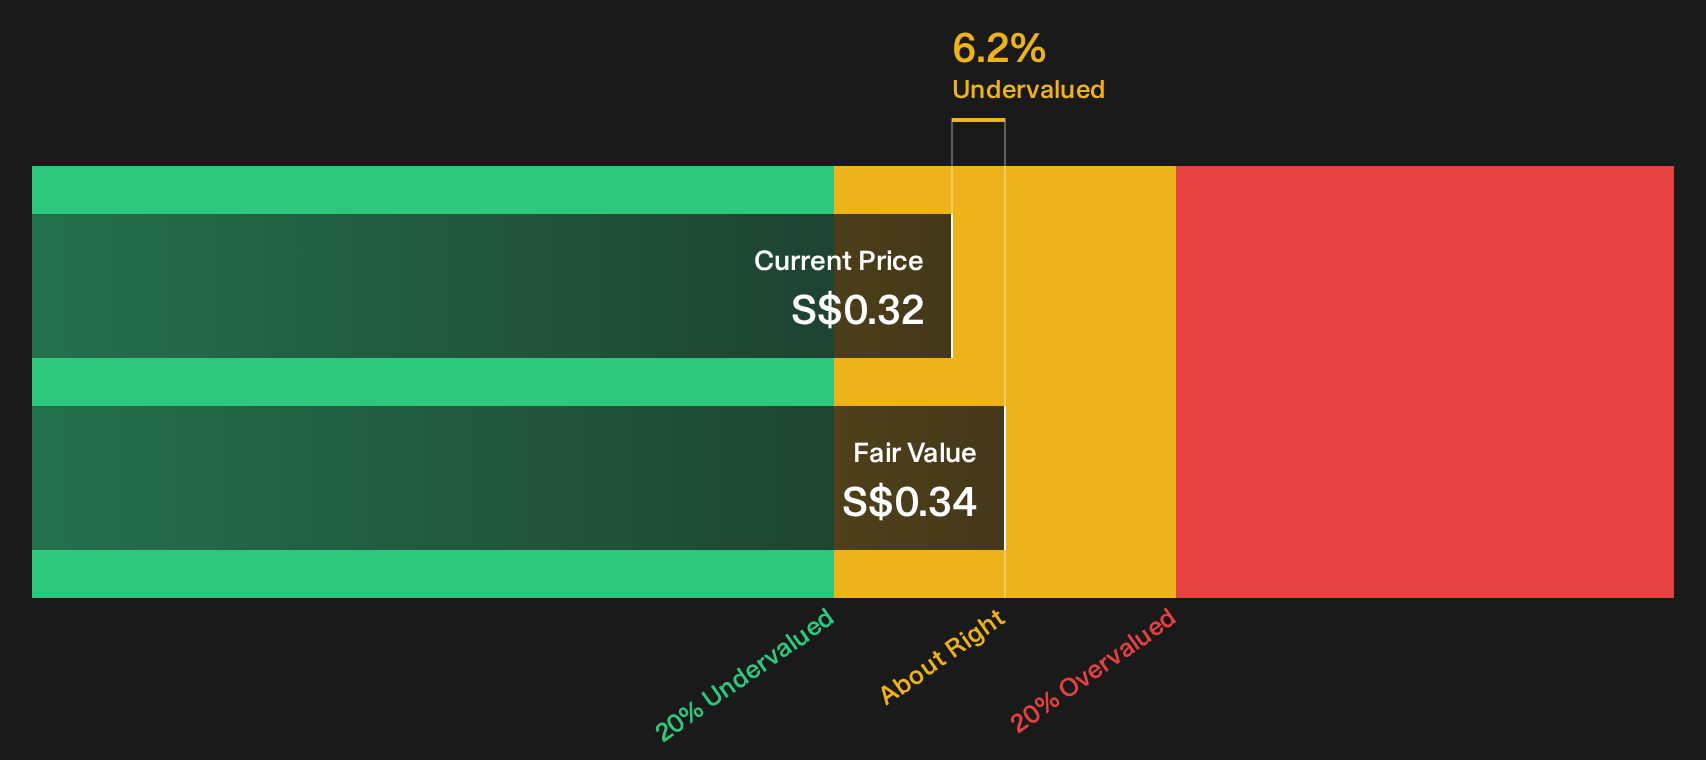
Overview: Aspial Lifestyle operates in the retail, pawnbroking, and secured lending sectors with a market capitalization of S$1.25 billion.
Operations: Aspial Lifestyle generates revenue primarily from its retail segment, with additional contributions from pawnbroking and secured lending. The company's gross profit margin has shown variability, reaching 37.46% in recent periods. Operating expenses have been significant, impacting net income margins which have fluctuated over time but recently stood at 11.35%.
PE: 6.3x
Aspial Lifestyle, a smaller company in Asia, recently issued SGD 75 million in notes due 2031 with a 5% interest rate, highlighting their reliance on external borrowing. Despite high non-cash earnings and funding risks, the company's half-year sales grew to SGD 464.16 million from SGD 367.18 million last year, while net income nearly doubled to SGD 52.4 million. Insider confidence is evident as key figures acquired about 28% of these notes, indicating potential belief in future growth prospects despite financial challenges.
Make It Happen
- Navigate through the entire inventory of 59 Undervalued Asian Small Caps With Insider Buying here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com