
Nippon Express Holdings (TSE:9147) Could Be 6% Undervalued As AI Cargo Push Expands
Nippon Express Holdings (TSE:9147) has partnered with Japan Airlines to launch a 747 freighter circuit between Los Angeles, Narita, Taipei and Singapore, targeting oversized AI and semiconductor cargo that many carriers currently underserve.
Investors have already been paying attention to Nippon Express Holdings this year, with the share price at ¥5,618 and a year-to-date share price return of 66.07% alongside a 1-year total shareholder return of 69.33%. Logistics partnerships and a recent share buyback help explain why momentum still looks constructive rather than fading.
Scan how Nippon Express Holdings stacks up against other logistics and infrastructure players riding AI supply chain demand with a curated set of 92 AI infrastructure stocks.
After a 66% year-to-date run and a completed ¥41,013.74 million buyback, Nippon Express Holdings already prices in plenty of optimism. Does that justify paying up now, or does patience for a better entry make more sense?
Most Popular Narrative: 6% Undervalued
Nippon Express Holdings closed at ¥5,618 compared with a widely followed fair value narrative of ¥5,955. The story hinges on whether its logistics footprint can earn into that gap over time.
Ongoing realignment of global supply chains, with new warehousing and production bases in the United States, South Asia and Oceania, positions the company to capture shifts in trade lanes and increase high value cross border volumes, which could lift revenue and gross profit.
Expansion of warehousing and distribution services, demonstrated by the Simon Hegele consolidation and 4.7% year on year warehouse sales growth, is increasing recurring, asset backed income and may gradually improve operating margins and earnings visibility.
See why 1 investors see Nippon Express Holdings as 6% undervalued.
Result: Fair Value of ¥5,955 (UNDERVALUED)
Still, if global freight volumes stay weaker for longer or European restructuring drags, the Nippon Express Holdings margin story that underpins this fair value could stall.
Find out about the key risks to this Nippon Express Holdings narrative.
Another View: Nippon Express Holdings Through The P/E Lens
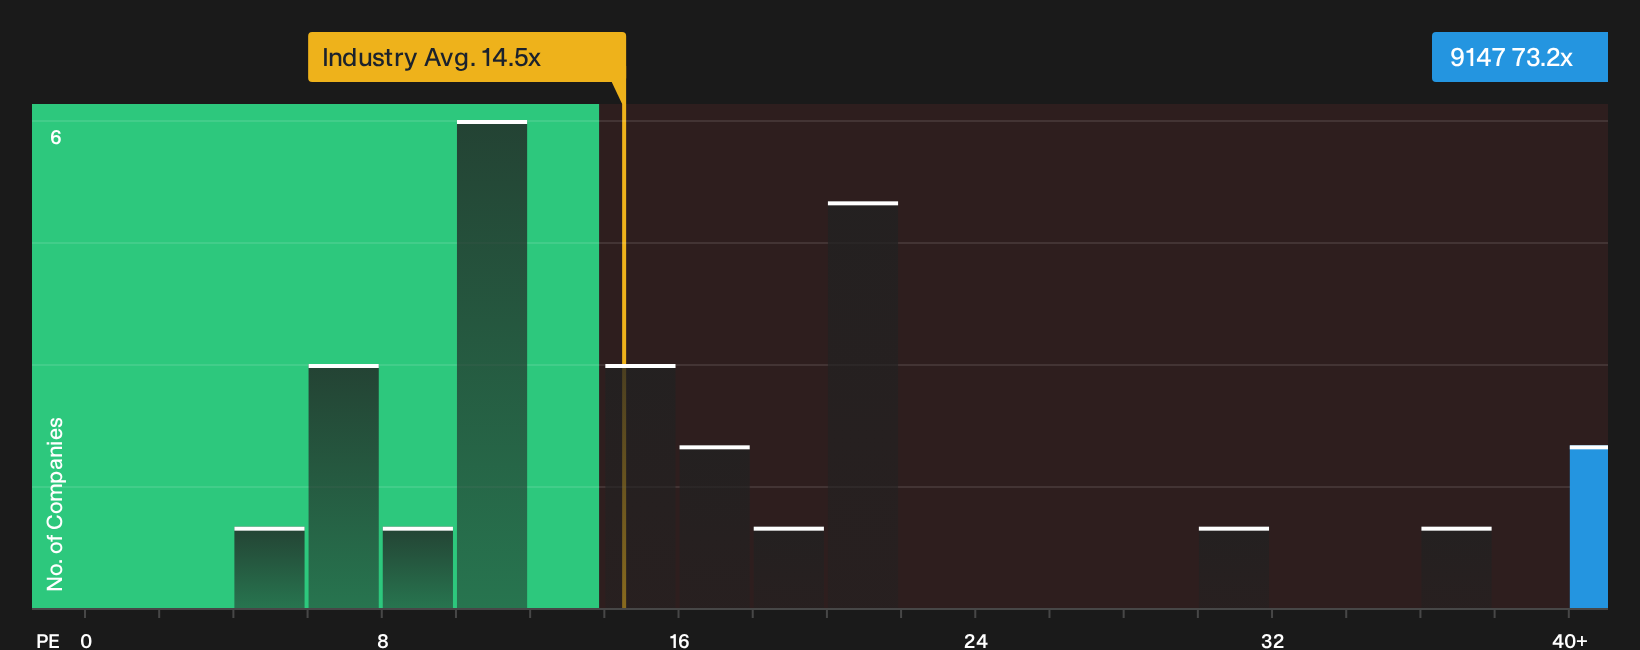
The SWS DCF model presents Nippon Express Holdings as deeply undervalued, yet the market is charging a rich 73.2x P/E compared with the JP Logistics industry on 14.5x and a fair ratio of 26.3x. That kind of gap points to real valuation risk if sentiment cools before earnings catch up.
For a closer look at what the numbers imply for today’s pricing versus that fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in Nippon Express Holdings sentiment today. If you want to move fast and anchor your own view in the data, start by weighing 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Nippon Express Holdings?
Do not stop your research with Nippon Express Holdings. Use the Simply Wall Street Screener to surface fresh opportunities that match your risk, return and income goals.
- Target resilient compounding potential by scanning a 23 resilient stocks with low risk scores that aim to keep drawdowns contained while still participating in market upside.
- Hunt for quality at a discount by reviewing a focused 12 high quality undervalued stocks that blend strong fundamentals with pricing that has not caught up yet.
- Build a sturdier foundation for your portfolio through a list of solid balance sheet and fundamentals (22 results) that can help you avoid fragile business models when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com