
Board Lot Cut Could Alter The Investment Case For SGX (SGX:S68)?
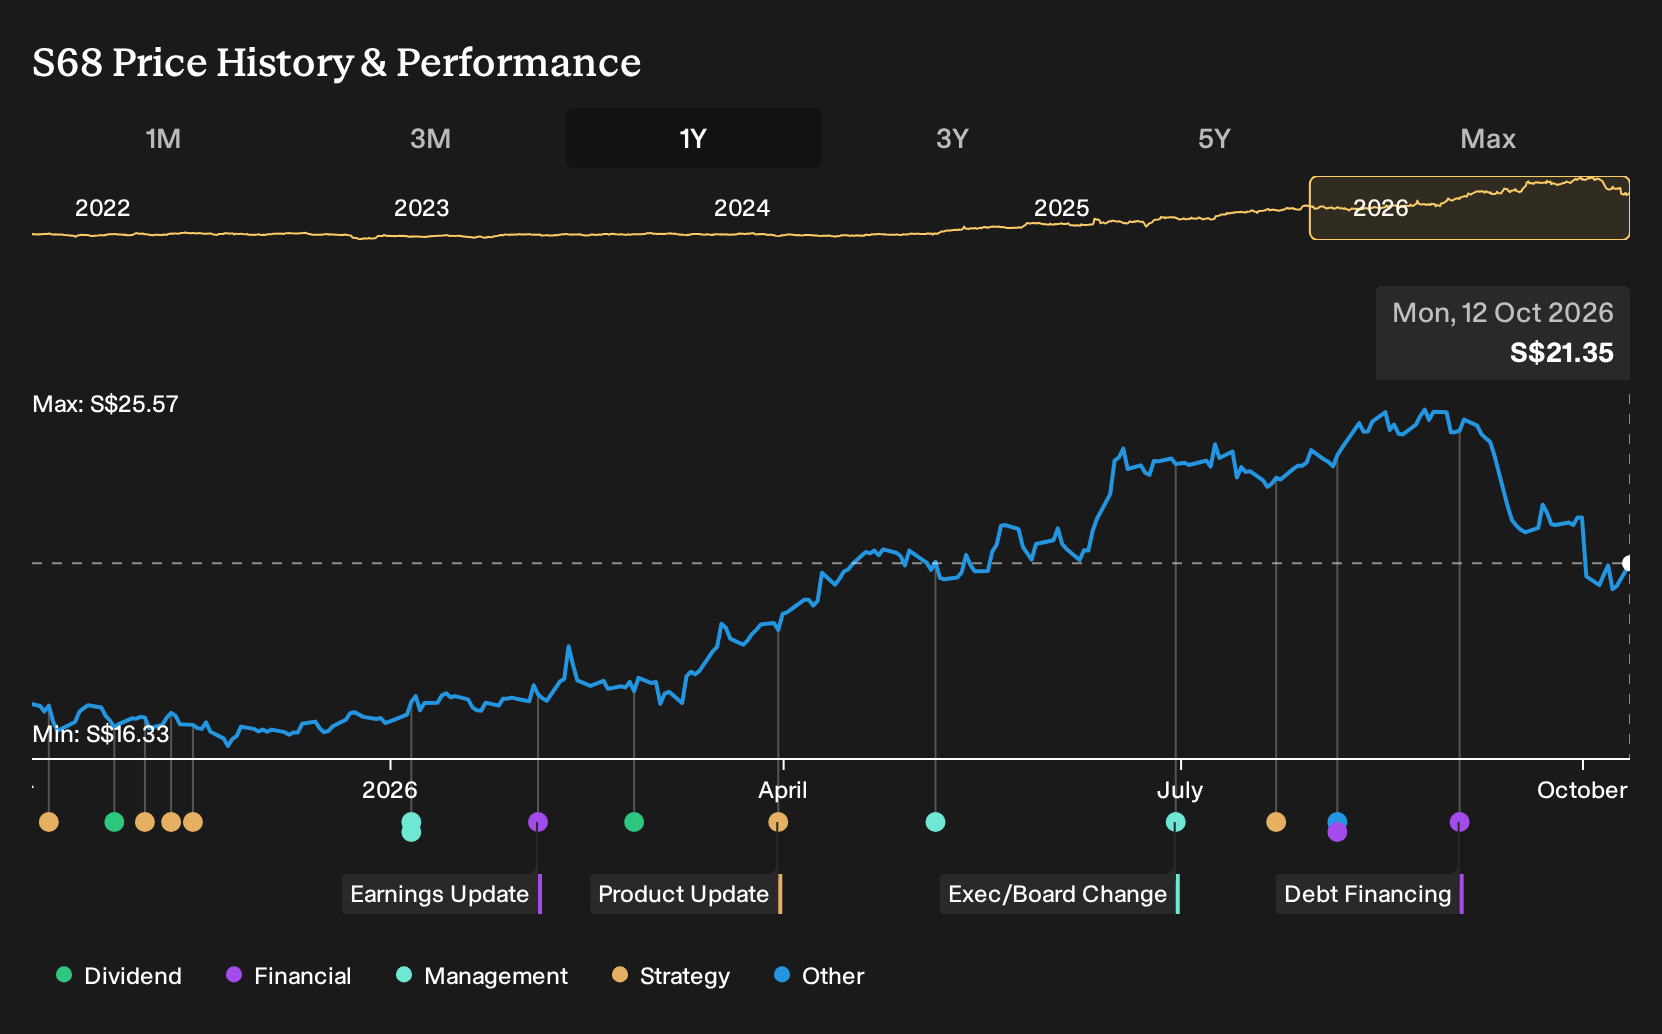
- Singapore Exchange Limited recently declared a cash dividend of SGD 0.24 with an ex-date of 30 October 2026, and cut board lots for DBS, OCBC, and UOB to 10 shares to support wider retail participation.
- This shift toward smaller trade sizes signals a focus on deepening liquidity and retail engagement in Singapore's key bank counters, which are core to SGX's securities franchise.
- We will now explore how Singapore Exchange's investment narrative is affected by the dividend decision and the bank board lot reduction.
Singapore Exchange Investment Narrative Recap
To own Singapore Exchange, you need to be comfortable with a business that lives on liquidity, product breadth, and its role as a gateway into Asia. The dividend of SGD 0.24 and board lot cuts for the three big banks speak to an emphasis on participation and depth. The closest short term operational catalyst remains trading and clearing activity across securities and derivatives, as that drives a large share of fee income.
The biggest near term risk still sits with competition for order flow from regional exchanges and alternative venues that can pull volume away. Retail oriented tweaks to market structure may not move that needle much if cross border flows soften or high volume trading periods ease off. Treat the latest measures as incremental to the story, not a reset of it.
The upcoming HSBC Singapore Exchange London Corporate Day on 12 October 2026 is the event most connected to this push on liquidity and retail access. Management gets a platform in front of global investors to explain how the cash equities franchise, derivatives book, and multi asset strategy fit together. That matters when the stock trades on a relatively high P/E multiple versus peers.
For you as a shareholder or potential shareholder, this kind of conference is less about marketing and more about execution detail. Investors will likely focus on how initiatives such as the bank board lot reduction could interact with existing growth drivers in ETFs, REITs, and equity derivatives, and how SGX is managing cost discipline, technology spend, and competitive pressure from larger regional exchanges.
Singapore Exchange Earnings Profile Behind the Liquidity Push
Analyst models around Singapore Exchange help frame what this liquidity push and dividend move are sitting on. Forecasts factor in a 6.5% yearly rise in revenue over the next 3 years and point to earnings today of SGD 698.4 million. Consensus estimates point to earnings of SGD 964.7 million by 2029, which is an increase of about SGD 266 million from current levels. On top of that, forecasts build in higher profit margins, from 44.8% now to 51.2% in 3 years, and a slight annual reduction in the share count of about 0.19%.
Singapore Exchange's narrative projects SGD 1.9 billion revenue and SGD 964.7 million earnings by 2029. This implies 6.5% yearly revenue growth and an earnings increase of about SGD 266 million from current earnings of SGD 698.4 million.
Valuation work from the same analyst set links those operational assumptions to a specific earnings profile. The models anchor on forecast revenue of about SGD 1.9b and earnings of SGD 964.7 million in 2029, with the stock hypothetically trading on a P/E of 32.2x on those earnings, compared with 39.1x today. That multiple is still higher than the SG capital markets industry at 11.1x. Any thesis that leans on the dividend or retail participation angle therefore needs to sit comfortably with a premium pricing narrative as well as the liquidity story.
Uncover why Singapore Exchange's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle around Singapore Exchange is the bullish focus on FX and derivatives as the real earnings swing factor, not just bank board lot cuts or the SGD 0.24 dividend. The highest analysts were already pencilling in revenue of about SGD 2.2b and earnings near SGD 1.1b by 2029, well above consensus, before this news. That gap shows how far opinions can spread. Treat this as a cue to compare several narratives and decide which set of assumptions fits how you think SGX’s story might evolve after the corporate day and retail push.
Explore 4 other Singapore Exchange fair value estimates, including one that suggests up to 33% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Singapore Exchange research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Singapore Exchange. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Singapore Exchange's overall financial health at a glance.
Looking for more investment ideas beyond Singapore Exchange?
If Singapore Exchange's liquidity story has sharpened your thinking, use that same lens to scan a wider set of listed companies. A focused screener can help you quickly filter for the balance sheets, income streams, or risk profiles that fit how you prefer to invest, instead of scrolling through tickers one by one.
- For investors who want sturdier finances at the core of their portfolio, start with a curated list of solid balance sheet and fundamentals (202 results) that already clear basic quality and resilience checks.
- If value is your priority, and you prefer paying less for stronger fundamentals, let the 179 high quality undervalued stocks guide you toward stocks that screen as both high quality and priced below their estimated worth.
- Income seekers who care about consistency as much as yield can use the 220 dividend fortresses to focus on companies that pair higher payouts with a more robust profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com