
AST SpaceMobile (ASTS) Stock Looks Expensive After Its Huge 3 Year Run
AST SpaceMobile has seen its share price swing sharply in both directions in recent years, and the latest setbacks and funding moves now put a spotlight on whether the current market value lines up with what sits on its balance sheet. With the stock coming under pressure as competitors secure key regulatory wins and AST SpaceMobile absorbs delays and write offs, the question for you is how that price stacks up against its book value.
- Over the past 3 years the share price has risen by a very large multiple. This now makes the gap between the stock chart and the company’s underlying net assets a central issue for anyone thinking about valuation. Greg Abel, who's set to succeed 93-year-old Warren Buffett as the next CEO of Berkshire Hathaway, recently purchased more than $24 million of the company's stock. His decision underscores how he views Berkshire's future when this change takes effect.
- SpaceX gaining FCC approval for a large direct to phone satellite network and AST SpaceMobile recording a significant satellite asset write off both influence expectations for future returns on its capital base and how much investors are paying for that equity today.
- The analysts covering AST SpaceMobile have run their own numbers. See what analysts think AST SpaceMobile's shares could be worth.
For investors, the debate is whether AST SpaceMobile’s current share price is adequately supported by its book value when set against the industry average.
If you want to test the same book value question across a wider field of opportunities, compare AST SpaceMobile with the companies in the 29 high quality undervalued stocks.
Is AST SpaceMobile Getting Expensive on Book Value?
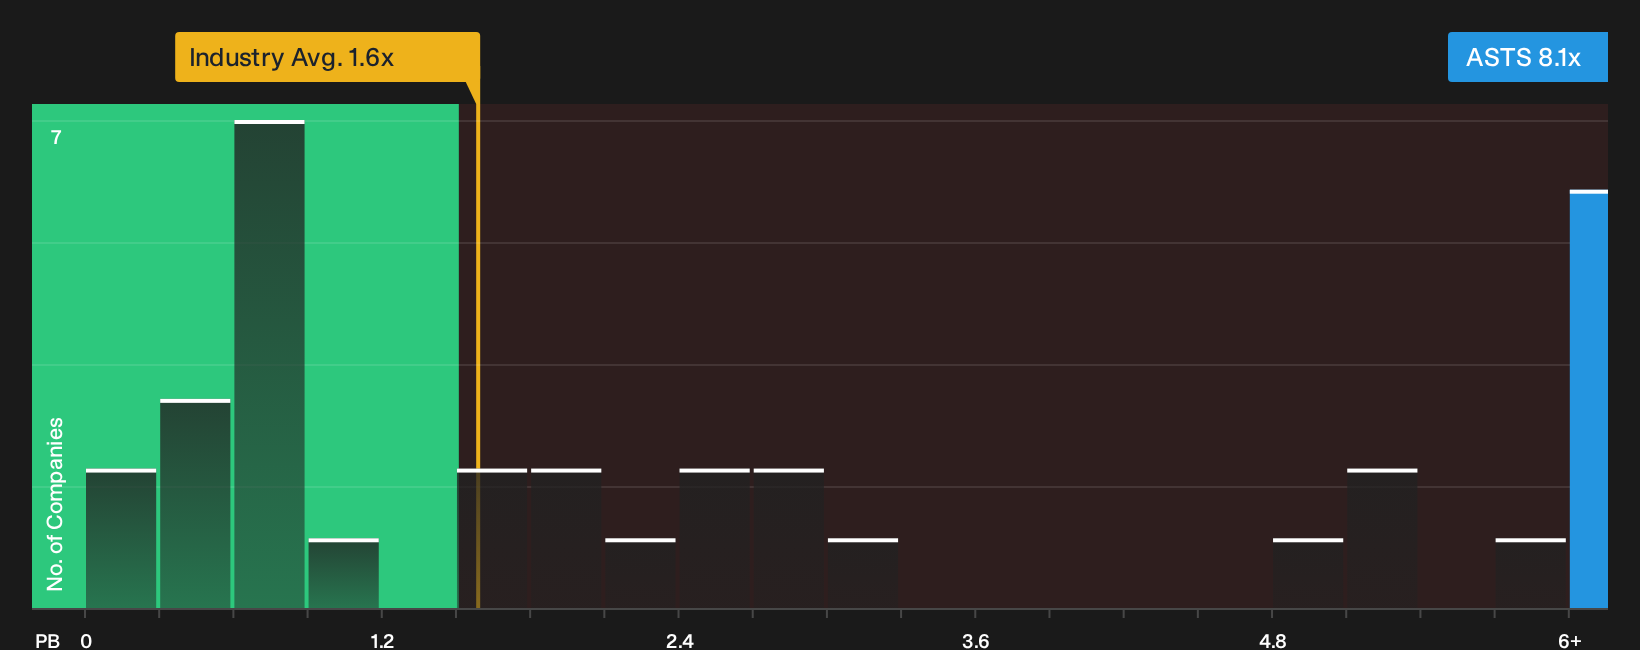
P/B is a useful yardstick for AST SpaceMobile because investors are effectively paying for a capital heavy satellite platform where physical assets and funding on the balance sheet matter a lot. On this basis, the stock trades on a P/B of 8.1x, which is well above the telecom industry average of 1.6x and still rich compared with the peer group at 13.5x.
Despite the recent sell off after SpaceX secured FCC approval for a rival direct to phone network, the current P/B still prices AST SpaceMobile at a premium to sector norms that already reflect capital intensive telecom businesses. That kind of gap usually means buyers are paying a higher price for each dollar of equity and need to weigh whether the competitive risks, satellite delays and asset write off leave enough support for that premium multiple. Explore the numbers behind AST SpaceMobile's P/B valuation.
The AST SpaceMobile Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for AST SpaceMobile pick up where the book value puzzle leaves off. They spell out which combinations of future growth, margins and earnings would need to play out for AST SpaceMobile's current share price to look high or low relative to today. Where a single ratio offers one snapshot figure, these narratives lay out the future assumptions behind that number so you can watch in real time whether reality tracks the story.
Community views on AST SpaceMobile split between a moonshot that still has room and a story the market has already priced in.
Bull case: 70% undervalued
"AST has definitive or strategic relationships with large carriers including AT&T, Verizon, Vodafone, Rakuten, Bell, and others, and its investor site says it is working with 50+ mobile network operators representing nearly 3 billion subscribers…"
Discover why this Narrative puts AST SpaceMobile at 70% undervalued.
Bear case: 27% overvalued
"At $90.94, ASTS is a victim of its own success, priced for a flawless future that ignores a $1.2B annual burn and a newly aggressive Amazon…"
Explore why this Narrative puts AST SpaceMobile at 27% overvalued.
AST SpaceMobile’s valuation is only half the story
Price and book value frame what you pay for AST SpaceMobile, but our broader checks highlight specific pressure points inside the business that could change how you view that risk reward trade off. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com