
adidas (XTRA:ADS) Following The SNICKERS Cleat Launch And The Case For Undervaluation
Why the SNICKERS cleat launch matters for adidas stock
adidas (XTRA:ADS) is leaning into seasonal marketing with SNICKERS, debuting a limited-edition ADIZERO ELECTRIC + II cleat in SNICKERS chocolate brown and Halloween themed green accents.
The product is targeted at U.S. football fans and timed around both the season schedule and Halloween. This puts fresh attention on how adidas uses collaborations to support its broader footwear and apparel portfolio.
adidas shares trade at €149.6, and the recent SNICKERS cleat news lands while the 7 day share price return of 5.13% contrasts with a 90 day decline of 17.16% and a 1 year total shareholder return that is down 19.25%, pointing to potentially fragile momentum.
Scan how adidas compares with other consumer brands that rely on hype driven launches by checking our hand picked 619 high quality undiscovered gems list before you move on.
After a 5.13% bounce in the last week but a 1-year return that is down 19.25%, adidas now asks a simple question: Is this the entry, or just a pause before better value later on?
Most Popular Narrative: 21% Undervalued
Against a last close of €149.6, the most followed narrative on adidas pegs fair value at €190, framing the recent SNICKERS cleat buzz inside a wider recovery story that leans heavily on brand reinvestment and cash flow repair.
The tension around Adidas is unusual: the business is producing some of its strongest sales numbers in years, while the market is treating the stock as though the improvement may already be nearing its peak. That gap widened dramatically after the second-quarter results. Revenue reached a record €6.74bn, currency-neutral sales rose 14%, direct-to-consumer sales increased 25%, and Performance revenue jumped 39%. Yet the shares suffered a record one-day decline because €574m of quarterly operating profit came in below expectations and management chose to spend heavily on marketing around the World Cup rather than maximize near-term profitability.
See why 7 investors see adidas as 21% undervalued.
Result: Fair Value of €190 (UNDERVALUED)
Still, the adidas story can crack if heavy marketing fails to translate into stronger cash generation or if hype-driven franchises cool faster than expected.
Find out about the key risks to this adidas narrative.
Another View on adidas valuation
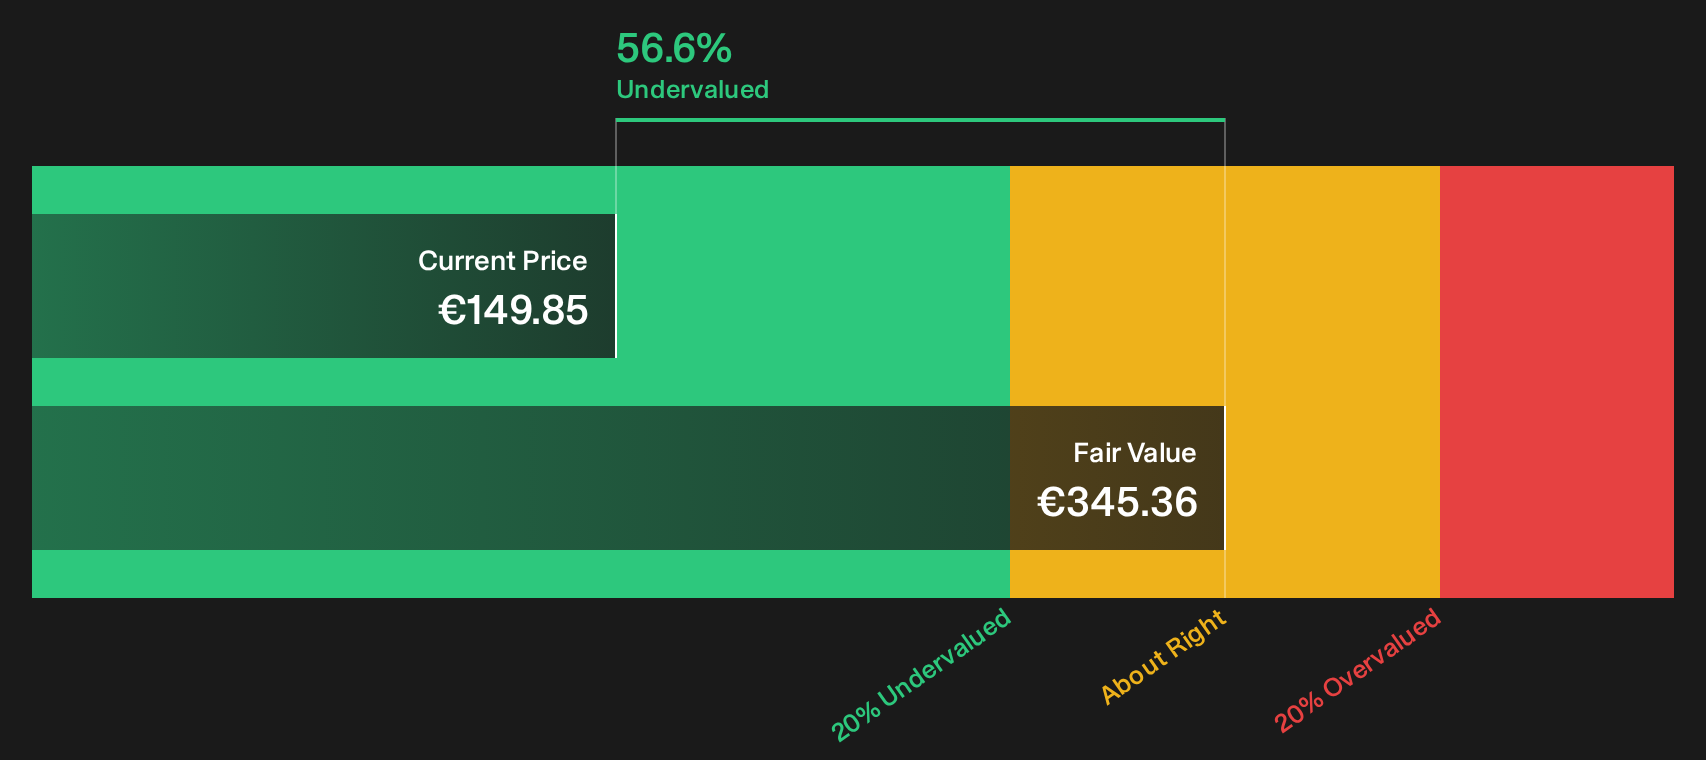
The SWS DCF model presents a very different perspective on adidas. In this view, the shares at about €149.6 sit well below an estimated future cash flow value of €345.36, which is described as undervalued and more optimistic than the €190 narrative fair value. Which lens do you trust more when both use the same cash flows but weigh risk so differently?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on adidas or simply a complex story that needs context. Act while the data is fresh in your mind and shape your own view with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond adidas?
If adidas has you thinking about timing and value, do not stop here. Broaden your watchlist and give yourself better odds of spotting the next opportunity.
- Target resilient upside with a shortlist of quality opportunities that mix earnings strength and reasonable prices through the 181 high quality undervalued stocks.
- Guard your capital by focusing on companies with sturdier finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (202 results).
- Stack potential cash returns on top of price moves by scanning for income ideas with the 220 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com