
What Incyte Buyers Were Betting On
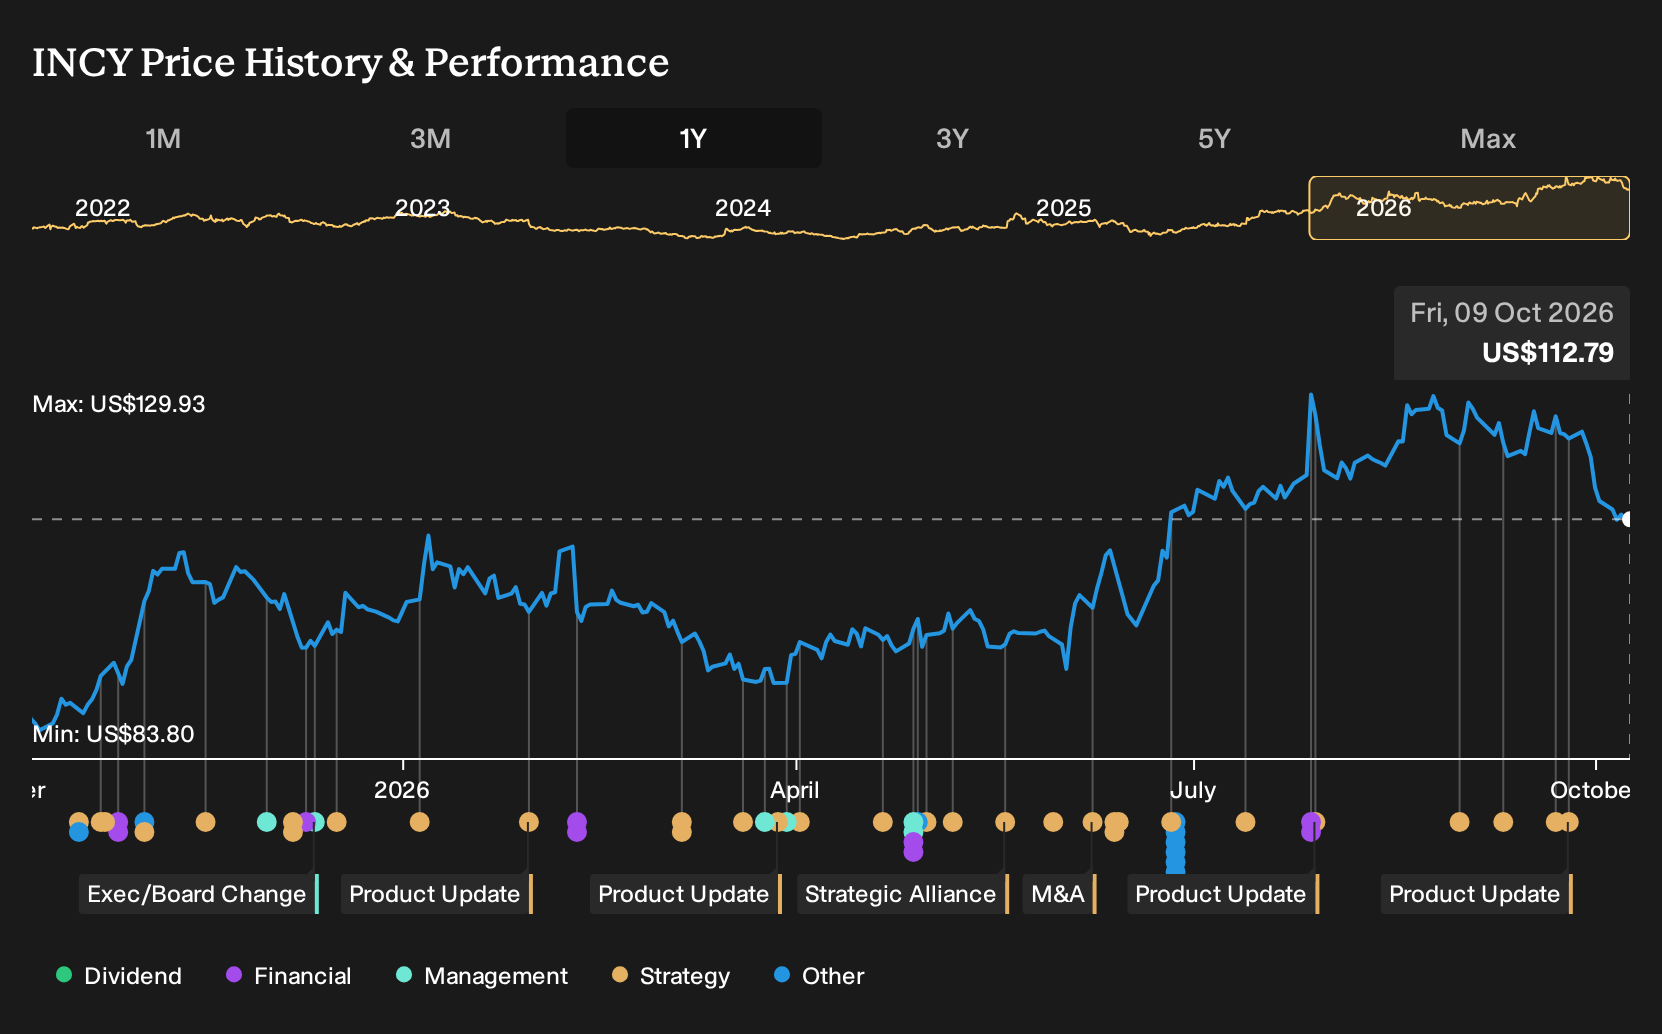
For Incyte shareholders, the return over the past year was 33.1%, including dividends. That outcome reads clean and simple. It did not feel that way on 9 October 2025, when bulls were pointing to precision oncology, Opzelura’s global rollout and a 9% above the start price fair value, while skeptics warned about Jakafi’s patent clock and pricing pressure. If you had been weighing those moving pieces then, which side of Incyte’s story would you have trusted?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
If the move has made Incyte harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Two Incyte Stories Investors Were Weighing
The shares cost US$84.75 at the start of the period, and Incyte investors were choosing between two very different but reasonable stories.
On the optimistic side, the bull narrative saw fair value at US$92, built on assumptions such as 14.3% annual revenue growth and profit margins rising toward 27.0%, supported by precision oncology and a broader international footprint.
The bear narrative pointed to a fair value of US$60, focused on heavy reliance on Jakafi and the risk that biosimilar competition and patent expiry after 2028 could affect future sales and profitability.
What The Evidence Around Incyte Actually Tested
The clearest new fact came from Incyte’s results. Total revenue was US$1,215.5m in Q2 2025 and US$1,674.0m in Q2 2026, while net income moved from US$405.0m to US$585.6m and net margin edged from 33.3% to 35.0%. That combination of higher sales and a slightly higher margin leaned toward the optimistic case, although it did not erase concerns about future Jakafi exposure.
The key lesson applies broadly. When a thesis depends on margin expansion as much as revenue growth, it is important to track both in the filings. Check whether profit per dollar of sales is actually improving, and how quickly, before treating any fair value narrative as grounded in reality.
What Incyte’s 33% Run Already Prices In
Incyte now trades at US$113, up 33.1% over the past year, while the selected Narrative’s Fair Value sits below the current price. That view leans on the idea that heavier R&D and SG&A tied to Vega and late stage programs could weigh on profitability.
For today’s level to hold, a buyer needs confidence that Incyte’s post Jakafi projects scale fast enough to support that higher cost base.
"Although the Vega deal adds a late stage hematology asset in latarcibart, the roughly US$1.27b upfront payment plus about US$50 million of additional Phase III spending in 2026 materially lifts R&D and SG&A. This could restrict operating leverage and leave earnings dependent on successful trial outcomes that are still several years from potential revenue."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Another Angle On Incyte’s Space
If Incyte sharpened your focus on drug risk, try one step wider. Big therapies often depend on more than a single flagship product.
Across oncology, immunology and neuroscience, another large group is chasing similar treatment gaps. It spreads effort across several platforms instead of relying on one anchor drug.
That business keeps directing capital into discovery and acquisitions to refresh its pipeline. Complex medicines, devices and surgical tools all support tougher disease treatment goals.
The unresolved question is how that broader mix might face pricing pressure, patent timelines and legal challenges differently from Incyte over time.
That argument has a Narrative and a number behind it. → See the company one Narrative values 22% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com