
How Investors Are Reacting To Monster Beverage Stock Free Cash Flow Outlook
- Monster Beverage is again in focus as investors weigh its long record of share gains against a business model built on high margin branded energy drinks and relatively low capital needs, which supports the company’s free cash flow profile if profitability is maintained.
- An additional angle is how differing views on Monster Beverage’s international expansion highlight that expectations for overseas demand are now central to how investors interpret its long term cash flow potential.
- We will now look at how Monster Beverage's investment narrative is affected by renewed focus on its free cash flow resilience.
Compare Monster Beverage’s cash rich formula with other branded consumer stocks by scanning our hand picked 29 high quality undervalued stocks that feature strong cash generation and disciplined capital needs.
Monster Beverage Investment Narrative Recap
To stay invested in Monster Beverage, you need to be comfortable with a story built around high margin energy drinks, disciplined capital spending, and the ability to turn that into steady free cash flow. The key near term swing factor is how well management balances price, product mix, and promotions against rising costs in freight, fuel, marketing, and aluminum.
Right now the biggest operational risk is that these expense pressures, plus softness in the Alcohol Brands segment, erode margin progress that has supported Monster Beverage’s free cash flow narrative. The latest news around free cash flow resilience does not materially change that risk profile. It mainly sharpens attention on cost control and pricing execution.
The most relevant recent update is management’s outlook for aluminum and distribution costs through the end of 2026. That guidance frames both the near term margin ceiling and the bar Monster Beverage has set for its own pricing actions, product mix, and cost efficiency programs. Investors are essentially tracking whether gross profit can absorb those inputs without squeezing earnings.
This same commentary ties directly into catalysts. International energy drink demand, the push into low and zero sugar formats, and the deeper Coca Cola distribution relationship only translate into better cash generation if Monster Beverage executes while those input costs and Alcohol Brands underperformance remain in check. That is where expectations around free cash flow durability and any future re rating of the stock will likely converge.
Monster Beverage Forecasts and What They Imply for Free Cash Flow
Monster Beverage's narrative projects US$12.1b revenue and US$2.9b earnings by 2029. Analysts are building this on 9.6% yearly revenue growth and an earnings increase of about US$800m from US$2.1b today.
Uncover why Monster Beverage's fair value indicates a 15% potential upside to its current price that could narrow quickly.
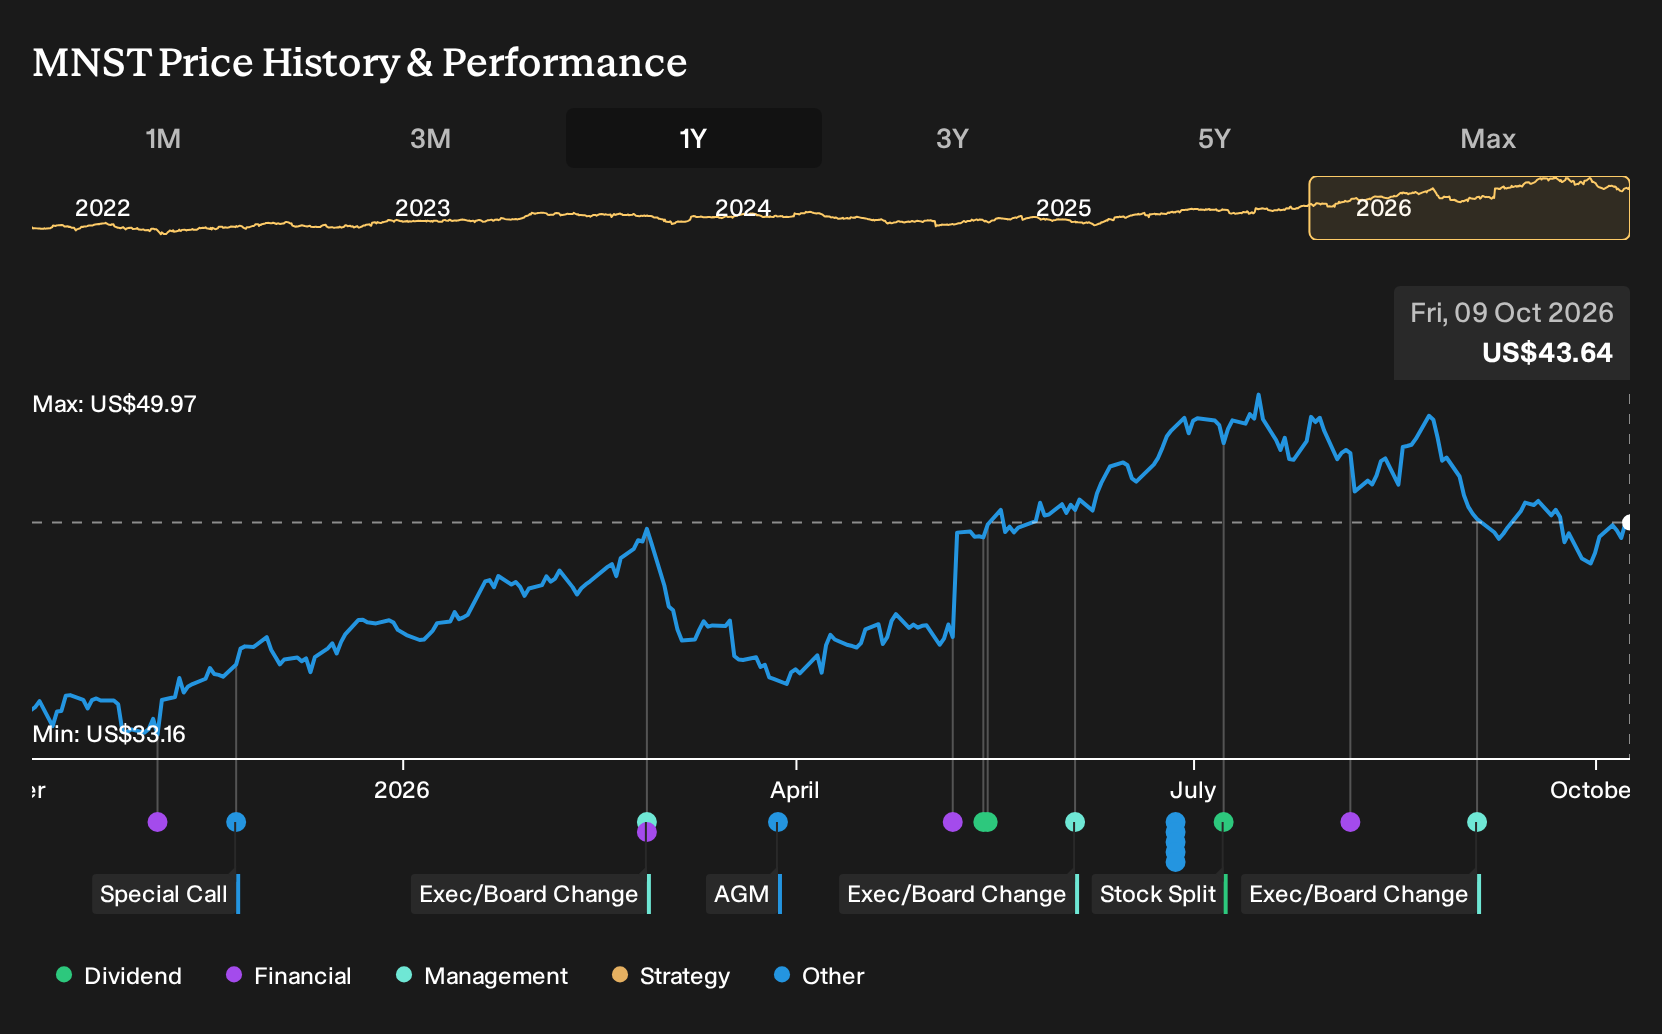
Exploring Other Perspectives
One alternate view on Monster Beverage is that international expansion could be less profitable than it looks. The most cautious analysts were previously modeling about US$11.5b of revenue and US$3.0b of earnings by 2029, with a lower 33.8x P/E. That group reads the same pre news data as a warning, not a comfort. You can use their assumptions as a stress test and decide which storyline feels closer to your own expectations if the latest news shifts the picture.
Explore 3 other Monster Beverage fair value estimates, including one that suggests as much as 6% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Monster Beverage research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Monster Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monster Beverage's overall financial health at a glance.
Looking for more investment ideas beyond Monster Beverage?
If Monster Beverage has sharpened your thinking on cash generation and capital discipline, you can use that same lens to size up other opportunities through the Simply Wall St Screener. You can quickly filter for businesses that better match your preferences for risk, return profile, and balance sheet strength.
- For investors who want to focus on stronger balance sheets first and valuation second, start with a list of solid balance sheet and fundamentals (25 results) that already filters for financial resilience.
- If your priority is cushioning your portfolio with income focused opportunities, scan a curated set of potential yield plays through the 8 dividend fortresses to see which ones align with your risk tolerance.
- When you want ideas that pair quality fundamentals with pricing that may still look reasonable, use the 20 high quality undiscovered gems to surface candidates that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com