
MeiraGTx Holdings (MGTX) Pulls Back On Valuation Focus, Is The Stock Still Cheap?
MeiraGTx Holdings (MGTX) has drawn fresh attention after recent trading left the shares at US$10.69. Performance has been mixed over the past month and past 3 months, and stronger over the past year.
Across recent months, momentum around MeiraGTx Holdings has cooled, with a 30-day share price return of 16.42% down and a 90-day share price return of 14.07% down, even as the year-to-date share price return of 36.88% and 3-year total shareholder return of 143.51% still point to a stock that has already moved a long way.
Compare MeiraGTx Holdings' recent run with other genetic medicine and pharma stocks by scanning our hand picked list of 33 healthcare AI stocks that could be setting up their own breakout moves.
MeiraGTx Holdings has already rewarded patient holders, yet the recent pullback and current US$10.69 price reset the equation. Does that cooling shift the risk reward balance back toward fresh buyers, or suggest caution on valuation?
Most Popular Narrative: 33% Undervalued
Against the last close of $10.69, the most followed narrative pegs MeiraGTx Holdings at a fair value of $16, which paints a meaningfully discounted picture once future earnings and risk factors are layered in using a 7.7% discount rate.
Although MeiraGTx is moving its AAV AQP1 xerostomia program toward a planned BLA filing and potential commercial launch, any unfavorable outcome from the fully enrolled pivotal AQUAx2 trial or regulatory pushback on relying on a single pivotal study could limit access to the estimated 165,000 prevalent U.S. patients and curb the multibillion dollar revenue opportunity that some investors expect.
See why 0 investors see MeiraGTx Holdings as 33% undervalued.
Result: Fair Value of $16 (UNDERVALUED)
Still, if the AQUAx2 xerostomia data come in stronger than the bearish camp assumes and payers support reimbursement, MeiraGTx Holdings could rapidly re-rate.
Find out about the key risks to this MeiraGTx Holdings narrative.
Another View: What MeiraGTx Holdings’ P/E Is Really Saying
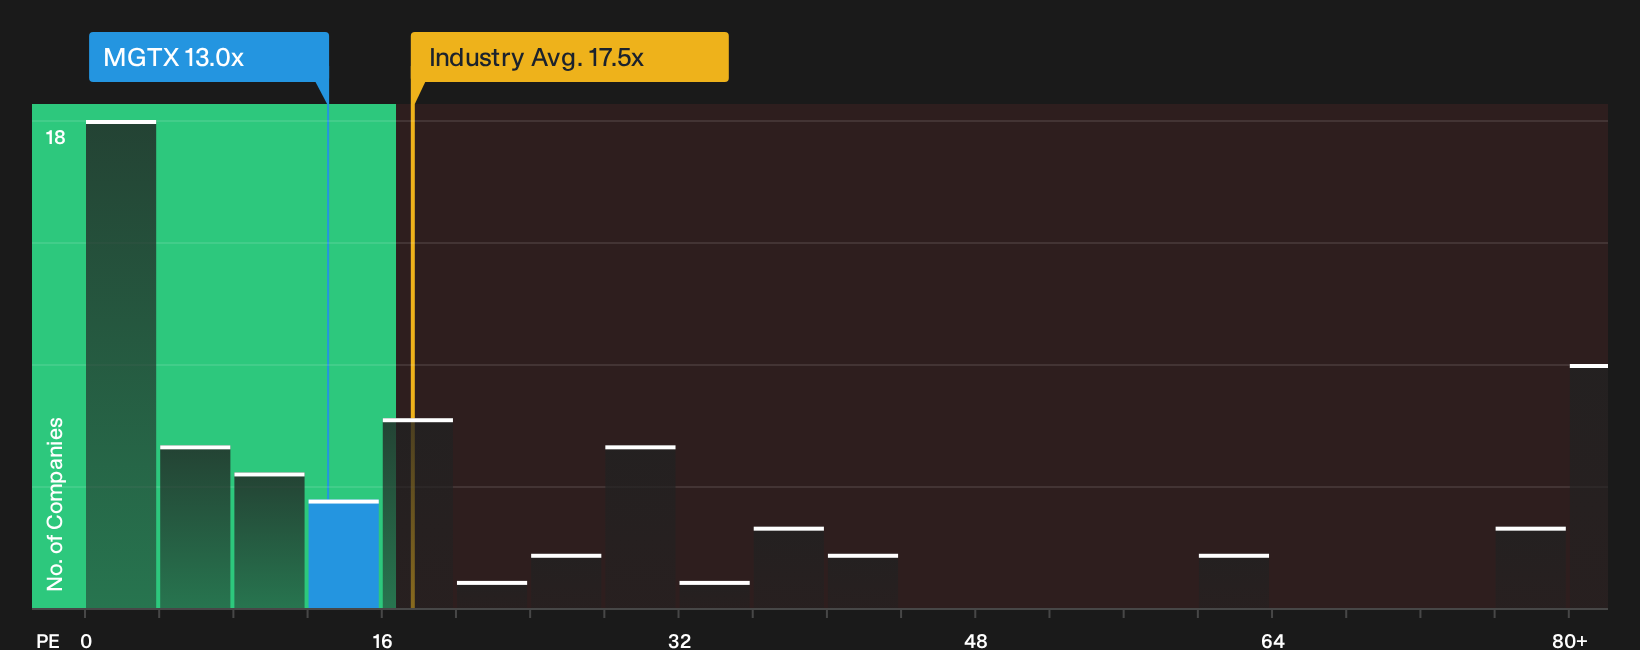
The first narrative framed MeiraGTx Holdings as 33% undervalued at $16 fair value. The plain earnings multiple tells a different story. At roughly 13x P/E, the shares trade below the wider US market on 18x, yet above both peers on 4.9x and an estimated fair ratio of 9.3x.
That gap signals investors are already paying a premium versus similar biotechs and where the ratio could settle over time, even while the stock screens cheaper than the market as a whole. The question is simple for you as a holder or potential buyer: Is that premium enough compensation for forecast earnings decline and execution risk on the pipeline, or not?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of opinions already swirl around MeiraGTx Holdings, but your view only really forms when you see the data side by side and weigh the trade off between concerns and potential upsides for yourself. To pressure test your own thesis quickly, start with the 2 key rewards and 3 important warning signs.
Looking for more MeiraGTx Holdings style investment ideas?
Do not stop with one stock. Use the Simply Wall St screener to quickly surface other potential opportunities that might fit your risk level and return goals.
- Target potential mispricing by scanning a curated pool of quality candidates through the 29 high quality undervalued stocks.
- Prioritise staying power and financial strength by reviewing the list of solid balance sheet and fundamentals (25 results).
- Hunt for off the radar opportunities before the crowd by checking out the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com